

Affiliate Account Meaning: The Profile Behind Commission Payments
An affiliate account connects a partner’s referrals to commission records and payment settings. It is not automatically a bank account, a withdrawable balance, or proof that payment is due.
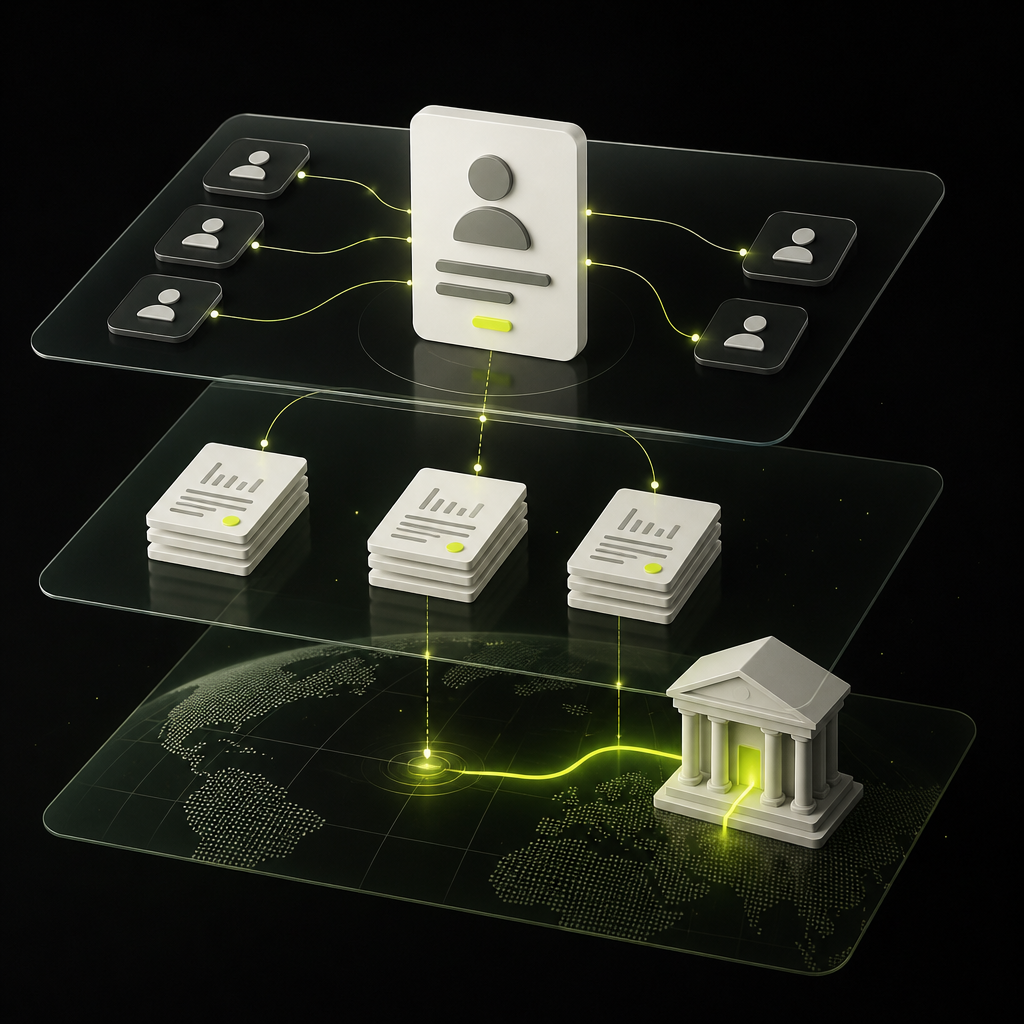
An affiliate account is a registered profile with an affiliate program or network that connects a partner’s promotional activity to commission reporting and payment settings. It typically provides an affiliate identifier, tracking links, performance reports, and tools for managing payout details.
That is the usual affiliate account meaning in marketing. For finance teams, the important distinction is that the account identifies a commercial relationship; it does not, by itself, prove that a commission is payable or that money has reached the affiliate.
This distinction matters when a program pays partners internationally. The person accessing the dashboard, the business entitled to commissions, and the owner of the receiving bank account may be different parties. Those relationships need to be explicit.
What does an affiliate account actually do?
An affiliate promotes a business through content, referral links, codes, or other approved channels. The account connects those activities to the program’s attribution and compensation rules.
A basic affiliate account definition describes access to tracking links, dashboards, and payment tools. Contract definitions add an important qualification: an account may be established only after an application is approved, as illustrated by Law Insider’s collected contractual definitions. Creating a login and gaining approval to participate are therefore not necessarily the same event.
The account generally supports these functions:
- Identification: assigns a partner or publisher identifier.
- Attribution: associates eligible referrals with that identifier.
- Reporting: displays activity, calculated commissions, and adjustments.
- Administration: records agreements, users, and payment preferences.
- Payment visibility: shows balances or payout records, depending on the platform.
The exact features depend on the program. A network account may provide access to multiple advertisers, while participation in each advertiser’s program can require separate approval.
Other meanings: corporate affiliates and banking accounts
In legal or corporate documents, an affiliate can mean an entity connected through ownership, control, or common control. That is different from a marketer earning referral commissions. The governing contract, statute, and jurisdiction determine the relationship; there is no universal ownership percentage that defines every affiliate.
Banking agreements can also use “affiliate account” for an account or sub-account associated with a related business or division. Read the agreement rather than assuming the marketing definition applies.
For a payment operator, the practical question is: Does this term identify a referral partner’s profile, a related legal entity, or an actual financial account? Each answer implies a different owner, purpose, and accounting treatment.
What information belongs in an affiliate account?
An affiliate dashboard can combine several kinds of records. Finance teams should distinguish them even when the user sees a single profile.
| Record layer | Typical contents | Question it answers |
|---|---|---|
| Access | Users, email addresses, roles | Who can operate the account? |
| Program relationship | Affiliate ID, advertiser approvals, terms | Which program can this partner join? |
| Attribution | Tracking links, codes, conversion references | Which activity belongs to this partner? |
| Commission | Rates, validation decisions, adjustments | What compensation has been earned? |
| Payee identity | Legal name, entity type, relevant documentation | Who is entitled to receive payment? |
| Payment destination | Beneficiary details, currency, payment method | Where should approved funds go? |
A login email is not a legal payee identifier. An agency employee might manage a company’s affiliate account without personally owning its commission income. Similarly, changing a display name should not automatically change the beneficiary on future payments.
A useful design principle is to keep stable identifiers for the affiliate relationship and legal payee, while versioning payment instructions separately. This preserves the connection between historical earnings and the destination authorized for each payout.
How an affiliate account connects to commission payments
Referral activity creates a potential commission
The program’s compensation model determines what activity qualifies. A sale, qualified lead, or click may trigger compensation; recurring arrangements may reward continuing customer subscriptions. These are distinct models described in Post Affiliate Pro’s commission-structure overview, not features guaranteed by every affiliate account.
A tracked event is evidence of activity. Whether it creates an enforceable payment obligation depends on the agreement and validation rules.
Validation determines what becomes payable
Programs may check eligibility, attribution, refunds, or prohibited activity before approving a commission. Pending commissions can become approved or rejected; later adjustments may also occur under the terms. Rejection is an alternative outcome, not a mandatory step on the way to payment.
Approval still does not necessarily mean immediate release. Payment schedules, minimum balances, documentation, or other contractual conditions may apply. There is no universal payout threshold or timetable for all affiliate accounts.
Payment execution moves money outside the account
Once release conditions are satisfied, the payer or its provider initiates payment to the designated destination. The affiliate dashboard may then show a payment status, but the meaning of “paid” depends on the platform: it might describe release rather than confirmed recipient credit.
An affiliate balance is not automatically a bank deposit or stored-value wallet. It may simply represent commissions in an internal reporting system. By contrast, multi-currency accounts for collecting and holding funds serve a separate financial function. Do not infer custody, withdrawal rights, or deposit protection from an affiliate dashboard’s balance display.
What changes when the affiliate is overseas?
The definition stays the same, but payment configuration becomes more consequential. Keep the commission currency separate from the currency delivered to the recipient. A commission quoted in one currency does not guarantee the beneficiary receives that currency or the full displayed amount after applicable deductions.
The account should make clear who pays transfer fees, where conversion occurs, and which party sets the exchange rate. Receiving details must match the selected country, currency, and payment route—not merely pass a generic bank-account field check.
Payment method selection also affects required data and delivery expectations. The guide to local payment rails versus SWIFT explains why routing should follow the actual corridor rather than a universal preference for one method.
Tax documentation and identity checks depend on the payer, recipient, jurisdiction, and arrangement. A program-approved account is not proof that every payment-related requirement has been satisfied.
A hypothetical example: one login, distinct responsibilities
A publishing company joins an affiliate network. Its marketing manager operates the dashboard, its legal entity signs the agreement, and its finance team supplies a company bank account.
The manager leaves and a replacement receives dashboard access. The affiliate relationship and legal payee remain unchanged. Later, the company requests a new bank destination. That request needs its own authorization and validation; changing dashboard access did not authorize it.
This illustrates why “account owner” is too ambiguous for payment controls. Label the administrator, contracting party, commission recipient, and beneficiary explicitly.
Checklist: define the account before paying it
- Confirm the context: marketing profile, corporate relationship, or financial account.
- Identify the contracting parties: distinguish advertiser, network, payment provider, and affiliate.
- Separate access from entitlement: record who manages the profile and who earns the commission.
- Define balance labels: explain pending, approved, eligible for release, and paid.
- Document currency and fees: distinguish commission value from expected recipient proceeds.
- Control destination changes: preserve previous instructions and record authorization.
- Retain payment references: connect each payout to the relevant commission records and beneficiary.
The takeaway for finance teams
An affiliate account is the operational profile connecting referrals, commission records, and payment preferences. It should not collapse identity, entitlement, and settlement into one ambiguous status.
Start by documenting those boundaries in your program’s account model. When you are ready to connect approved commissions to international money movement, explore Payouts.com’s affiliate and partner payout solutions.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
PayPal Payouts: Fees, Funding, and Cross-Border Readiness
PayPal Payouts can simplify mass payments to wallet users, but wallet delivery is not the same as local bank settlement. Here is what finance teams should verify before building it into an international payment run.
Gumroad Minimum Payout: The $100 Rule and Release Checks
Gumroad’s reported standard payout minimum is $100 USD, but reaching that balance is not the same as getting paid. Separate the threshold from sale eligibility, account review, payout scheduling, and bank settlement.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.