

Credit Card Affiliate Payout: From Issuer Approval to Partner Cash
A card approval is not necessarily a payable commission—or money ready to send. Finance teams need to connect issuer validation, contractual release rules, and cross-border delivery without losing the audit trail.
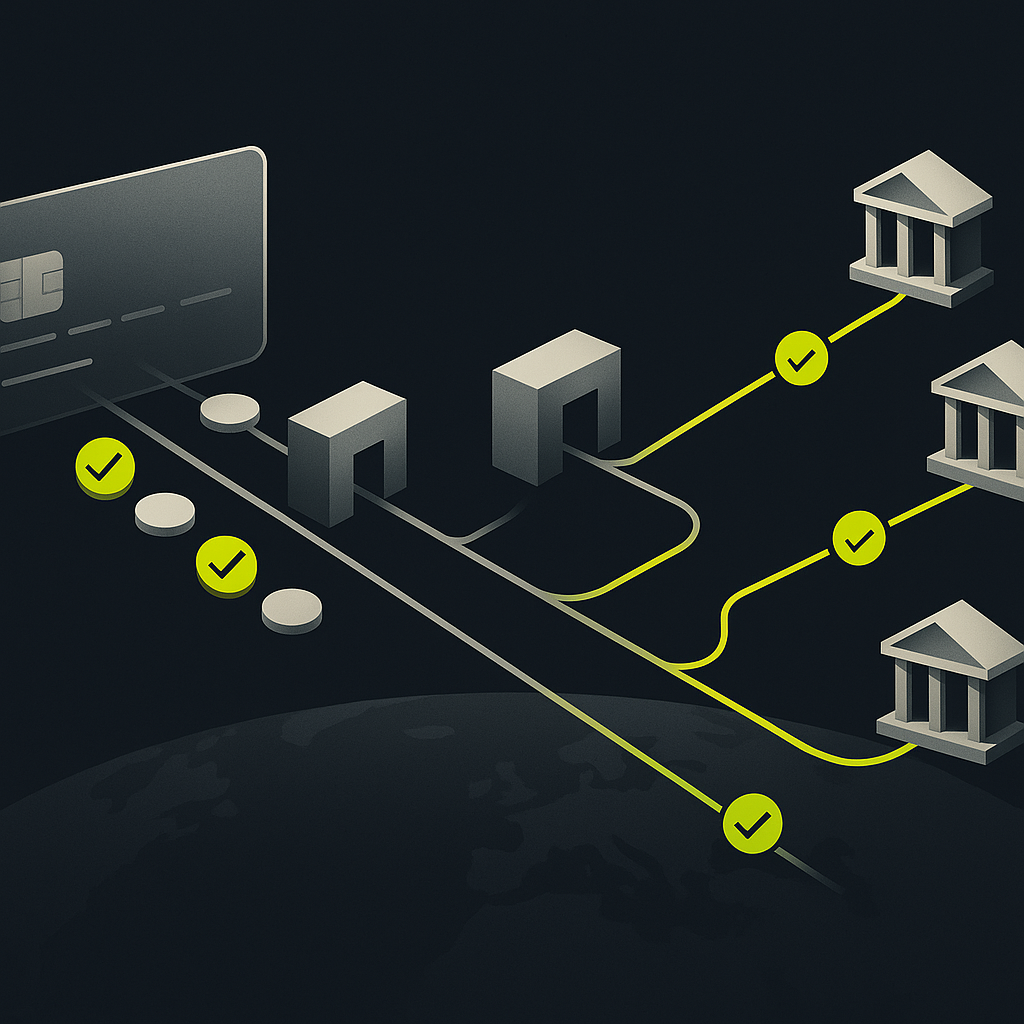
A credit card affiliate payout is the commission an issuer or affiliate network pays a publisher for a qualifying referral. The qualifying event may be a submitted lead, an approved application, or a later milestone such as activation. The contract determines the amount, validation rules, and payment schedule; the payment method determines how released funds reach the affiliate.
There is no universal commission rate or payout date. For finance teams paying international partners, the central challenge is separating cardholder approval, commission approval, and payment completion. Treating them as the same event creates premature payments, misleading balances, and difficult recoveries.
This guide concerns commissions for promoting credit cards—not paying affiliates using a credit card.
What determines the commission amount?
Start with the campaign agreement, not a public “highest-paying programs” list. Credit card offers differ by product, market, qualifying action, and partner terms. Tapfiliate’s credit card affiliate program roundup describes differing commission structures across offers, but it is secondary research, not an issuer’s binding rate sheet.
Before loading a rate into the payout system, document:
- Qualifying action: A valid lead, approved application, issued card, activation, or another explicitly defined outcome.
- Eligible traffic: Permitted countries, audiences, channels, and promotional methods.
- Attribution: Which referral receives credit, the attribution window, and duplicate handling.
- Rate version: The applicable product, currency, effective dates, and any tier conditions.
- Adjustments: Validation periods, reversal grounds, dispute deadlines, and recovery rights.
- Release terms: Payment cycle, minimum balance, documentation requirements, and any advertiser-funding condition.
For tiered agreements, specify whether crossing a threshold changes the rate for all eligible conversions or only subsequent ones. Otherwise, finance and partner management can calculate different balances from identical activity.
Define the payable event before choosing the payment rail
A tracking notification is evidence of activity, not necessarily authorization to pay. Fintel Connect’s discussion of CPA in financial affiliate marketing emphasizes connecting acquisition cost to conversion outcomes. Operationally, that means finance needs the contract’s exact qualifying event—not a generic “conversion” field.
The following is a recommended control model, not a universal issuer workflow.
| Stage | Evidence to retain | Payout treatment | Control owner |
|---|---|---|---|
| Referral tracked | Referral ID and campaign version | No release | Affiliate operations |
| Qualifying event reported | Issuer or network event reference | Pending validation | Program operations |
| Commission validated | Rate and eligibility decision | Approved commission balance | Program operations |
| Release conditions satisfied | Due date and cleared holds | Available for payment | Finance |
| Payment submitted | Payment ID and provider response | In transit | Payments operations |
| Delivery confirmed or returned | Final status evidence | Close or investigate | Finance |
Keep issuer events and payment statuses in separate fields. An application can be approved while its commission remains disputed; a valid commission can be due while its transfer is blocked by incorrect bank details. These require different owners and different remedies.
Preserve a versioned commission record
Each commission should connect the affiliate’s legal identity, campaign, referral reference, qualifying event, applicable rate, currency, and validation decision. Link adjustments to the original record rather than overwriting it.
Do not copy card applications or underwriting details into the payout ledger. Use opaque references and the minimum decision information needed to substantiate the commission. Affiliate payment teams generally do not need applicants’ sensitive financial data to calculate partner compensation.
Why an approved commission can remain unpaid
A useful partner statement distinguishes a validation deadline, contractual due date, payment submission date, and expected delivery date. Calling all of these “payout date” creates avoidable support tickets.
Validation and reversals
Depending on the agreement, duplicate referrals, ineligible traffic, attribution disputes, or failure to complete a required milestone may prevent a commission from becoming payable. Define which party can invalidate an event and what evidence must accompany that decision.
For post-payment reversals, record a separate adjustment and follow the contract’s recovery process. Do not silently deduct disputed amounts from unrelated campaigns or assume every negative balance is automatically recoverable.
Thresholds and advertiser funding
A minimum payout balance can defer release without making the commission invalid. Similarly, advertiser funding can be a contractual release condition—but only where the agreement says so. If the network owes the affiliate on a fixed date regardless of collection, delayed issuer payment is a treasury issue, not a reason to relabel the affiliate’s earnings as unapproved.
Separate operational payment eligibility from accounting recognition. Finance should apply its accounting policy to the underlying obligation rather than using a dashboard status as the sole basis for recognition.
Beneficiary and payment holds
Missing tax documentation, an unresolved identity check, or a beneficiary-name mismatch can stop delivery independently of referral quality. Show the affiliate the specific remediation needed without exposing sensitive screening information.
Move the commission across borders without changing its meaning
Keep three currencies distinct where applicable: the campaign’s commission currency, the funding currency, and the recipient’s settlement currency. Define who bears conversion costs and at what point the exchange rate becomes binding.
Multi-currency accounts can support collecting and holding funds in different currencies. They do not remove the need to reconcile the original commission obligation against the amount delivered.
Validate receiving instructions by rail
Collect details for the actual receiving route, not simply the affiliate’s country of residence. Common starting requirements include:
- US ACH: Account-holder name, ACH routing number, account number, and account type. A wire routing number may differ.
- UK domestic bank payment: Account-holder name, sort code, and account number.
- Euro SEPA credit transfer: Beneficiary name and an eligible IBAN; additional requirements depend on the provider and route.
- International bank transfer: Beneficiary and bank identifiers, typically including a BIC/SWIFT code and account number or IBAN, with address or purpose information where required.
These are starting points, not complete country checklists. Validate the provider’s current requirements, supported currencies, account eligibility, and local reporting fields before release.
A local route may reduce intermediaries, while an international transfer may better fit a recipient who wants to retain the commission currency. Use a documented local-rail versus SWIFT routing policy rather than choosing solely on the advertised sending fee.
Make the net receipt explainable
The remittance statement should show the approved commission, authorized adjustments, any applicable withholding, disclosed recipient-paid fees, conversion rate, and payout amount. Distinguish a quoted receiving amount from one the provider guarantees.
Measure contractual lateness separately from bank transit time. Faster rails cannot resolve a commission still awaiting issuer validation, and a submitted transfer is not necessarily confirmed recipient cash.
Connect marketing compliance to payout evidence
Credit card promotions require more careful controls than ordinary retail referrals. BrandVerity’s credit card affiliate compliance guidance discusses monitoring promotional content and keeping offers compliant. For finance, the practical consequence is retaining the campaign and content-approval references associated with a disputed commission.
Program rules can restrict paid search, email, claims about approval, or use of outdated card terms. Check the specific agreement rather than assuming a restriction applies to every issuer. Legal and compliance teams should determine the applicable disclosure and financial-promotion requirements in each market.
Maintain separate controls for an affiliate’s permission to promote an offer and its eligibility to receive payment. A marketing investigation should not automatically freeze unrelated earned commissions unless the agreement or applicable law supports that action.
Checklist for the next payout cycle
- Confirm the event: Match each commission to the contractual qualifying action and authoritative event source.
- Lock the calculation: Preserve the rate version, tier treatment, currency, and adjustment history.
- Resolve holds explicitly: Assign an owner, reason, and next action to every blocked balance.
- Test international delivery: Validate beneficiary fields, route eligibility, fee allocation, and FX treatment.
- Protect against duplicate payment: Keep a stable payout reference and investigate uncertain transfer status before retrying.
- Reconcile delivery: Link commission records to payment instructions, provider results, returns, and ledger entries.
- Explain the outcome: Give partners a statement that separates pending earnings, payable amounts, and funds in transit.
Build around the obligation, not the headline CPA
A dependable credit card affiliate payout operation can explain why a commission exists, when it becomes due, and what reached the partner. That chain matters more than the largest advertised commission or fastest advertised rail.
Start by reviewing a payout batch across several receiving countries. Trace every exception to its source: campaign terms, issuer validation, finance release, or payment delivery. Then evaluate Payouts.com’s affiliate payout solutions and payout automation against those documented requirements, so automation accelerates valid obligations rather than ambiguous balances.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
30 commentsRelated resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
Established Common Standards for Cross-Border Payments
Cross-border payments rely on several standards, not one global rulebook. Learn what each standard governs, where local requirements still apply, and how to turn standards into enforceable payment controls.
Xero Supplier Payment on Account: Record and Allocate Advances
A supplier advance should remain visible until it is allocated or refunded—not disappear into a reconciled bank transaction. Here is how to manage that workflow in Xero, including cross-border payment checks.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The section on attribution windows and duplicate handling is useful but raises a question we're still wrestling with: when an affiliate has multiple campaigns active and the same user clicks through different placements within the attribution window, who defines the tiebreaker logic—program ops or finance? We've had situations where operations says last-click wins but the contract actually specifies first qualifying event, and reconciling those differences manually every month is a nightmare.
In our setup, program ops defines the logic but finance has to approve it before it goes live, specifically because different tiebreaker rules can shift revenue timing across periods. We documented six scenarios—last-click, first-click, highest-value campaign, etc.—and the contract has to explicitly state which one applies, otherwise you end up arbitrating disputes with no ground truth.
In our case that logic lives in the contract and gets encoded by engineering, but finance has sign-off on the priority rules before deployment. If program ops could change attribution tiebreakers without a trace, you lose the ability to defend a commission calculation six months later when someone disputes it.
The part about minimum thresholds versus advertiser funding is underappreciated. We had a situation where our network ops kept telling affiliates their payments were 'pending approval' when really it was just a $100 threshold not met yet—completely different remediation path and created unnecessary friction with partners who thought their conversions were being disputed.
We did the same thing. The fix was adding a separate status field for payment eligibility and surfacing the actual reason in the partner portal—threshold not met, awaiting tax form, whatever. Cleared up 90% of the escalations.
Exactly. We separated "commission earned" from "payment eligible" in the partner portal and support tickets dropped by half. The hardest part was explaining to affiliates why their balance was real but not yet payable—adding a reason code field to the status helped a lot.
The guidance on reversal handling is helpful but doesn't address timing—if we reverse a commission four months after payout because the card was never activated, and the affiliate is below minimum threshold or no longer active, do you write it off or carry the receivable indefinitely? Our recovery rate on aged affiliate debits is under 30% and finance wants to stop accruing them entirely.
We treat it as a receivable and attempt recovery from future earnings if the affiliate comes back above threshold, but we write off after 18 months if there's been no activity. The key is making sure your contract explicitly gives you offset rights across payment periods, otherwise you're stuck chasing ex-partners for small balances that aren't worth the collection effort.
We set a 12-month recovery window in the contract and classify anything uncollected after that as a partnership cost written off to program expense. Carrying small receivables forever is worse than taking the hit once, especially if you're paying more in collection effort than the balance is worth.
The three-currency model (commission currency, funding currency, settlement currency) is something we're still wrestling with. Our system today only tracks commission currency and assumes settlement happens in the same, but we have partners in LATAM who want to receive USD even though campaigns are priced in EUR. Who usually owns the FX exposure in that scenario—the network or the affiliate?
We ended up treating settlement currency as a payment-layer concern, not a commission-layer one. Commission stays denominated in campaign currency through approval, then treasury handles the conversion and settlement instructions at payment time. Keeps the affiliate ledger cleaner and lets us change payment providers without touching commission records.
We handle this by treating FX as a payment execution detail—the commission ledger stays in the campaign currency, and the settlement currency choice triggers a conversion at payment time with the spread documented separately. The affiliate sees both amounts on the remittance advice. Keeps the commission record clean and makes it easier to reconcile when partners switch their preferred settlement currency mid-year.
The section on treating approved applications as payable commissions hit close to home. We burned weeks of treasury time last year trying to claw back payments we shouldn't have released because our CRM didn't distinguish between card issuance and activation milestones. Finance needs veto authority on what triggers the payment workflow, not just visibility into it after the fact.
Curious how you structured the veto—does finance review every batch before release, or did you build a rule-based gate that blocks payment until both milestones are confirmed in the system? We're considering the latter but worried about creating bottlenecks when activation data lags by days.
We added a release gate where program ops has to manually confirm the milestone before finance sees it in the payment queue. Slows things down by a day or two but completely eliminated the clawback issue.
The point about not copying card applications or underwriting details into the payout ledger is important from a PCI and data minimization perspective, but in practice we've found it creates friction when resolving disputes—program ops wants to see why an application was flagged, and if we only store an opaque reference they end up requesting access to the issuer system every time. How are others balancing audit needs with not over-replicating cardholder data?
We handle this by storing only the issuer decision code and timestamp in the payout system, then requiring program ops to pull full application context from the issuer's system when they need to investigate. It's slower for disputes but keeps the audit surface smaller and forces clearer handoff boundaries between teams.
We solved this by giving program ops read-only access to a separate dispute resolution view that pulls issuer decision codes and timestamps on demand, but never persists the underlying application data in the payout database. It adds a lookup step but keeps the audit boundary clean.
The recommendation to keep issuer events and payment statuses in separate fields is something we learned the hard way. Our old system had a single 'status' column that would show 'approved' even when the bank details were invalid, and reconciliation became a nightmare because we couldn't tell if a stuck payment was a validation issue, a compliance hold, or just bad beneficiary data.
We had the same problem and eventually created separate tables—one for commission eligibility decisions and one for payment instructions. The payment table references the commission ID but tracks its own lifecycle. Made rollback and resubmission much cleaner.
We ended up splitting into three columns: validation_status, release_status, and payment_status. Reconciliation still isn't pretty, but at least now we can see where in the pipeline things are stuck without having to dig into event logs.
The distinction between cardholder approval, commission approval, and payment completion is something we learned the hard way. We were booking commissions at application approval and then scrambling to reverse them when cards were never activated. Now we track each stage separately with its own status field, exactly like the table in this article suggests. Wish we had this framework two years ago.
Same issue here. We were accruing liabilities on every approved application and ended up with a massive reversal backlog when activation rates dropped. The validation deadline vs. due date separation mentioned in the article would have saved us months of reconciliation work.
We went through the same thing. The problem was our affiliate platform fired a webhook on approval and our payment queue consumed it directly. Adding a validation layer that checked the activation milestone before queuing the payout cut our reversal rate by about 70%.
The point about not using dashboard status as the sole basis for revenue recognition is critical. Our accounting policy says we recognize when performance obligations are met, but operations was marking things 'approved' based on payment eligibility, not contract terms. Created a complete mess during audit.
We had the exact same problem. Operations was treating 'approved' as ready-to-pay, but our contract had a 60-day activation requirement. Fixed it by splitting the workflow into two approval gates—one for commission eligibility, one for payment release.
We solved this by creating a separate workflow state called 'contractually earned' that sits between validation and payment eligibility. Accounting uses that trigger for recognition, while payments waits for beneficiary clearance and threshold logic to mark it payable. Took some convincing to get ops to maintain both fields but it cleaned up our deferrals completely.
Question on the versioned commission record recommendation: are you suggesting keeping a separate immutable log table for each commission decision, or is it enough to timestamp rate changes and link adjustments via foreign keys? We've been appending JSON blobs to a metadata column but I suspect that's going to become unmaintainable.
We went with a separate immutable event log, one row per state change with a snapshot of the decision context at that moment. JSON blobs get messy fast when you need to reconstruct who approved what rate on which date, especially during audits or disputes. Foreign keys work if your schema is already normalized, but make sure you're capturing the exact rate version and validation decision that applied at the time, not just linking to a master table that could change.
Separate log table. JSON blobs break your ability to query by rate version or audit who approved what adjustment. We keep a commission_events table with event_type, effective_timestamp, decision_user, and a foreign key back to the master commission record. The metadata column approach works until legal asks for a reconciliation report.