

Cross Border Payments: Follow the Money and the Data
International payments move through two connected chains: money movement and payment information. Finance teams need visibility into both to understand costs, resolve delays, and confirm recipients have been paid.
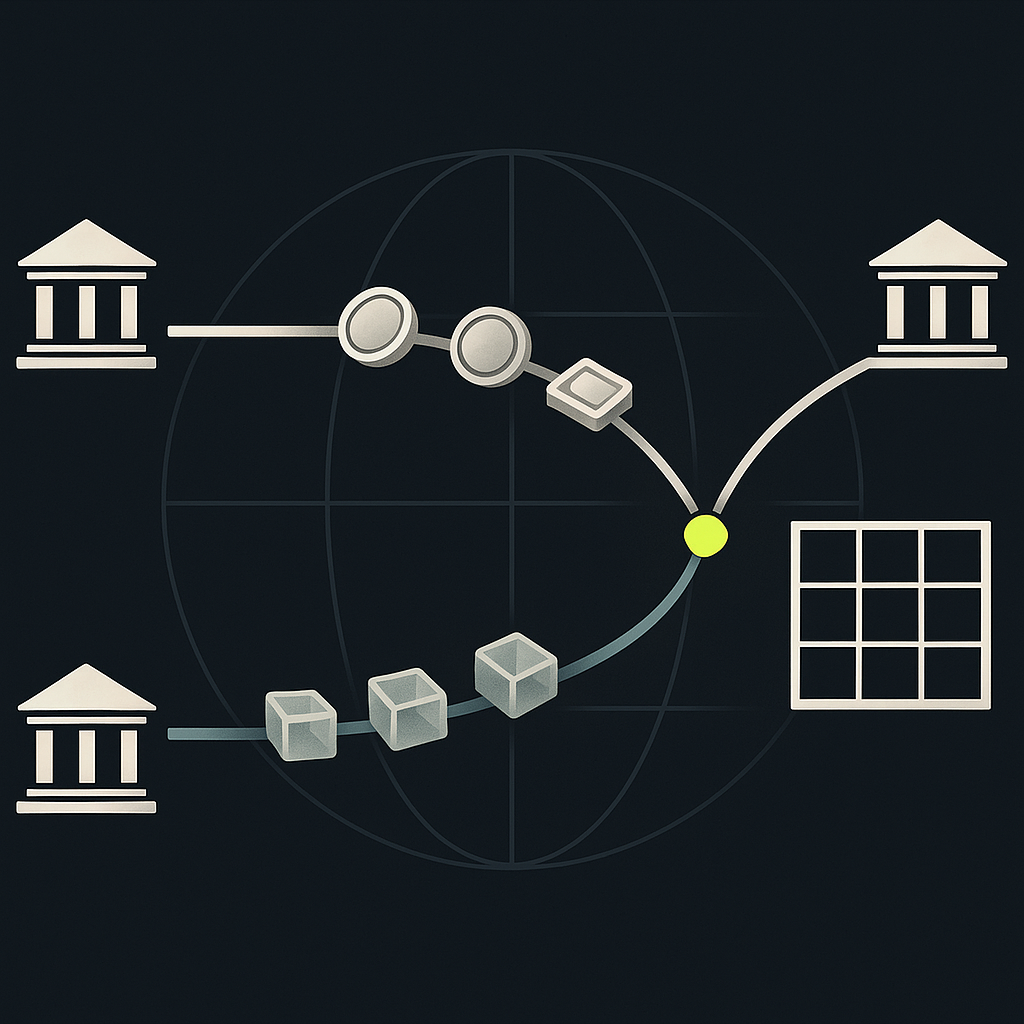
Cross border payments are transfers between payers and recipients in different countries. They can use the same currency or involve foreign exchange, and may travel through correspondent banks, local payment networks, cards, or wallets. The essential distinction: sending a payment instruction is not the same as making funds available to the recipient.
For finance teams paying hundreds of international vendors, contractors, or sellers, reliable execution requires tracking two connected chains: where the money is and what the payment data proves. A debit confirms that funds left an account; it does not necessarily establish that the beneficiary received them.
This guide explains that lifecycle, the data it needs, and how to build an evidence trail from the approved obligation to the recipient’s credit.
How cross border payments actually work
An international payout typically involves an approved obligation, a funding source, a payment provider, and a receiving institution. Currency conversion and intermediary institutions may sit between them. These activities can occur at different times and appear in different systems.
Consider a company funding a provider in dollars to pay a contractor in local currency. The provider may convert funds and pay from a domestic account in the destination market. The contractor receives a local transfer, even though the underlying commercial payment crosses borders. The provider separately manages its liquidity and settlement obligations.
Alternatively, the payer’s bank may use correspondent banking relationships to reach the recipient’s bank. SWIFT supplies financial messaging; it is not itself the account holding the recipient’s money.
The practical consequence is that the visible delivery method does not describe the entire funding and settlement chain. A fast domestic final leg can still depend on earlier funding, screening, or FX processing.
Why infrastructure improvements do not remove every delay
The Financial Stability Board’s 2025 consolidated progress report found that policy milestones had not yet translated into tangible improvements for end users globally. That is a global assessment, not a performance judgment on every provider or corridor.
The CPMI’s monitoring survey brief published in May 2026 describes progress in payment-system operating hours, fast-payment interlinking, and ISO 20022 adoption. These developments matter, but a finance team still needs to establish which improvements apply to its actual payment route.
Map the lifecycle before interpreting payment statuses
Provider status labels are not universal. “Completed” may mean released to a banking partner, credited to a beneficiary, or something else defined in the service documentation. Build an internal lifecycle and map each provider’s events to it.
| Lifecycle stage | Evidence to retain | What it does not prove | Suggested owner |
|---|---|---|---|
| Obligation approved | Invoice or earnings record; approval | Recipient details are valid | AP or payout operations |
| Funding available | Usable balance confirmation | Payment was submitted | Treasury |
| Instruction accepted | Provider ID; validation result | Funds reached the recipient | Payment operations |
| FX executed | Rate; currency amounts; timestamp | Delivery succeeded | Treasury |
| Payment released | Rail reference; release event | Beneficiary credit occurred | Payment operations |
| Recipient credited | Credit confirmation, where available | Accounting is reconciled | Payment operations |
| Reconciled | Matched obligation, cash, fees, and FX | No later return or adjustment | Accounting |
This is a control model, not a mandatory processing sequence. FX may occur before funding or within payment execution. Some providers cannot supply beneficiary-credit confirmation; record that evidence gap rather than treating an earlier event as equivalent.
Understand what each payment method changes
The delivery method affects reach, data requirements, and available evidence. It does not eliminate the need to fund the transaction or meet applicable compliance requirements.
- Correspondent banking: Supports international bank transfers across many markets, but intermediary handling can complicate fee visibility and investigations.
- Local bank delivery: Can simplify the beneficiary’s domestic receipt. The provider still needs an eligible local route and sufficient destination liquidity.
- Instant payment networks: Can accelerate the domestic leg. Cross-border availability depends on provider access or supported interconnections, not merely the existence of a domestic instant network.
- Card and wallet payouts: Depend on eligible recipient endpoints, program rules, limits, and cash-out options.
- Stablecoin transfers: Add blockchain transaction evidence, but that evidence does not establish fiat conversion or bank credit. Legal availability, custody, redemption, and off-ramp costs require separate assessment.
For method selection, use a dedicated local-rails-versus-SWIFT routing policy. The lifecycle record should remain consistent even when the delivery method changes.
Build country-specific data requirements without hard-coding assumptions
A country name alone is not enough to determine required fields. Requirements can vary by currency, payment network, recipient type, transaction purpose, and provider.
For example, a UK domestic bank route commonly uses a sort code and account number; a euro SEPA credit transfer uses an IBAN; an Indian bank route may require an IFSC and account number. These are routing examples, not complete onboarding specifications.
Maintain a versioned requirements record for each supported combination:
- Identity: Legal beneficiary name, individual or business classification, and address fields where required.
- Destination: Account identifier, bank or branch code, or eligible wallet identifier.
- Regulatory context: Payment purpose, residency, tax identifier, or supporting documentation where applicable.
- Remittance: Invoice or earnings reference, permitted characters, and field-length limits.
- Validation: Required formats, conditional fields, effective date, and provider documentation supporting the rule.
Keep structured address components in the underlying record rather than relying solely on free text. Richer message standards cannot recover missing or incorrect source data.
Use the country-by-country contractor bank payment guide as a starting point, then confirm the exact requirements for your contracted route. Format validation is not proof of account ownership; changes to beneficiary details need independent verification.
Connect cost and speed to the same transaction record
Separate quoted economics from realized economics
Store the funding currency and amount, agreed payout currency and amount, FX quote, quote expiry, explicit fees, and who bears deductions. After execution, attach actual debits, executed FX, reported deductions, returns, and adjustments.
Compare FX pricing against a timestamped reference rate for the same currency pair and quotation convention. A spread embedded in the exchange rate will not necessarily appear as a separate fee.
Keep internal investigation costs and prefunding costs separate from provider charges. Otherwise, an operationally expensive route can appear inexpensive on a fee report.
Measure the whole clock, not just rail speed
Record when the obligation became payable, when funding was available, when the instruction was accepted, and when beneficiary credit was confirmed. These timestamps separate internal approval delays from provider processing and recipient-bank handling.
If you hold destination currency through multi-currency global accounts, you may decouple FX timing from payment release. That also introduces liquidity allocation and currency-exposure decisions. Available destination balances are an operating choice, not free acceleration.
A hypothetical example: one payment, conflicting evidence
A company pays an overseas contractor in local currency. Its provider accepts the instruction, debits the funded balance, and reports the payment as released. The contractor says nothing has arrived.
The team should not immediately send another payment. Instead, it should locate the original obligation, provider payment ID, bank reference, beneficiary details used, and latest event. It then asks the provider whether credit is confirmed, pending, rejected, or unknown.
If a return follows, accounting matches it to the original payment and records any fee or FX difference. A replacement requires an explicit link to the failed attempt and confirmation that the original cannot still credit the recipient. This prevents an investigation from becoming a duplicate-payment problem.
Checklist: make every payout explainable
- Define the obligation: Retain its amount, currency, due date, recipient, and approval.
- Validate the destination: Apply current route-specific requirements and independently verify sensitive changes.
- Confirm funding and pricing: Record usable balances, quote terms, fees, and expected deductions.
- Preserve identifiers: Link the obligation, payment attempt, provider reference, and rail reference.
- Normalize events: Document what each status proves and retain both event and receipt timestamps.
- Assign uncertainty: Give pending or unconfirmed payments an owner and escalation path.
- Close the accounting loop: Reconcile cash, liability, fees, FX, and any return without overwriting history.
Start with traceability, then automate
Reliable cross border payments require more than broad geographic coverage. Finance must be able to explain what was owed, what was sent, what arrived, and what remains uncertain.
Start by tracing a representative payout through the full lifecycle. Then use Payouts.com’s payout automation as part of a connected money workflow, evaluating the supported routes and evidence available for your needs. Automate the repeatable steps while keeping ownership clear wherever the evidence stops.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
How to Pay International Contractors: A Country-by-Country Bank Payment Guide
A successful contractor payment delivers the agreed amount—not just a completed transfer instruction. Build a country-specific payment plan around bank details, currency, fees, and the date funds become available.
How Does Etsy Pay Sellers? From Sale to Bank Deposit
Etsy pays sellers through Etsy Payments, but a completed sale is not the same as cash available in the bank. Understand deposit schedules, deductions, reserves, and international payout routes.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.