

Cross Border Payments Using Blockchain: Control the Handoffs
Blockchain can improve the settlement leg of an international payment without fixing every step around it. Finance teams need to control conversion, custody, compliance, and recipient credit—not just the blockchain transaction.
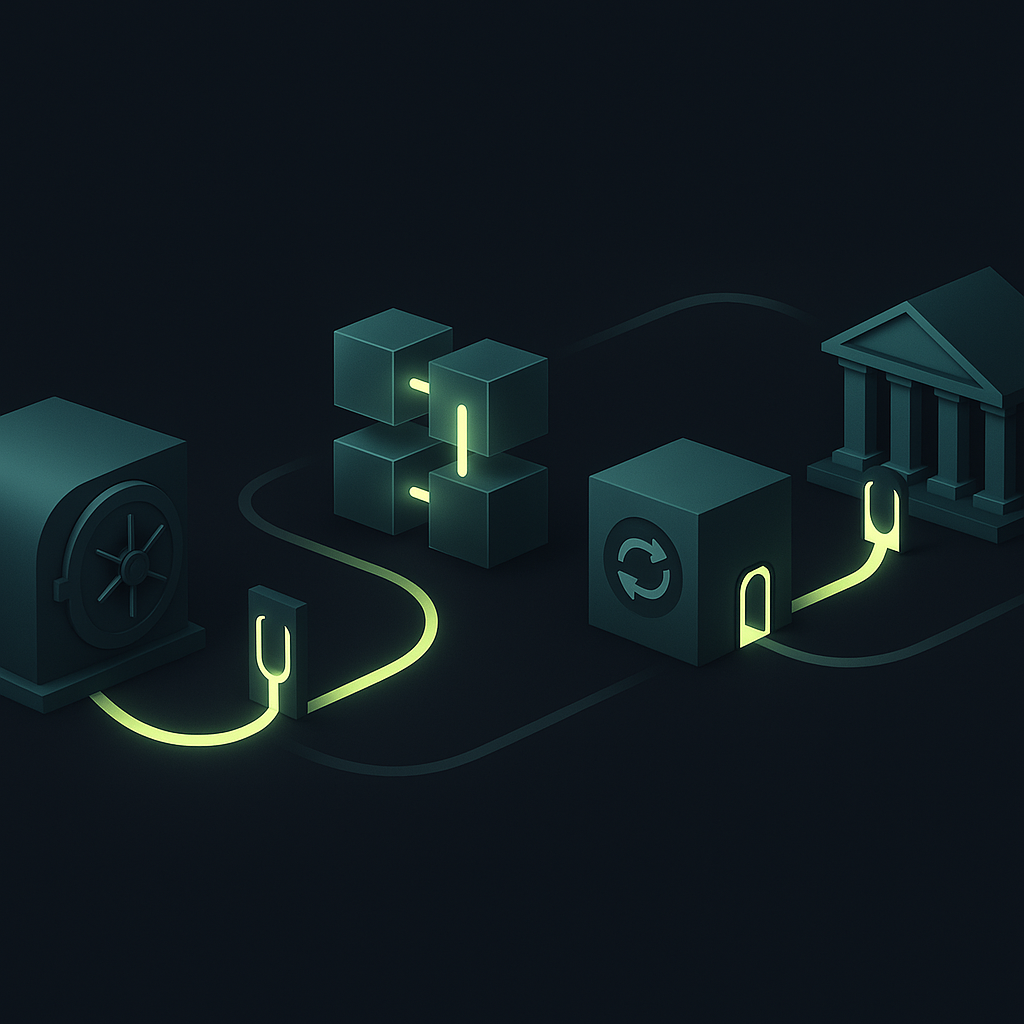
Cross border payments using blockchain move value between wallets or participating institutions on a shared ledger, often using stablecoins as the settlement asset. A business can fund a payment in fiat currency, have a provider transfer stablecoins internationally, and deliver local currency to the recipient’s bank account. The recipient does not necessarily need a crypto wallet.
The potential benefits are extended settlement availability, fewer correspondent-bank handoffs, and more direct visibility into the blockchain transfer. But an on-chain confirmation is not proof that a vendor has received usable bank funds. For finance teams paying hundreds of recipients, the practical question is whether every handoff—from funding through conversion to final delivery—is controlled and observable.
How a blockchain cross-border payment works
A common business model uses blockchain as an intermediate settlement rail rather than asking either business to hold digital assets. BVNK’s explanation of blockchain cross-border payments describes this fiat-to-digital-asset-to-fiat approach.
- Fund: The payer sends fiat currency to a payment provider or uses an existing balance.
- Convert: The provider acquires the agreed settlement asset, such as a dollar-denominated stablecoin.
- Transfer: The asset moves to a receiving provider or recipient wallet over the selected blockchain.
- Off-ramp: The receiving provider converts the asset into the required payout currency.
- Deliver: A domestic payment rail credits the recipient’s bank account.
Some arrangements use prefunded inventory rather than converting funds separately for every payment. That changes where liquidity is held and who bears the exposure; it does not eliminate funding requirements.
Direct wallet payouts end at the wallet instead. Tokenized bank deposits offer another model, with access and transferability determined by participating institutions. These instruments are not interchangeable: a stablecoin holder’s redemption rights differ from a depositor’s claim on a bank.
Blockchain and banking infrastructure can work together
This is not necessarily a choice between blockchain and existing banking networks. In its September 2025 shared-ledger announcement, Swift described plans to add a blockchain-based ledger to its infrastructure. That announcement signals a hybrid direction, not proof that every bank or corridor already supports blockchain settlement.
For an operator, the relevant architecture is the one available for the specific payment: supported funding currency, settlement asset, network, receiving partner, and domestic delivery method.
Separate blockchain finality from payment completion
A useful payment model distinguishes three milestones:
- Network confirmation: The transfer meets the provider’s confirmation or finality policy for that blockchain.
- Recipient availability: Funds are available in the agreed wallet or bank account.
- Obligation discharged: Delivery satisfies the applicable contract and legal requirements for paying the recipient.
These milestones may occur at different times. An irreversible transfer to an off-ramp provider does not establish that a supplier’s invoice has been paid. Nor does a stablecoin designed to track a dollar guarantee immediate redemption at par under every condition.
Require the provider to define what each status means. Labels such as “complete” should identify whether they refer to the blockchain transfer, conversion, or beneficiary credit.
Build an evidence chain across the handoffs
The following control map is an operating template, not a universal provider specification.
| Handoff | Evidence to retain | Completion gate |
|---|---|---|
| Payer to funding provider | Funding reference and credited balance | Spendable funds confirmed |
| Fiat to settlement asset | Quote, asset, network, execution record | Conversion terms satisfied |
| Sending to receiving wallet | Transaction hash, addresses, confirmation status | Network policy satisfied |
| Receiving provider to local currency | Conversion record and payout instruction | Local funds available |
| Domestic rail to beneficiary | Bank reference and credit or return status | Agreed delivery confirmed |
Use one business payment identifier to connect these records. A blockchain explorer can show a token transfer; it cannot, by itself, identify the invoice allocation, agreed FX rate, or subsequent bank return.
Evaluate the full cost and liquidity requirement
Low network fees do not establish a low-cost payout. Compare quotes for the same net recipient amount, destination currency, and delivery requirement.
The cost stack can include funding charges, stablecoin acquisition spreads, network fees, provider charges, off-ramp conversion, domestic delivery, and recipient deductions. Avoid double-counting bundled charges. Also assess the cost of prefunding and the operational effort required to resolve exceptions.
A dollar-denominated stablecoin does not remove FX exposure when the obligation is denominated in another currency. Establish when the local-currency rate becomes binding, when the quote expires, and who funds a shortfall if execution is delayed.
For a rail-level comparison, use the stablecoin versus SWIFT cost and speed breakdown. For implementation, go further: ask whether off-ramp liquidity is available at your payment sizes and outside local banking hours. Blockchain availability cannot make a closed domestic rail process payments.
Control the risks that the ledger does not solve
The BIS review of cross-border payment technologies provides a broader framework for assessing payment innovations. For deployment, translate technical possibilities into explicit responsibilities rather than treating the settlement technology as a substitute for compliance or risk management.
Custody and asset exposure
Determine who owns and controls the asset at each stage. Ask about custody arrangements, segregation, issuer redemption eligibility, account freezes, and the treatment of balances if a provider fails. A managed service can reduce your direct key-management burden without removing counterparty exposure.
Specify the exact token and network. Native and bridged versions of an asset can introduce different dependencies. For direct wallet payouts, validate the destination through an authenticated process and restrict changes to approved recipients.
Compliance and country-specific data
Blockchain does not waive sanctions screening, customer verification, tax obligations, or local foreign-exchange rules. Requirements depend on jurisdiction, provider, asset, and payment purpose. A provider’s authorization in one market does not establish permission for every destination.
Obtain a corridor-specific field specification before onboarding recipients. Depending on the destination and rail, it may require legal names, account identifiers, bank or branch codes, addresses, tax identifiers, payment-purpose codes, and supporting documents. For wallet delivery, add the network and address, plus any required beneficiary and originator information.
Keep sensitive business records off public ledgers unless a reviewed design specifically requires otherwise. A transaction hash can link internal records without publishing invoices or personal information.
Release authority and reconciliation
Apply approval controls before an irreversible transfer. Separate beneficiary changes, payment approval, and execution authority. Configurable approval policies can support this governance layer; the release process still needs to enforce the approved destination, amount, asset, and network.
Reconcile the business obligation to conversions, transfers, fees, and delivery evidence. Shared-ledger settlement can simplify one part of reconciliation, but it does not reconcile the entire money cycle automatically.
Design recovery before the first live batch
Hypothetical example: A company pays an overseas supplier in local currency through a stablecoin settlement provider. The blockchain transfer confirms, but the destination bank rejects the beneficiary account details.
The supplier remains unpaid. Automatically sending a replacement could create duplicate exposure if the original provider later retries delivery. The correct response is to identify where the value is held, block uncontrolled retries, correct the beneficiary details through an authenticated workflow, and determine whether the provider will redeliver or return funds.
Require each exception to have an owner, a recoverable balance location, a next action, and evidence that closes the case. Use the failed-payment recovery guide to structure the surrounding operations.
A launch checklist for finance and payment operations
- Define the endpoint: Wallet receipt or usable local bank funds?
- Validate the corridor: Confirm legal availability, recipient data, limits, and domestic delivery support.
- Document exposure: Identify custody, issuer, conversion, and provider risks at each stage.
- Agree economics: Capture net delivery, fees, quote validity, and liquidity requirements.
- Test evidence: Trace an approved obligation through funding, transfer, conversion, and recipient credit.
- Test exceptions: Include rejected bank details, screening holds, unavailable liquidity, and ambiguous statuses.
- Control fallback: Release a replacement only after the original payment’s disposition is established.
- Measure outcomes: Track recipient availability, net delivered value, manual interventions, and unresolved balances—not only chain confirmation speed.
Choose blockchain for an operational improvement
Blockchain is useful when it improves a real settlement constraint without creating disproportionate liquidity, compliance, or recovery burdens. It may add little where existing domestic connections already deliver predictable, low-cost payouts.
Start with a defined corridor and prove the entire payment lifecycle. Payouts.com brings global payouts, treasury, and financial automation into one financial operating system. Explore Payouts Automation with your funding, delivery, approval, and exception requirements documented, then confirm which supported configuration fits the job.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
31 commentsRelated resources
Stablecoin vs. SWIFT: A Cost and Speed Breakdown for Cross-Border B2B Supplier Payments
SWIFT wires and stablecoin rails both move money across borders — but they price, settle, and reconcile very differently. Here's an operator-grade comparison for B2B supplier payments.
Multi Currency Payouts: A Failed-Payment Recovery Guide
A returned cross-border payment is not simply the original transaction in reverse. Learn how to preserve the recipient’s currency entitlement, manage FX differences, and retry payments without creating duplicates.
Payment Operations Manager: Role, Authority, and Global Payout KPIs
A payment operations manager owns the execution and control of payments, not just the processing queue. For global payouts, success depends on clear authority over releases, exceptions, provider performance, and operational change.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The framework for evaluating the full cost and liquidity requirement is helpful, but we're also finding that providers are inconsistent about whether their quoted FX spread applies to the on-ramp conversion, the off-ramp conversion, or both. When you ask for a breakdown they'll show you the network fee separately but still bundle the acquisition and redemption spreads into a single 'conversion rate' which makes it impossible to compare apples to apples across providers.
The section on separating blockchain finality from payment completion is critical and honestly something most provider demos gloss over. We've seen cases where the on-chain transfer succeeded but the off-ramp partner had a compliance hold that delayed final delivery by three days, yet the dashboard showed 'complete' the whole time. The article's point about requiring providers to define what each status label actually means should be a non-negotiable in any RFP.
We had the exact same thing happen. The dashboard showed 'complete' but our vendor never received funds due to a KYC flag on the off-ramp side. Now we only mark our AP obligation as paid when we have the domestic bank reference, not the on-chain confirmation.
We had the exact same thing happen. The dashboard showed 'complete' but our vendor never received funds for 48 hours due to a manual compliance review on the receiving side. Now we don't consider a payment done until we get explicit confirmation that the beneficiary account was credited, regardless of what the blockchain shows.
The custody section gets cut off but that's exactly where we need the most detail. Who holds title to the stablecoin during the 90 seconds between on-ramp conversion and off-ramp delivery, what happens if the off-ramp provider goes under while holding converted local currency, and how do we even audit segregation when the provider is using omnibus wallets? These aren't edge cases when you're moving mid-six figures per week.
We required a written legal opinion on exactly this before signing. Turns out the stablecoin issuer's terms excluded our provider from direct redemption rights, so there was a two-party chain of credit exposure during settlement that wasn't disclosed in the sales process. The custody arrangement during those 90 seconds mattered a lot more once we mapped out insolvency scenarios.
Agreed, that's the gap in most provider documentation. We asked this exact question during diligence and got directed to general terms that said title transfers 'upon conversion' but didn't specify which entity held liability during the off-ramp window or what recourse we'd have if their local partner became insolvent with our funds in their nostro account.
The custody question is what killed our last blockchain pilot. We got comfortable with the settlement speed and the cost was acceptable, but legal couldn't sign off because none of the providers could give us a clean answer on who had redemption rights if their off-ramp partner went under mid-transaction. The article's point about distinguishing stablecoin redemption rights from depositor claims is exactly where we got stuck.
We hit the same thing. The article's point about distinguishing stablecoin redemption rights from depositor claims is exactly where our discussions with legal stalled. The provider documentation treated custody as a technical detail rather than a legal one.
We walked away from a similar situation last year. The provider could explain the blockchain custody fine, but once we asked about the window between off-ramp conversion and actual bank credit, nobody wanted to put in writing what happened to those funds if the local partner had a license issue or froze operations.
The point about blockchain availability not mattering when the domestic rail is closed is the reality check most vendors skip in their demos. We had a provider pitch us on 24/7 settlement to Brazil, but the local PIX rail still batched overnight and their off-ramp partner didn't staff weekends, so the 'instant' settlement sat in limbo until Monday morning.
We ran into the same wall with a Southeast Asia corridor. The provider kept emphasizing irreversible settlement in under a minute, but their local partner bank only processed outbound transfers twice daily. The blockchain part worked exactly as advertised, but our suppliers still waited 8-12 hours for actual credit.
This is why the handoff control map in the article is so useful. You need to verify off-ramp partner availability and domestic rail operating hours separately from the blockchain piece, otherwise the entire value proposition falls apart during the hours you actually need coverage.
The three-milestone model (network confirmation, recipient availability, obligation discharged) should be the default for any AP system integrating with these providers. We built our reconciliation workflow assuming blockchain finality meant payment complete and spent two months retrofitting status webhooks to distinguish between on-chain settlement and actual bank credit.
We made the same mistake. The evidence chain section in the article is exactly what we needed from day one—keeping the business payment identifier consistent across all handoffs would have saved us from manually linking explorer data to invoices in spreadsheets.
We had the exact same issue. Our provider's API returned 'confirmed' once the stablecoin hit the off-ramp wallet, but we had no visibility into local bank settlement for another 48 hours in some corridors. Had to add a manual reconciliation step that defeated the whole automation point.
The article correctly identifies that low network fees are misleading, but I'd add that the reconciliation burden is often the hidden cost nobody prices in. We spent more on engineering time building tracking across the conversion and off-ramp steps than we saved on the first six months of payments.
This is exactly right. The article mentions building an evidence chain across handoffs but doesn't emphasize enough that tracking a payment ID from your AP system through three or four provider touchpoints requires actual integration work. The provider gives you a blockchain explorer link and acts like that's transparency.
We hit the same wall. The evidence chain section calls out using one business payment identifier to connect all the records, but actually getting that reference to propagate through every provider handoff took us three months of integration work. The blockchain part was the easy part.
The evidence chain template is helpful, but I'm curious how teams are actually reconciling the blockchain record with their ERP when the payment identifier doesn't flow through every provider hand-off. We've had cases where the off-ramp partner generates their own reference for the domestic leg and our AP system can't auto-match without manual intervention.
We solved this by requiring the provider to echo our payment ID in every webhook and status callback, including the final domestic credit notification. It's in the contract now. If their off-ramp partner can't preserve it, they need to maintain a mapping table and expose it through their API so we can pull the full chain on demand for reconciliation.
We had the same break in reference flow. Our workaround was to require the provider to include our original payment ID in the beneficiary reference field on the domestic leg, even though it meant truncating it in some corridors. Not perfect, but it let our reconciliation bot match 80% automatically instead of manual lookup every time.
The distinction between network confirmation and obligation discharged is something we learned the hard way. We had three payments show "complete" in our dashboard but the vendors never received bank credits due to an off-ramp provider liquidity issue. Now we don't mark an invoice paid until we have the domestic rail confirmation, regardless of what the blockchain says.
Same experience here. We now require the provider to give us separate status codes for blockchain finality versus actual beneficiary credit, and we built a reconciliation process that pulls bank confirmation files before we close the AP record. The extra step adds a day to our close cycle but it's worth it.
We implemented a similar control after a partial failure scenario. Our payment operations team now waits for the domestic bank reference before closing the AP line item, and we built a reconciliation report that flags any transaction sitting in 'blockchain confirmed' status for more than four hours without a corresponding beneficiary credit.
Appreciate the cost stack breakdown. We evaluated two blockchain payout providers last quarter and the quoted savings completely evaporated once we accounted for prefunding requirements and the spreads on both ends of the conversion. The stablecoin acquisition cost alone was higher than our existing correspondent banking fees for EUR and GBP corridors.
Same. The real killer for us was the liquidity lock-up. One provider wanted us to maintain a minimum balance equal to 3 weeks of average volume just to access their best conversion rates, which completely changed the working capital math.
Exactly this. The network fee is a rounding error compared to the bid-ask on acquiring the stablecoin and then the off-ramp spread on the other end. We found the all-in cost was competitive with traditional rails only on specific high-volume corridors where the provider had deep liquidity partnerships.
How are teams handling the accounting treatment when you have a dollar-denominated stablecoin sitting with the provider for 18-36 hours before final delivery in local currency? Are you booking the FX gain/loss at the point of stablecoin conversion or when the beneficiary is credited?
We book the exposure at the point our fiat leaves our account and recognize the gain/loss when local currency is actually credited to the beneficiary. The stablecoin phase is just a settlement mechanism for us, not an asset we're intentionally holding. Our auditors were comfortable treating it as in-transit, similar to how we'd treat funds moving through correspondent banks.
We recognize the FX exposure the moment we commit to the local currency amount with the provider, which is usually before they acquire the stablecoin. The intermediate stablecoin position is their risk, not ours, since we locked a delivery quote. If you're not getting a binding rate upfront, you're taking currency risk during the settlement window.