

Does Revolut Support SEPA Instant? Limits and Payout Checks
Revolut supports SEPA Instant, but support does not guarantee that every euro payment will arrive instantly. Here is how finance teams should verify availability, interpret limits, and handle uncertain transfers.
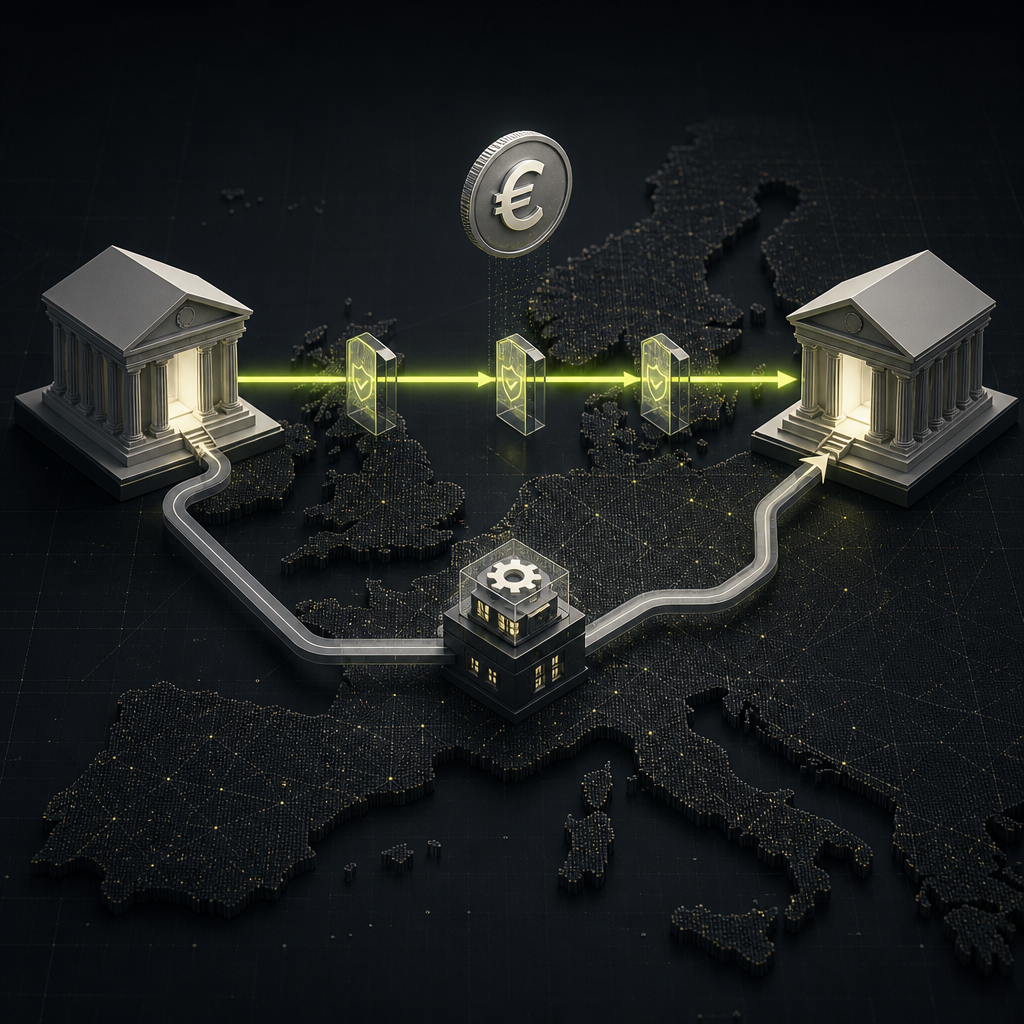
Yes—Revolut supports SEPA Instant Credit Transfer (SCT Inst) for eligible euro bank transfers. However, availability depends on the account, payment route, receiving bank, and applicable limits. Revolut’s instant money transfer page explicitly describes SEPA Instant as available “if available” and makes fast delivery conditional on the recipient bank supporting it.
For finance teams paying vendors or contractors, the useful distinction is between Revolut supporting the rail and a particular payment being eligible for that rail. Do not promise instant receipt solely because the sender or recipient uses Revolut.
What SEPA Instant support actually means
SEPA Instant is a euro bank-transfer rail. SEPA covers participating countries beyond the euro area, so a recipient’s country alone does not establish whether a transfer is eligible. The payment currency, account eligibility, and reachability of the receiving bank matter.
It is also different from a Revolut-to-Revolut transfer. A fast payment between Revolut users does not demonstrate that an external supplier’s bank account is reachable through SCT Inst.
Evaluate outgoing and incoming payments separately:
- Sending from Revolut: confirm that the specific recipient, amount, and account setup are eligible for an instant euro transfer.
- Receiving into Revolut: the sending provider must support the route, and the receiving Revolut account’s limits still apply.
- Funding from another currency: any required conversion is a separate step. An instant euro transfer does not make the preceding FX transaction costless or eliminate funding delays.
Even when the bank-transfer leg is fast, invoice approval, balance availability, compliance checks, and payment release remain separate operational stages.
Revolut’s limits: distinguish personal settings from business receipts
The documentation supplied for this article includes different account types and localized help pages. These should not be combined into one universal Revolut limit.
Personal accounts: configurable instant-transfer limits
Revolut’s Slovenia-localized personal help page on SEPA Instant limits says users can set a maximum per transaction or per day, with no default limit under that setting. Both types of limit cannot be active simultaneously.
That describes a customer-configurable control. It is not evidence that every Revolut product supports unlimited instant transfers, nor should a finance team apply personal-account guidance to a business payment workflow.
Business accounts: a published incoming-transfer cap
Revolut’s US-localized Business help page on receiving limits states that incoming SEPA Instant transfers are capped at €100,000 per transfer. It says an incoming payment above that threshold is processed as a normal SEPA Credit Transfer instead.
Treat this as a published Revolut Business receiving condition, not a universal SEPA scheme limit or a confirmed outgoing-transfer ceiling. The evidence reviewed on October 28, 2026 does not establish one global outgoing Business limit. Confirm the current conditions for the receiving account’s jurisdiction before arranging a time-critical receipt.
Do not split a payment merely to bypass a control. If a large invoice cannot use the intended route, agree an authorized payment method and delivery expectation with the recipient.
Why a Revolut euro transfer may not be instant
The Sweden-localized Revolut transfer page cited above includes an important caveat: euro transfers from Sweden to a bank account in the SEPA region will usually use standard SEPA, generally arriving within two working days.
That is a localized statement, not proof that every Swedish recipient—or every non-euro-area country—has the same restriction. It does show why global product messaging should not replace account-specific checks.
Use the following diagnostic table before treating a slower payment as a failure.
| Check | Possible issue | Operator action |
|---|---|---|
| Payment currency | Transfer is not in EUR | Identify the actual rail and ETA |
| Recipient eligibility | Instant route unavailable | Check the transfer’s delivery estimate |
| Account jurisdiction | Local product conditions differ | Use account-specific guidance |
| Amount and limits | Applicable threshold exceeded | Confirm rejection or fallback behavior |
| Available funds | Funding or FX remains incomplete | Resolve funding before release |
| Payment status | Review or processing unresolved | Investigate before resending |
Standard SEPA is not the same as a failed payment. It may be the route available for that transfer. Equally, do not assume every failed instant attempt automatically falls back to standard SEPA: the documented incoming Business rule above does not establish universal fallback behavior.
What to check about fees
SEPA Instant support alone does not establish the total cost of a business payout. Check the applicable Revolut plan, account jurisdiction, transfer quote, and any currency-conversion charges before approval.
Separate the cost of sending euros from the cost of obtaining them. A company holding funds in another currency can incur FX costs even if the euro bank-transfer leg carries no additional charge. For recurring vendor runs, compare the amount debited with the euro amount instructed, rather than judging cost from the transfer-fee line alone.
A pre-release checklist for finance teams
For a large recipient file, eligibility should be checked at payment level. One successful transfer is not evidence that every beneficiary in the next run will receive funds instantly.
- Validate the beneficiary. Collect the account-holder name and IBAN, plus any additional details requested by the payment interface. Independently verify changes to supplier bank details.
- Confirm the currency and funding. Establish whether the invoice will be paid in euros and whether spendable EUR funds are available.
- Check the relevant account conditions. Distinguish personal from Business documentation, sending from receiving limits, and local from global guidance.
- Inspect the transfer-specific estimate. Review the available method, expected arrival, and fees before authorizing payment. Do not infer the rail from speed alone.
- Define acceptable fallback. Decide whether standard SEPA still meets the supplier’s due date. Escalate if it does not.
- Save the payment evidence. Retain the payment identifier, beneficiary details, amount, currency, release time, and provider status alongside the invoice.
- Reconcile before retrying. Establish the original payment’s outcome before initiating a replacement.
This is a narrower application of a payment corridor routing policy: select the route using the actual account, currency, deadline, and available evidence—not the provider’s brand alone.
If a transfer is pending, do not immediately send it again
A pending status creates uncertainty; it does not establish that the money has failed to arrive. Sending a replacement through another rail can create a duplicate payment if the original later completes.
First, inspect the payment record and any requests for information. Confirm the beneficiary details and delivery estimate. If the outcome remains unclear, contact support with the transaction identifier and ask whether the payment is still processing, completed, rejected, or returned.
Keep the invoice linked to the unresolved payment while investigating. A recovery workflow should distinguish confirmed failures from unknown outcomes, as explained in this guide to failed-payment recovery.
The practical answer for business payouts
Revolut supports SEPA Instant, but the defensible commitment is conditional: eligible euro payments can use the instant rail when the relevant accounts, receiving bank, and limits permit it.
Before the next payment run, document which transfers qualify, what happens when they do not, and who owns unresolved statuses. If your operation spans multiple providers and rails, explore Payouts.com’s payout automation as part of a broader money-movement workflow. Evaluate specific corridors and reconciliation needs rather than treating instant support as a complete payout operating model.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
Multi Currency Payouts: A Failed-Payment Recovery Guide
A returned cross-border payment is not simply the original transaction in reverse. Learn how to preserve the recipient’s currency entitlement, manage FX differences, and retry payments without creating duplicates.
ClickFunnels Affiliate Payout: Release Rules and Global Payment Checks
ClickFunnels commissions become payable only after eligibility, threshold, and onboarding requirements are met. Here is how to separate earned commissions from money ready to reach your bank.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.