

Friendi Pay International Transfer: Fees and Sending Checks
FRiENDi Pay offers app-based international remittances, but its Saudi and Oman services have different rules. Here is how to check the quote, recipient details, delivery expectations, and suitability for business payments.
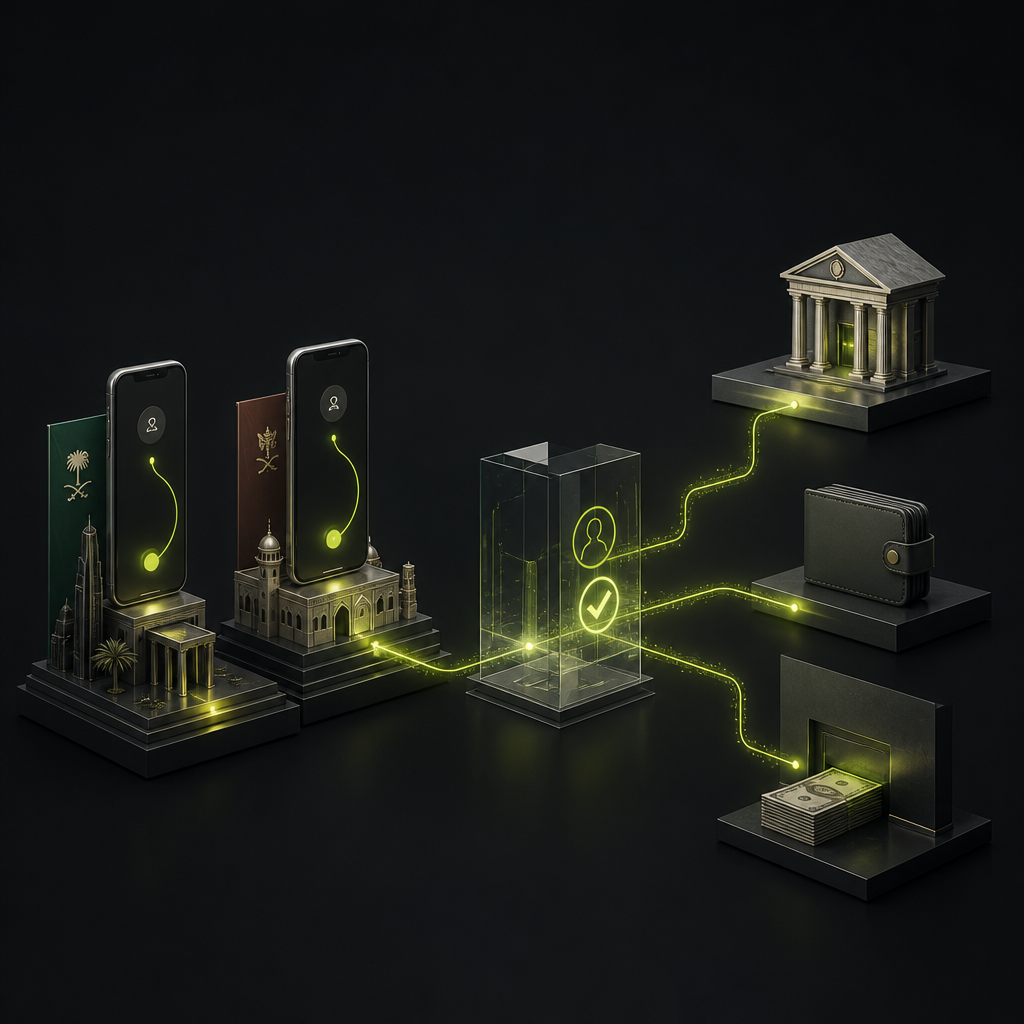
A Friendi Pay international transfer lets an eligible customer send money abroad through the FRiENDi Pay app. In practice, you complete identity verification, add an international beneficiary, select an available delivery method, review the exchange rate and fees, and confirm. The Saudi Arabia and Oman services are separate offerings: do not assume that eligibility, charges, limits, or destination coverage carry over between them.
For finance teams, the important distinction is between an individual remittance service and a business payout workflow. The supplied official materials describe individual onboarding; they do not establish corporate account eligibility, bulk-payment functionality, or approval controls. Confirm permitted business use before considering the service for vendor or contractor payments.
Start with the correct sending country
Saudi Arabia: a bank-backed remittance service
The Saudi Investment Bank’s FRiENDi Pay product page describes an international money transfer service from Saudi Arabia, powered by the bank and built around Saudi Central Bank agent-banking regulations. Customers do not need to be existing SAIB account holders.
Saudi onboarding is identity-linked. The described process uses a National/Iqama ID and date of birth, with government digital-identity authentication involving Absher and Nafath. Follow the current app prompts rather than assuming a document upload alone completes verification.
Oman: a separate wallet service
The Oman offering is a separate mobile wallet with local and international transfer functions. Its official help page describes eligibility for individuals aged 18 or older with a valid national or residence ID and an active Oman-based mobile number. Onboarding includes questions such as occupation and income range.
The Oman help material distinguishes free FRiENDi Pay-to-FRiENDi Pay wallet transfers from transfers to other wallets, which carry fees shown before confirmation. Neither statement should be read as a promise of free international remittances.
How to make a Friendi Pay international transfer
Use this sequence as a preparation guide; labels and available options can change by app version and jurisdiction.
- Confirm eligibility and complete KYC. Register in the correct country app and finish the required identity checks. In Saudi Arabia, expired KYC restricts account access until it is renewed.
- Check funding options before loading money. Verify which funding methods your account accepts and whether you can recover unused funds. Do not assume that wallet funding is reversible through the same route.
- Add the beneficiary. Open beneficiary management or the send-money flow, select an international beneficiary, and choose the destination and available receiving method.
- Enter recipient details. Provide the recipient’s name and the bank details or wallet identifier requested. Supply purpose-of-transfer information accurately when required.
- Review the complete quote. Check the amount debited, sending currency, transfer fee, exchange rate, receiving currency, recipient amount, and delivery estimate.
- Confirm and retain the reference. Save the receipt and transaction identifier. Track the existing transfer rather than submitting another simply because the recipient has not yet received funds.
The Saudi FRiENDi Pay help page describes the international-transfer and beneficiary workflows, confirms that international remittance fees appear before confirmation, and explains restrictions when KYC expires.
Fees and exchange rates: compare the recipient’s net amount
There is no verified universal international-transfer tariff in the supplied official material. The Saudi FAQ says account funding is free, but international remittances carry fees displayed in the transaction flow. Free funding is not the same as a free transfer.
Do not build a recurring payment budget around a first-transfer offer or an old “zero fee” claim. Check any promotion’s current eligibility and conditions, then obtain a normal, non-promotional quote for repeat payments.
The exchange rate also matters. A low explicit fee can be offset by a less favorable conversion rate. The supplied sources do not establish a fixed FX markup, so assigning FRiENDi Pay a spread percentage would be misleading.
For a practical comparison, request quotes close together for the same sending country, destination, receiving method, and total sender debit. Then compare the recipient amounts. If your obligation is a fixed amount in the recipient’s currency, instead compare how much each provider requires you to pay to deliver that amount.
This approach separates advertised fees from the actual payment outcome. Our guide to reducing cross-border payment fees explains how finance teams can apply that distinction across recurring payouts.
Delivery methods, beneficiary data, and timing
FRiENDi Pay materials describe bank transfers, cash pickup, and digital-wallet delivery across its remittance offering. That does not establish that every method is available for every country or in both sending-country apps. Check the live destination and method selection before collecting recipient information.
Use the following as a verification checklist, not as a universal FRiENDi Pay field specification.
| Transfer element | What to verify | Why it matters |
|---|---|---|
| Bank deposit | Name, account identifier, requested routing fields | Incorrect details can cause rejection or delay |
| Wallet delivery | Supported wallet and registered recipient identifier | A phone number alone may be insufficient |
| Cash pickup | Pickup partner, name match, collection requirements | Recipient must be able to collect |
| Currency | Quoted payout currency and receiving-account compatibility | Additional conversion may affect net proceeds |
| Timing | Destination-specific estimate and status meaning | Submission is not proof of receipt |
| Limits | Current account and transaction allowances | A valid beneficiary does not ensure acceptance |
For bank transfers, required routing data varies by destination. Do not force every beneficiary into an IBAN-only template or assume an account number is always sufficient. The app’s country-specific prompts should govern the submission; our international contractor bank-payment guide provides broader context for country-level data collection.
There is no single verified delivery time for every FRiENDi Pay transfer. The Saudi help material says completion varies by destination and receiving bank. Treat the displayed estimate as transaction-specific, not as a guarantee that another corridor will perform identically.
Limits and delayed transfers: what not to assume
The supplied official sources do not confirm a universal current monthly international-transfer limit. Do not use an unofficial published figure as payment-run capacity. Check your verified account’s available allowance and ask whether any transaction, cumulative, or destination-specific restrictions apply.
If a transfer stalls, collect the transaction reference, submission time, amount, currency, receiving method, and displayed status before contacting the relevant country support team. Ask whether the transfer is awaiting review, rejected, returned, or awaiting recipient action.
Avoid resending until the original transfer’s disposition is clear. A pending transfer and a replacement can both complete. If funds are being returned, ask separately about the refund amount, fee treatment, exchange-rate treatment, and expected return route; the supplied evidence does not establish a universal refund policy.
Can a finance team use it for recurring business payouts?
Individual remittance access does not prove permission to pay business obligations. Before using FRiENDi Pay for company funds, obtain confirmation of corporate eligibility, permitted payment purposes, funding-account requirements, and any restrictions on third-party payments. Do not route company payments through an employee’s personal account as a workaround.
For a high-volume recipient base, ask for evidence of:
- Authority controls: separate preparation and release permissions, with an auditable approval record.
- Operational capacity: approved volume limits and supported batch or integration options.
- Reconciliation: transaction exports connecting each payment to the recipient and underlying obligation.
- Exception handling: usable rejection reasons, return tracking, and duplicate-prevention controls.
These are evaluation requirements, not confirmed FRiENDi Pay features. A remittance app may suit an eligible individual’s transfer without meeting a company’s payment-control requirements.
Before you send: the final decision
Choose the correct country service, complete KYC, verify the recipient’s delivery route, and review a live quote showing both total debit and recipient proceeds. Confirm the applicable limit and save the transfer reference. Those checks are more reliable than a generic fee claim or headline delivery promise.
If the objective is recurring vendor, contractor, or seller payments, establish business-use permission first. Then evaluate a dedicated workflow such as Payouts.com’s payout automation against your actual corridors, approval requirements, and reconciliation needs—not just the ability to send one successful transfer.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
How to Pay International Contractors: A Country-by-Country Bank Payment Guide
A successful contractor payment delivers the agreed amount—not just a completed transfer instruction. Build a country-specific payment plan around bank details, currency, fees, and the date funds become available.
How to Reduce Cross Border Payment Fees: A Finance Playbook
Lower transfer fees do not always mean cheaper payouts. Learn how to negotiate, operationalize, and verify savings across your international payment program.
Mobily Pay International Transfer Limit: What You Can Send
Mobily Pay’s published wallet limits are not a guaranteed international remittance allowance. Here is how to distinguish funding, spending, and transfer caps before committing to a payment.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.