

Google Pay International Transfer: What Works for Business?
Google Pay is not a universal cross-border payout service. Learn which payment functions are distinct, where older transfer instructions fail, and how to handle overseas recipients who ask for GPay.
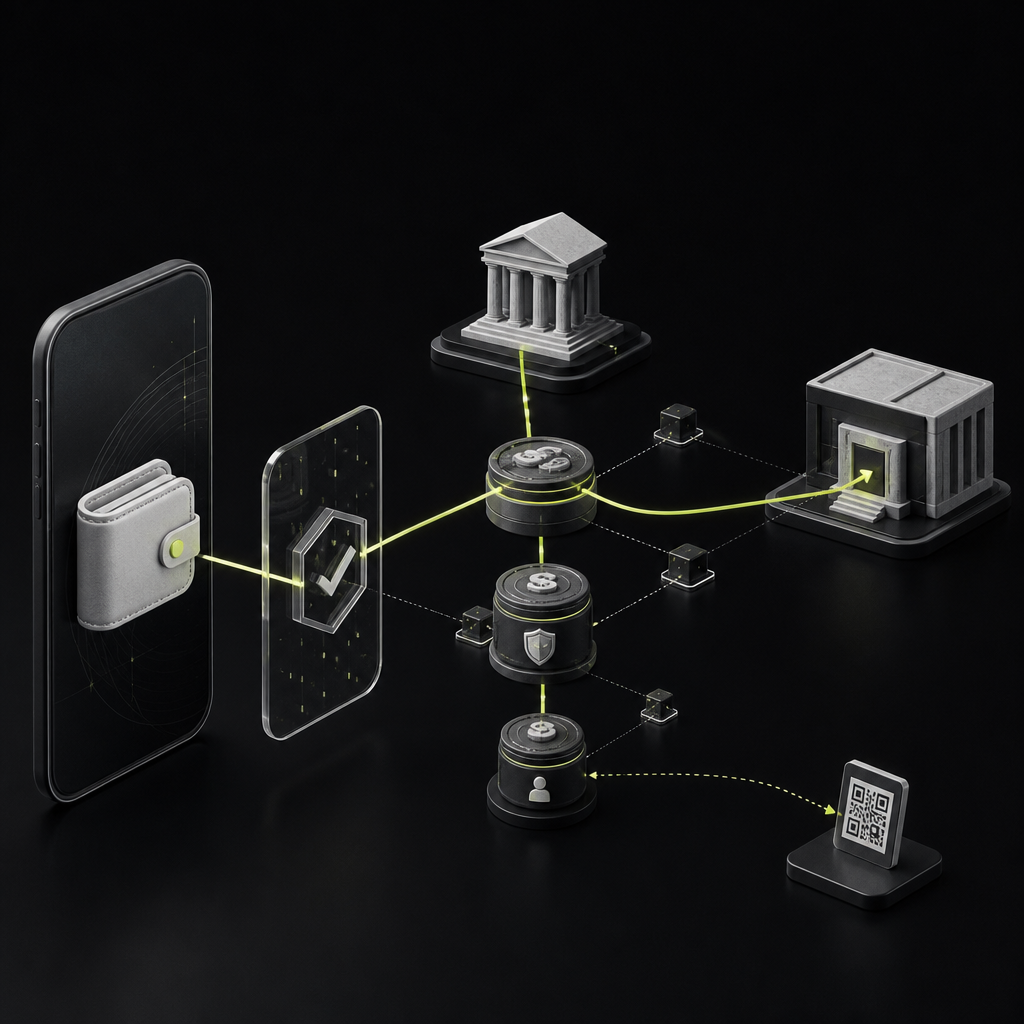
Google Pay does not provide a universal international money-transfer service. The standalone US Google Pay app was discontinued on June 4, 2024, so older instructions for sending remittances through that app are no longer a usable guide. In India, Google Pay does not offer general outbound overseas transfers; paying participating overseas merchants through UPI International is a separate function.
For finance teams, the practical answer is clear: a contractor saying “pay me through Google Pay” has not supplied complete international payment instructions. You still need an eligible transfer provider, an approved payment purpose, and a supported receiving account or payment identifier.
What changed for Google Pay international transfers?
The US app discontinuation announcement set June 4, 2024 as the shutdown date and explained that sending, requesting, and receiving money through the US app would end. This did not mean that the Google Pay checkout brand or Google Wallet contactless payments disappeared.
Older guides describe US users initiating partner-powered transfers to India and Singapore through Google Pay. Those instructions belong to the former US app experience. They should not be treated as evidence that the same sending route remains available today.
Google Wallet is not a replacement remittance account. Holding a payment card in a digital wallet, paying an overseas merchant, and transferring money to an overseas beneficiary are different activities.
Separate the payment functions before choosing a route
The phrase “Google Pay international transfer” can refer to several different services. Identify the actual task before checking fees or collecting recipient details.
| Payment function | What it means | Business implication |
|---|---|---|
| Former US app remittance flow | Partner-powered international sending | Do not use legacy app instructions |
| Google Pay or Wallet card payment | Payment to a merchant using a stored card | Not a general beneficiary transfer |
| India outbound remittance | Sending funds from India overseas | Requires a separate eligible route |
| UPI International | Payment to participating overseas merchants | Not general contractor remittance |
| Foreign inward remittance feature | Receiving through a supported arrangement | Verify current sender and purpose eligibility |
Sending money abroad from India
As explained in Wise’s India-focused Google Pay guide, Indian users cannot use Google Pay for general overseas money transfers. For a foreign supplier invoice or contractor payment, evaluate a bank or provider that supports the relevant Indian outbound business-payment route.
Do not confuse this restriction with international shopping. A merchant payment capability does not establish permission to send funds to an individual or business beneficiary abroad.
Paying overseas merchants through UPI
Google’s UPI International documentation describes payments to merchants abroad using supported QR arrangements. Availability depends on the participating market, merchant, and banking setup.
This is not a way to bypass cross-border remittance requirements. It also does not mean foreign exchange costs disappear: a purchase denominated in another currency still requires conversion, with applicable charges determined by the arrangement.
Receiving foreign remittances in India
Google documents an activation process for Foreign Inward Remittances. However, a receiving-side help page is not proof that a particular sender can initiate a transfer today. It must be read alongside current sending-provider availability, especially given the US app shutdown.
Before relying on this feature, confirm the supported origin country, provider, beneficiary account, and payment purpose. Do not assume that activation makes a recipient eligible for overseas commercial payments, or that every international sender can reach their UPI identifier.
Who actually moves the money?
Where a remittance provider offers Google Pay as a funding option, the wallet interface and the transfer service perform different jobs. The interface may authorize a supported card payment; the remittance provider controls the transfer quote, verification, supported destinations, and delivery process.
A useful operational model is:
- Funding: The sender authorizes payment using an accepted funding method.
- Transfer processing: The provider checks eligibility, performs required screening, and handles conversion where needed.
- Recipient delivery: The provider pays through its supported bank, wallet, or other receiving route.
A successful funding authorization does not prove that the beneficiary has received usable funds. If a transfer stalls, finance needs the remittance provider’s transaction reference and delivery status—not just a wallet payment confirmation.
Likewise, a Google Pay checkout button does not prove support for corporate senders, supplier invoices, bulk payouts, or a particular destination. Verify those capabilities with the provider operating the transfer.
Fees, limits, and timing: use the live transfer terms
There is no single Google Pay international transfer fee, limit, or delivery time that applies across these different services. Historical US app limits and generic card-fee figures should not become operating assumptions for a current business payment.
Compare the amount received, not just the advertised fee
For the same destination-currency amount, compare the total sender debit across eligible providers. Include the transfer fee, exchange rate, funding charges, and any disclosed delivery deductions. Check whether the recipient amount is guaranteed or estimated.
A low visible fee can be offset by a less favorable exchange rate. Conversely, a separately disclosed fee may accompany a better conversion rate. Finance should save the accepted quote and its expiry terms with the payable.
Validate limits against the legal sender and payment purpose
Ask whether limits apply per transfer, over a rolling period, to a funding instrument, or to the verified sending entity. Confirm that the account is approved for business use. Do not split payments to evade limits or route company obligations through employees’ personal accounts.
Measure delivery through beneficiary credit
Separate funding acceptance, compliance review, conversion, payment submission, and beneficiary credit. Fast movement on the receiving rail cannot eliminate an earlier verification hold. Communicate an estimated receipt time only after checking the provider’s conditions and outstanding requirements.
A checklist for recipients who request Google Pay
For a team paying hundreds of overseas recipients, the useful control is to separate recipient preference from approved payment instructions. A familiar app name belongs in the preference field; it should not determine routing by itself.
- Clarify the request. Ask whether the recipient means a UPI-linked bank account, a merchant checkout, or a specific remittance service.
- Identify the beneficiary. Match the legal name and individual or business status to the contract and invoice.
- Confirm commercial eligibility. Obtain confirmation that the provider supports your sending entity, destination, and payment purpose.
- Collect route-specific data securely. An Indian bank-credit route may require the beneficiary name, account number, and IFSC. Other destinations have different requirements. Collect only what the selected provider requires.
- Check documentation. Ask what invoice, purpose, tax, or inward-remittance evidence is needed and what the provider can supply.
- Approve the economics. Record the sender debit, recipient amount, currency, fees, and delivery estimate.
- Close the payment loop. Retain the transaction reference, confirm beneficiary credit, and reconcile fees and FX differences against the payable.
A structured vendor onboarding portal can help collect payment preferences and required details without treating free-text requests as approved instructions. For bank-routing requirements, use the country-by-country contractor payment guide alongside the selected provider’s current requirements.
Hypothetical example: an Indian contractor requests GPay
A US company receives an invoice from an Indian contractor with a phone number and the note “Google Pay accepted.” AP should not assume that the phone number is internationally routable.
Instead, AP confirms the beneficiary’s identity and selects a provider that explicitly supports the commercial payment. If the supported route is an Indian bank credit, it collects the required bank details through a secure workflow. It also confirms which remittance documentation the contractor needs before releasing funds.
The contractor may use Google Pay for everyday access to the same bank account. That does not make the company’s payment a Google Pay remittance.
Choose the transfer route, not the app label
Google Pay can describe a checkout interface, a domestic payment experience, or a feature connected to another provider. None of those labels alone proves that an international business payout is supported.
For recurring overseas payments, start with the corridor, commercial purpose, recipient data, net amount, and evidence of delivery. Then evaluate Payouts.com’s payout automation against those requirements. The next step is to validate the routes your recipients actually need—not to build a payment policy around an app name.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
How to Pay International Contractors: A Country-by-Country Bank Payment Guide
A successful contractor payment delivers the agreed amount—not just a completed transfer instruction. Build a country-specific payment plan around bank details, currency, fees, and the date funds become available.
Flipkart Affiliate Account: Access, KYC, and Payout Rules
A Flipkart affiliate account connects referral sales to commissions, but your registration route determines who pays you. Learn what to verify about access, identity documents, thresholds, and Indian bank settlement.
Payment Methods for Small Business: Collect Locally, Pay Globally
The right payment mix helps customers pay easily without making international vendor payments expensive or difficult. Choose methods around both sides of your cash flow.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.