

Klarna Launches Stablecoin to Cut Cost of Cross-Border Payments
KlarnaUSD signals a move toward stablecoins inside payment providers’ settlement infrastructure. For finance teams, the opportunity depends on end-to-end economics—not just cheaper blockchain transfers.
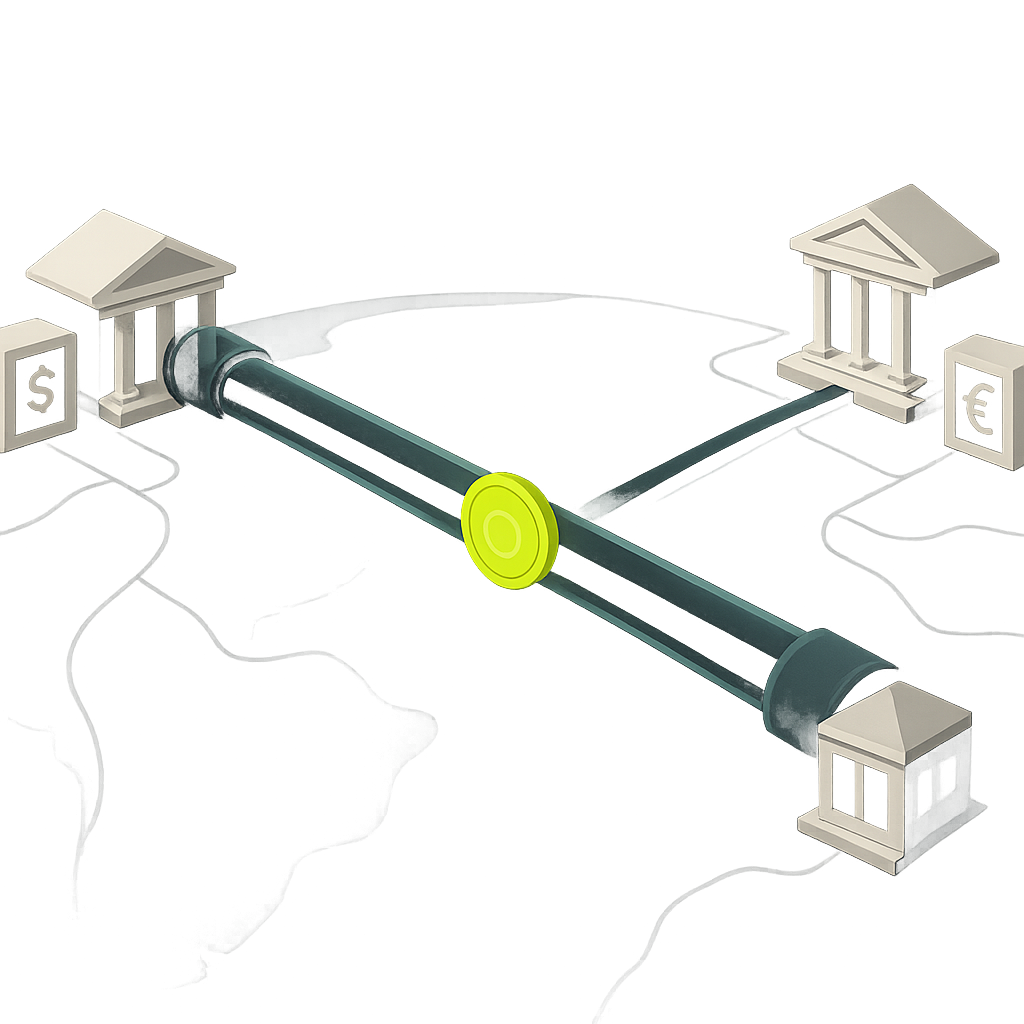
Klarna announced KlarnaUSD, a dollar-backed stablecoin intended to help reduce international payment costs, on November 25, 2025. Built using Open Issuance by Bridge and designed for the Tempo blockchain, it represents a move toward stablecoins inside Klarna’s payment infrastructure—not proof that merchants can already select a cheaper payout method.
The important qualification: Klarna’s announcement described a testnet deployment and targeted a mainnet launch in 2026. The sources reviewed for this article, as of October 22, 2026, do not confirm a completed mainnet launch or public rollout. Finance teams should distinguish the announced infrastructure from a production service they can contract for today.
What Klarna announced—and what remains unconfirmed
According to Klarna’s official announcement, KlarnaUSD uses Bridge’s issuance infrastructure and runs on Tempo, a payments-focused blockchain started by Stripe and Paradigm. At announcement, the token was available on testnet for testing and integration, rather than public use.
A testnet deployment lets a company develop transaction flows and integrations without demonstrating production liquidity, commercial availability, or recipient access. Those are separate milestones.
The intended starting point is also narrower than the headline might suggest. Payments Dive reported that Klarna’s first focus would be internal uses, including reducing the cost of international payments within Klarna. Peer-to-peer payments and cross-border merchant payments were areas for further exploration; the spokesperson did not specify an exact operational launch date.
| Issue | What the evidence establishes | What finance teams still need |
|---|---|---|
| Deployment | Testnet announced; mainnet targeted for 2026 | Confirmed production availability |
| Infrastructure | Bridge issuance; Tempo blockchain | Contractual service responsibilities |
| Initial focus | Internal international payment costs | External merchant eligibility |
| Economics | Cost reduction is an objective | Corridor-specific pricing and results |
| Recipient access | Public rollout not confirmed in reviewed sources | Supported redemption and payout routes |
There is no verified KlarnaUSD savings percentage in the supplied evidence. Industry estimates of stablecoin savings should not be presented as Klarna’s achieved results.
How KlarnaUSD could reduce cross-border costs
The economic opportunity is to change the settlement path behind a payment. A provider may move dollar-denominated value between approved counterparties on a blockchain instead of using a chain of correspondent banks for that leg of the transaction.
That can reduce intermediary charges and make funds movement less dependent on bank processing windows. But a blockchain transfer is only part of a cross-border payout. Funding, currency conversion, compliance, redemption, and local bank delivery remain relevant.
Internal settlement can be a practical starting point
Internal flows offer a more controlled environment than an immediate public rollout. A provider can define approved wallets, counterparties, funding rules, and reconciliation procedures before adding a broad population of external recipients.
This is the strategic significance of Klarna’s stated sequencing. A merchant could eventually receive an ordinary bank deposit while a stablecoin handles an intermediate settlement leg. The recipient would not necessarily need to hold tokens or manage a wallet.
That is a possible operating model, not a confirmed description of KlarnaUSD’s production design. It also explains why a stablecoin announcement does not automatically create a new merchant-facing payment option.
Faster movement may improve liquidity use
If value can move between funding locations more predictably, a provider may be able to reduce some precautionary prefunding. However, local disbursement partners may still require balances in advance, and fiat redemption may remain subject to processing windows.
The relevant treasury question is therefore not simply whether tokens move quickly. It is whether usable funds reach the account that must make the next payment. This is the same distinction explored in real-time treasury and liquidity management.
Dollar settlement does not remove FX
A dollar-backed token can simplify the dollar settlement leg. It does not eliminate exchange-rate exposure when the payer funds in another currency or the recipient requires local currency.
A non-dollar-to-non-dollar payment could require conversion into dollars and then into the destination currency. Depending on pricing and liquidity, that route may be less attractive than a direct FX conversion followed by a local payout.
The strategic question: Who captures the savings?
KlarnaUSD’s announced internal focus creates an important distinction between provider savings and customer savings. Lower settlement costs could improve Klarna’s economics without immediately changing the price or timing offered to merchants.
Finance leaders should look for how any benefit appears commercially:
- Lower explicit fees: a reduced settlement or payout charge.
- Better FX pricing: a narrower spread against a clearly defined benchmark.
- Earlier access to funds: a contractual improvement in availability, not just faster token movement.
- Fewer deductions: more predictable net proceeds in the receiving account.
Issuing a branded stablecoin also adds a question that generic blockchain adoption does not answer: why use this particular token? The business case depends on its funding and redemption arrangements, acceptance by settlement partners, and integration into the provider’s existing flows.
Brand recognition alone does not establish liquidity or convenient redemption. A finance team needs to know which counterparty will convert the token into bank money, under what conditions, and at what cost.
Where the cost advantage can disappear
Evaluate the complete route, not the network fee in isolation. A useful cost model is:
End-to-end payout cost = funding charges + FX costs + token conversion charges + network and service fees + local delivery charges + liquidity and exception costs.
Avoid double-counting when a provider bundles several components into one quote. Measure the amount debited, the amount credited, and the time until the recipient can use the money.
For KlarnaUSD or any comparable proposal, particular limitations deserve attention:
- Redemption access: the payer, merchant, or intermediary may not have the same redemption rights.
- Banking dependencies: a continuously operating blockchain does not make every bank endpoint continuously available.
- Issuer and reserve exposure: dollar backing does not make a token identical to an insured bank deposit.
- Jurisdictional restrictions: permission to issue, hold, transfer, or redeem must be assessed for the relevant entities and markets.
- Operational recovery: incorrect wallet details or an unsupported network can require a different recovery process from a bank-payment return.
The reviewed evidence does not establish KlarnaUSD’s complete production compliance framework. Do not infer worldwide eligibility from the announcement or assume that using an issuance provider removes the payment operator’s obligations.
A finance checklist for evaluating the announcement
Companies paying hundreds of international vendors, contractors, or sellers should treat KlarnaUSD as a development to monitor—not a reason to replace working payout routes before availability and economics are established.
- Verify the service milestone. Request confirmation of mainnet availability, eligible legal entities, supported jurisdictions, and whether access is internal-only or customer-facing.
- Map the contractual money path. Identify who receives fiat, who issues or supplies tokens, who holds them, who redeems them, and who delivers the final payment.
- Separate token settlement from payout completion. Require status definitions for blockchain confirmation, redemption, local submission, and beneficiary credit.
- Obtain an end-to-end quote. Compare the same funding currency, recipient amount, payment purpose, and delivery deadline against the current route.
- Confirm recipient data requirements. Establish whether the route needs wallet details, bank identifiers, beneficiary verification, payment-purpose information, or supporting documents.
- Test exceptions and fallback. Define ownership for screening holds, failed redemption, incorrect details, and delayed local credit. Prevent duplicate payment when switching routes.
- Set a production acceptance gate. Require usable recipient funds, reconcilable records, acceptable risk, and a demonstrable commercial advantage before expanding volume.
Use a corridor-based payout evaluation rather than assuming that a successful internal settlement test proves readiness across every destination.
The takeaway: Follow the settlement economics
Klarna’s stablecoin announcement matters because it places digital settlement infrastructure inside the strategy of an established payments business. Its initial internal focus suggests a measured route toward changing how money moves behind customer-facing services.
But the announcement is not evidence of public availability, guaranteed savings, or universal merchant acceptance. The finance team’s test remains practical: does the complete route deliver the required funds more economically, reliably, and transparently?
Start by documenting a high-friction corridor and its current costs, funding requirements, and exception rates. Then assess new rails against that baseline. For teams coordinating those workflows, explore Payouts.com’s payout automation as part of a broader multi-rail operating model—not as an assumption of KlarnaUSD support.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
Real-Time Treasury Explained: How Finance Teams Are Rethinking Liquidity in Motion
Real-time treasury moves beyond batch reporting and end-of-day snapshots, giving CFOs and controllers a live, actionable picture of every dollar in motion. This guide explains the mechanics, the operational payoff, and what it takes to build it.
How to Evaluate a Mass Payout Platform: Test Corridors, Not Country Counts
Country coverage is not proof that a platform can deliver your payment run. Use a corridor-level acceptance test to evaluate costs, recipient requirements, delivery evidence, and failure handling.
How Does eBay Pay Sellers? Methods, Deductions, and Net Proceeds
eBay collects buyer payments and pays sellers their net proceeds through supported payout destinations. Here is how account setup, deductions, currency conversion, and reconciliation fit together.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.