

Mass Payout Solutions: Make Every Payment Run Accountable
A successful bulk upload is not a successful payment run. Learn how to connect funding, approvals, individual payment outcomes, and reconciliation across international payouts.
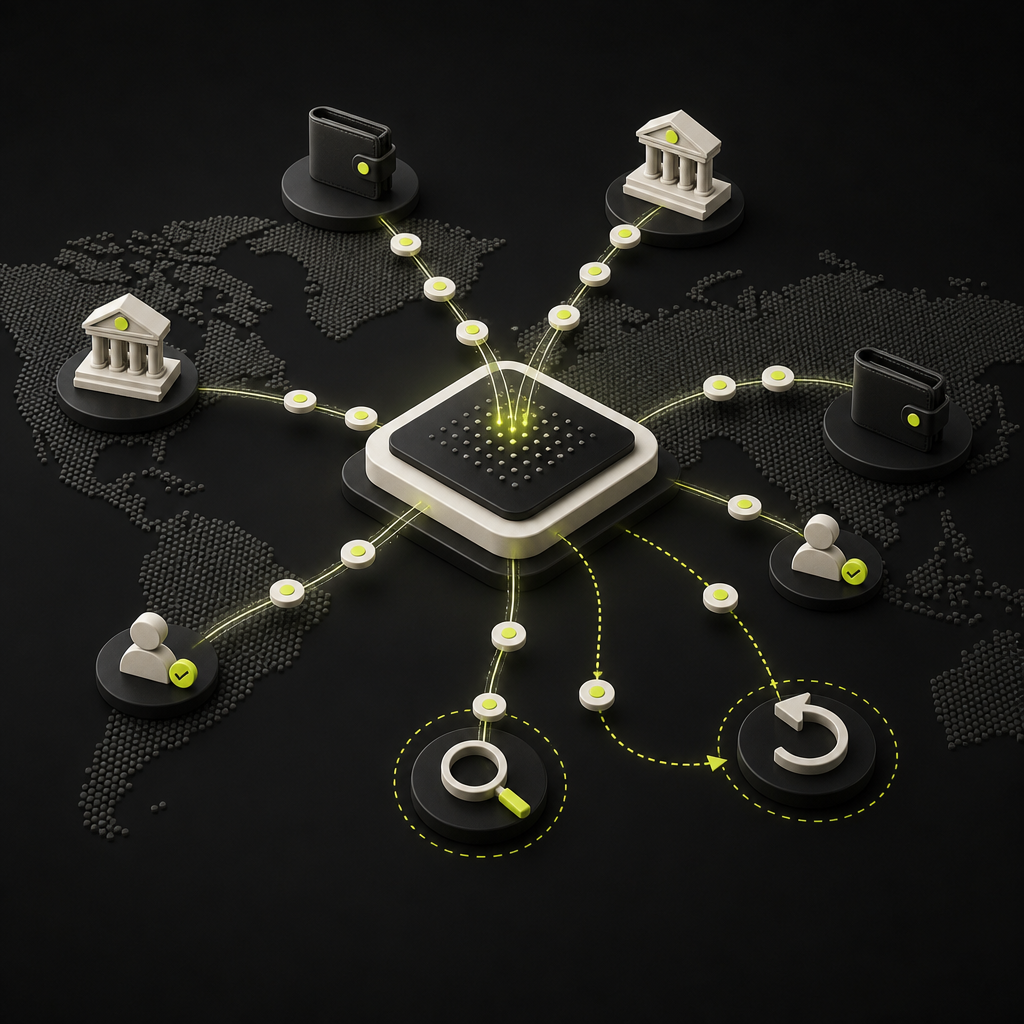
Mass payout solutions let businesses initiate, track, and reconcile payments to many recipients through a shared workflow, typically using a file upload or API. For international payments, they also coordinate currencies, payment rails, recipient requirements, and funding. Their value is not simply sending more payments at once: it is keeping every payment accountable when a batch produces different outcomes.
For finance and operations teams paying hundreds of vendors, contractors, or sellers across borders, the essential question is: Can we explain what happened to each approved obligation and the money allocated to it? This guide focuses on that payment-run discipline—not another ranking of providers.
What mass payout solutions should connect
A bank upload can transmit payment instructions. A broader payout solution should connect those instructions to the obligations that created them, the approvals authorizing them, and the evidence needed to reconcile them.
Common functions include recipient onboarding, batch creation, funding, currency conversion, routing, status reporting, and accounting exports. Availability varies by provider and product. For example, XTRM describes a centrally funded wallet model that distributes funds to different recipient endpoints. That is one architecture, not a universal feature of mass payouts.
Even with these functions, the business must decide who can release funds, which recipient changes require review, and what evidence counts as payment completion. Software does not establish those policies by itself.
Treat the batch as a container, not a payment outcome
A payment run may contain local bank transfers, international wires, and wallet payouts. Some instructions may be rejected before submission; others may be processing, credited, or subsequently returned. A single label such as “batch successful” obscures those differences.
Maintain separate records for the approved obligation, the payout instruction, and each execution attempt. A retry should not create another payable or erase the history of the original attempt.
| Stage | Evidence to retain | Release or closure rule |
|---|---|---|
| Obligation approved | Source reference, amount, currency | Business approval complete |
| Recipient validated | Destination version, required fields | Current details pass checks |
| Funding allocated | Available balance, currency, reservation | Funds cover authorized instructions |
| Instruction submitted | Internal ID, provider ID, timestamp | Acceptance recorded per payment |
| Outcome reported | Status, reason, supporting reference | Provider status meaning understood |
| Run reconciled | Debits, fees, returns, open items | Every amount explained |
Where a provider cannot confirm beneficiary credit, preserve that limitation. Do not translate “sent to bank” into “received by recipient.” Close the accounting workflow using an explicit evidence policy, while retaining visibility into unresolved delivery questions.
Build the payment run before choosing its release time
Validate data against the destination and rail
One universal bank-details form is rarely sufficient. Common routing fields include an account number and routing number for US ACH, a sort code and account number for UK domestic transfers, and an account number and IFSC for Indian bank transfers. These are examples, not complete onboarding requirements; provider, currency, recipient type, and payment purpose can change what is needed.
Store requirements by destination, currency, rail, and recipient category. Validate before scheduling, and distinguish a format check from account ownership verification. A correctly formatted account identifier does not prove that it belongs to the intended recipient.
Freeze the approved destination version for each run. If a recipient changes bank details after approval, hold the affected instruction for review rather than silently redirecting it.
Partition by execution requirements
Group instructions by funding currency, sending entity, provider, and relevant timing constraints. This makes it possible to release eligible payments without confusing their status with payments awaiting funding or documentation.
Decide whether partial release is permitted. Independent contractor invoices may be paid separately, while linked commercial obligations may require coordinated release. That is a business rule, not a technical default.
Keep compliance holds specific and visible
Payment regulation and compliance requirements vary across markets, as outlined in Nuvei’s enterprise payment-compliance overview. Accordingly, document which party handles identity checks, sanctions screening, transaction monitoring, and any applicable reporting.
A provider’s tools do not automatically resolve your own obligations. Give held payments a clear owner, reason category, and escalation route. Never route around a compliance hold merely to complete the batch.
Connect funding, FX, and the recipient’s net amount
A funded account does not necessarily mean a run is ready. Funds may be in the wrong currency, reserved for another run, or unavailable to the sending entity. Calculate releasable balances after existing commitments, rather than relying on a headline wallet balance.
Multi-currency accounts can help finance teams collect and hold funds in different currencies. Holding balances can reduce repeated conversions, but it also creates liquidity and currency-exposure decisions. Establish replenishment rules and review idle balances.
Record the economics at instruction level:
- Amount owed: the approved obligation and its contractual currency.
- Recipient amount: the intended destination amount and responsibility for deductions.
- FX terms: the quoted rate, quote validity, and when conversion becomes binding.
- Charges: payout fees and any known intermediary or recipient-side deductions.
- Return treatment: whether fees are refunded and whether returned funds require another conversion.
Compare costs for the same recipient outcome. A lower sending fee is not necessarily cheaper if the recipient receives less or finance must issue a top-up. Likewise, an instant destination rail does not eliminate onboarding, funding, conversion, or review time.
Make uncertain outcomes safe to investigate
The most dangerous response to an API timeout is an automatic fresh payment. A timeout may mean the provider accepted the instruction but the response never reached your system.
Use stable instruction identifiers and the provider’s documented idempotency mechanism. Confirm its scope and retention period; do not assume that reusing a key prevents duplicates indefinitely. Query the existing instruction before deciding whether another execution attempt is safe.
Webhook processing should also tolerate duplicate and out-of-order events. Retain event history, verify authenticity, and prevent an older message from overwriting a later confirmed state. Supplement event notifications with status queries or reconciliation reports.
Define distinct actions for rejected, pending, returned, and unknown payments. A rejected instruction may be correctable immediately; a payment with an unknown outcome requires investigation. Our failed-payment recovery guide explains how to separate these recovery paths.
Hypothetical example: a mixed-outcome contractor run
Consider a business paying contractors in several currencies. Before release, one recipient changes bank details, another lacks required information, and the remaining instructions pass validation.
Under a documented partial-release policy, operations holds the changed and incomplete records while releasing the eligible payments. Treasury reserves funding only for the authorized release and records the remaining obligations separately.
During execution, a provider request times out. Operations queries its existing instruction identifier rather than submitting a new payment. Later, a different transfer is returned. Finance links that return to the original obligation, records any charges, and authorizes a replacement only after the destination issue is resolved.
The run is not simply “done” or “failed.” Its report explains completed payments, held obligations, funds in transit, and returned amounts. That is the operational result a mass payout solution should support.
A practical payment-run acceptance checklist
Before production release, ask finance and operations to demonstrate that they can:
- Trace every instruction to an approved obligation and a specific recipient-details version.
- Validate required destination data before reserving funds.
- Separate available, reserved, debited, and returned balances by currency.
- Explain partial-release rules and who may override them.
- Investigate a timeout without creating a duplicate payment.
- Interpret each provider status without overstating delivery certainty.
- Reconcile principal, fees, FX, returns, and outstanding obligations.
- Export the evidence needed to investigate a payment independently of the dashboard.
Use representative workflows rather than a clean demonstration batch. For geographic coverage and rail-specific testing, extend this exercise with the corridor-based platform evaluation guide.
Choose accountability over upload capacity
The strongest mass payout solutions keep obligations, funding, execution, and accounting connected—even when only part of a run completes. Upload capacity matters, but exception visibility and financial traceability determine whether the operation remains manageable.
Start by documenting one payment run from approval through reconciliation. Then explore Payouts.com’s payout automation against that workflow, including its holds, uncertain outcomes, and returns. The goal is not merely to send the batch. It is to account for every payment within it.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
3 commentsRelated resources
How to Evaluate a Mass Payout Platform: Test Corridors, Not Country Counts
Country coverage is not proof that a platform can deliver your payment run. Use a corridor-level acceptance test to evaluate costs, recipient requirements, delivery evidence, and failure handling.
Multi Currency Payouts: A Failed-Payment Recovery Guide
A returned cross-border payment is not simply the original transaction in reverse. Learn how to preserve the recipient’s currency entitlement, manage FX differences, and retry payments without creating duplicates.
Daraz Affiliate Account: Choose Your Program and Verify Payouts
A Daraz affiliate account connects promotional activity to commission earnings, but payment rules depend on the country and enrollment route. Verify who pays, which currency you receive, and what makes earnings payable before launching campaigns.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The point about freezing the approved destination version is critical and often overlooked. We had a contractor change their bank details mid-cycle last year, payment went through automatically to the new account, and it turned into a week-long mess proving they were the same entity for audit purposes. Now we flag any changes for manual review even if it delays the run by a day.
Curious how others handle the evidence policy when the provider only confirms funds left their system but can't verify beneficiary credit. We're paying suppliers in markets where correspondent banking adds 2-3 day delays and our ERP wants to close the payable immediately. Right now we're booking it as cleared but flagging for follow-up, which feels like a compromise nobody loves.
"A funded account does not necessarily mean a run is ready" - this hit hard. We're constantly battling the treasury team because our wallet shows a balance but half of it is already committed to scheduled runs or locked for FX settlements. Would love to see more providers surface committed vs. available balances natively instead of making us track it in spreadsheets.