

Mass Payout vs Paxum Payout: Compare the Full Payment Journey
Paxum is a mass payout provider, not an alternative to mass payouts as a category. The useful comparison is how each option gets recipients to usable funds—and what finance must manage along the way.
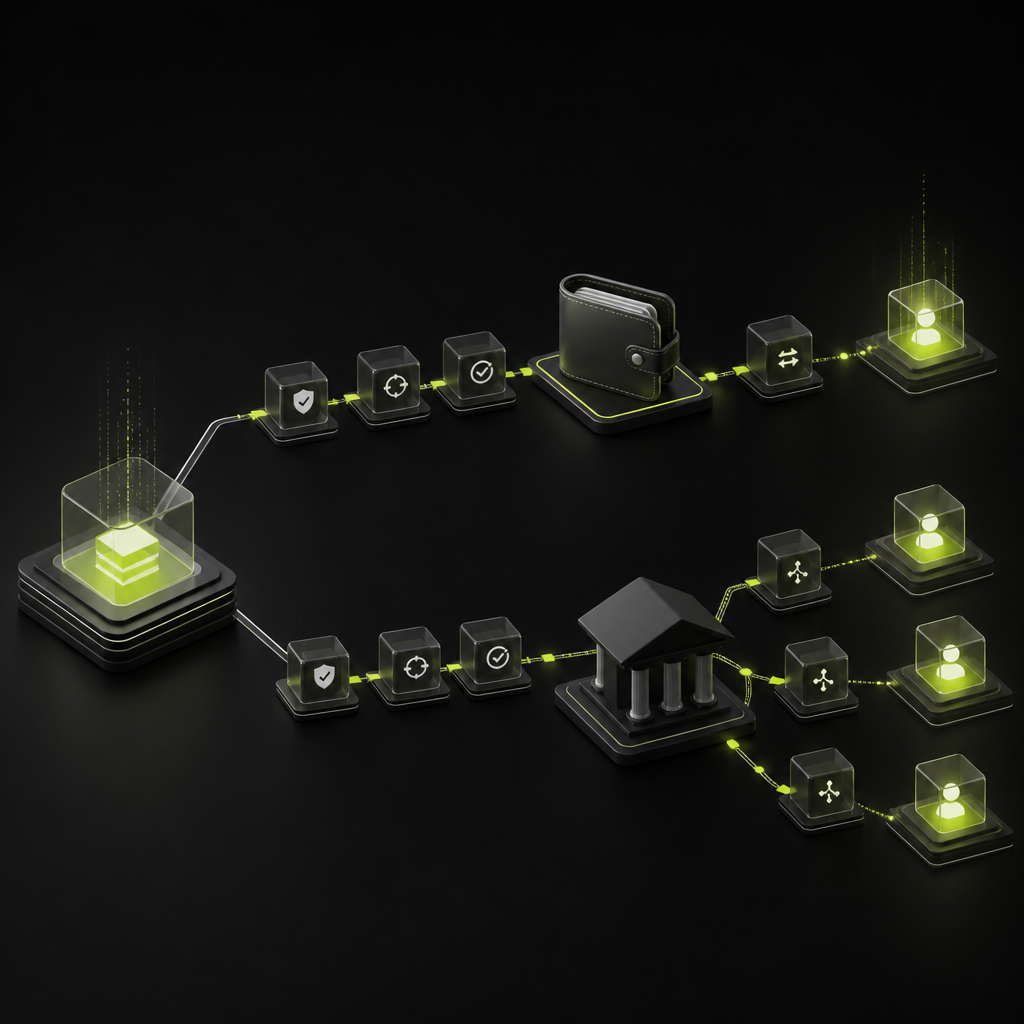
The direct answer: mass payout describes the process of paying many recipients; Paxum is a specific provider that offers that capability. In a mass payout vs Paxum payout comparison, the real choice is between Paxum’s payment model and another provider’s combination of recipient access, payment rails, costs and financial controls.
Paxum deserves consideration when recipients want its payment options and your business is eligible. A broader payout platform may fit better when recipients need different destinations or finance needs payment execution connected to approvals, accounting and treasury. Neither conclusion follows from a low transfer fee or a long country list alone.
For teams paying hundreds of international contractors, affiliates or sellers, the deciding question is simple: what must happen between approving a payable and the recipient being able to use the money?
What exactly are you comparing?
A mass payout platform accepts multiple payment instructions, typically through a file, interface or API, and processes them for individual recipients. Depending on the provider, payments may go to bank accounts, wallets, eligible cards or other destinations. A batch is an operational grouping—not necessarily a single settlement event.
Paxum’s official mass payout offering places it within that category. Its account FAQ identifies mass payouts as a business-user capability. A recipient’s ability to receive money therefore should not be confused with a sender’s eligibility to run business payment batches.
Do not reduce the comparison to “wallet versus bank.” Paxum’s affiliate-network materials describe paying affiliates even when they do not have a Paxum account. Confirm the actual destination, onboarding requirements and availability for your specific program rather than assuming every recipient must open a wallet.
Paxum and broader mass payout platforms: practical comparison
The table below is an editorial fit assessment, not a scored product test. Broader platforms vary considerably; their capabilities must be verified individually.
| Decision area | Paxum evaluation | Broader platform evaluation | Best-fit signal |
|---|---|---|---|
| Recipient access | Confirm wallet and non-account routes | Confirm direct and wallet destinations | Matches recipients’ preferred endpoint |
| Business eligibility | Business mass payout approval required | Provider underwriting varies | Written acceptance of your activity |
| Total cost | Include funding, conversion and withdrawal | Include platform and delivery charges | Competitive cost to usable funds |
| Payment timing | Separate wallet credit from withdrawal | Separate submission from destination credit | Timing matches the recipient promise |
| Finance controls | Verify approvals and accounting outputs | Verify execution and workflow scope | Clear ownership of each control |
| Operational fit | Potential fit for Paxum-preferring cohorts | Potential fit for mixed recipient needs | Less recipient friction and manual work |
Compare the recipient endpoint, not just the transfer
Wallet credit and bank cash are different milestones
Where a payout credits a wallet, the recipient may still need to complete a withdrawal or conversion before paying local expenses. If the recipient actively uses that wallet, this may be convenient. If they only want bank cash, it adds a step.
Direct bank delivery removes that particular withdrawal step, but it does not remove screening, bank processing, FX or potential receiving charges. Neither model is universally faster or cheaper.
Ask recipients what they actually need: a balance they can use within a payment service, local-currency bank funds or another supported destination. Then compare providers at that endpoint.
Do not force existing users to migrate without a reason
A recipient already comfortable with Paxum may value keeping it. Moving that person to another service can create onboarding work without improving their experience. Conversely, requiring an unfamiliar wallet for recipients who need local bank deposits can increase support demand.
Segment the recipient base by preference, destination country, currency and account type. If maintaining multiple providers is justified, document which system owns each payment obligation. Otherwise, a recipient changing methods during a payment run can become a duplicate-payment risk.
Build the cost comparison around net recipient proceeds
The supplied research contains conflicting Paxum fee figures from secondary sources. Those figures are not a dependable tariff. Obtain a current business quote and route-specific recipient charges before making a pricing decision.
Compare the total cost of delivering the same usable amount in the same destination currency. Include:
- Sender funding: charges for moving money into the provider and any conversion before payment.
- Payment execution: per-payment charges, minimum fees and contracted platform costs.
- Foreign exchange: the executable rate, conversion point and any separately charged conversion fee.
- Recipient access: wallet withdrawal, destination-bank or intermediary deductions where applicable.
- Exceptions: return charges, refund conversion effects and operational handling.
Compare FX quotes at comparable times and for the same amount. A funding conversion followed by a recipient withdrawal conversion can produce a different outcome from direct local-currency delivery.
Also separate company cost from recipient deductions. Passing withdrawal costs to recipients may reduce the sender’s invoice without improving the economics of the payment journey. The cross-border payment fee guide provides a framework for auditing those layers.
Define “paid” before comparing speed
A fast balance transfer is not necessarily a fast withdrawal. Equally, an accepted bank payment instruction is not proof that the beneficiary has been credited.
For both Paxum and any alternative, request definitions and available evidence for these milestones:
- Funding available: the sender’s balance can actually fund the payment.
- Instruction accepted: the provider has validated and accepted the request.
- Destination credited: money has reached the specified wallet or account.
- Usable funds: any necessary recipient withdrawal or conversion is complete.
A provider may not observe every downstream event. Record that visibility boundary rather than presenting an estimated withdrawal as confirmed delivery.
Align customer communications and accounting policy with the contracted destination. Whether wallet credit satisfies a payment obligation depends on the agreement and applicable requirements; it should not be decided by an API status label.
Check controls without assuming that missing documentation means missing capability
The available evidence does not establish a complete comparison of Paxum’s approval controls, tax workflows, reconciliation exports or API failure handling. Ask for demonstrations and contract documentation. Apply the same standard to alternatives.
Require answers to operational questions that a successful transfer alone cannot resolve:
- Can one user change recipient details and release the resulting payment?
- What happens if a batch partially succeeds?
- How does the integration prevent duplicate execution after a timeout?
- Can finance match each payable to funding, payment, fee, FX and return records?
- Who owns recipient verification, sanctions screening, tax documentation and reporting?
- What evidence is retained when a payment is held, rejected or returned?
Provider identity checks do not automatically satisfy the payer’s tax obligations. Requirements depend on the paying entity, recipient, payment type and jurisdiction. A workflow such as tax documentation and compliance management should be evaluated separately from the ability to move funds.
A hypothetical decision: retain Paxum, replace it or use both?
Hypothetical example: an affiliate business has an established group that prefers Paxum and a growing contractor group that wants local bank payments.
The finance team should not assume either that Paxum requires wallet onboarding for everyone or that another provider serves every destination better. It should request confirmed routes and quotes for both groups.
Retaining Paxum may make sense for recipients who prefer it. Another platform may be justified for contractors if it demonstrably improves access or integrates more effectively with payable approvals. Using both introduces additional funding and reconciliation work, so that benefit must outweigh the operating burden.
In a dual-provider setup, maintain one payable identifier and one active execution owner. Do not reroute an uncertain payment until its status is resolved sufficiently to avoid paying twice.
Buyer checklist and next step
- Confirm eligibility: obtain acceptance for your legal entity, business activity and recipient types.
- Document recipient access: verify wallet requirements, non-account routes and destination eligibility.
- Price the complete journey: request sender charges, executable FX and recipient deductions.
- Define completion: distinguish provider acceptance, destination credit and withdrawal.
- Demonstrate exceptions: test invalid details, partial batches, timeouts and returns.
- Assign control ownership: document approvals, compliance responsibilities and accounting evidence.
The best choice is the one that delivers the agreed recipient outcome with manageable cost and defensible controls. Paxum can belong on that shortlist; the category label “mass payout platform” does not make another provider inherently better.
If your comparison extends beyond execution to managing the broader money cycle, evaluate Payouts.com’s payout automation against the same checklist. Start with a representative recipient file and ask each provider to show the full journey from approved payable to usable funds.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
3 commentsRelated resources
How to Reduce Cross Border Payment Fees: A Finance Playbook
Lower transfer fees do not always mean cheaper payouts. Learn how to negotiate, operationalize, and verify savings across your international payment program.
eBay Affiliate Account: Setup, Commissions, and Payment Controls
An eBay affiliate account earns referral commissions through the eBay Partner Network—not seller proceeds. Here’s how to set it up and connect reported earnings to usable cash.
Apple Pay International Transfer: Funding vs. Payouts
Apple Pay can fund some international transfers, but it is not itself a cross-border payout rail. Understand the difference between card authorization, provider funding, and money reaching your recipient.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
How are people actually getting visibility into the "instruction accepted" vs "beneficiary credited" gap? Our treasury team treats the batch submission as complete but we have zero confirmation of final receipt unless someone complains.
"Do not force existing users to migrate without a reason" - wish our previous finance director had read this. We moved 300+ affiliates off their existing wallet to consolidate vendors and the support tickets were brutal for three months.
The point about comparing cost to usable funds instead of just transfer fees is critical. We switched providers last year based on advertised rates and didn't factor in recipient withdrawal charges. Our contractors in Southeast Asia ended up paying $8-12 per withdrawal, which basically wiped out the savings we thought we were getting. Now we map the full journey before making any decision.