

Mobile Pay International Transfer: From App to Usable Funds
A mobile app can initiate an international transfer without guaranteeing mobile-wallet delivery. Learn how to verify the destination, recipient requirements, and usable funds before scaling business payouts.
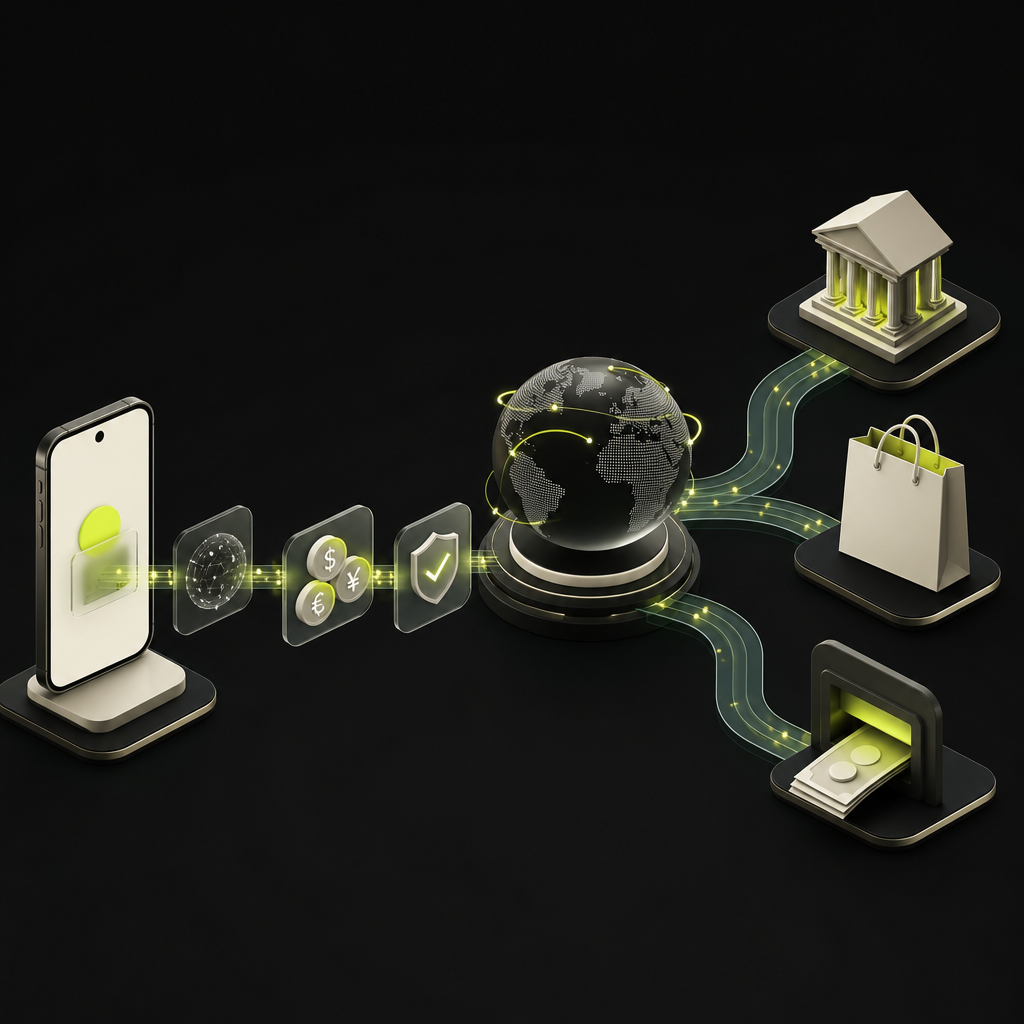
A mobile pay international transfer is possible when the provider supports your sending country, destination, funding method, and recipient account. The phone is the interface—not the payment rail. Money may arrive in a bank account, a mobile-money wallet, or through cash pickup, depending on the service and corridor.
If you mean the specific service MobilePay, rather than mobile payments generally, verify its supported country pair and transfer type directly. Do not assume that a domestic phone-number payment feature supports international transfers or business disbursements. This guide covers the broader category of mobile-initiated and mobile-wallet international transfers.
For finance teams paying hundreds of contractors, vendors, or sellers, the key question is not whether someone can send money from a phone. It is whether the intended recipient can receive and use the correct amount, under a business-supported workflow, with evidence finance can reconcile.
Separate the app, the funding method, and the destination
Three different capabilities often get bundled together under “mobile transfer”:
- Mobile initiation: A sender creates or approves a transfer in an app.
- Mobile-wallet funding: A supported wallet or its linked payment credential funds a transfer.
- Mobile-wallet delivery: The recipient receives value in a supported wallet account.
These are not interchangeable. A service accepting Apple Pay as a funding option does not necessarily deliver money to the recipient's Apple wallet. Likewise, an app-based transfer can end as a conventional bank deposit.
The Statrys international transfer app comparison describes different funding and delivery options across providers, including wallet-based funding options for Wise. Treat those options as provider-specific: availability still needs checking for the sender's location, account type, and transaction.
Destination choice matters independently. For example, WorldRemit's service overview distinguishes bank deposits, cash pickup, mobile money, and airtime top-ups. Airtime is not a cash-equivalent business payout simply because it reaches a mobile phone.
How an international mobile transfer works
- The sender creates an instruction. It identifies the recipient, destination country, currency, amount, and delivery method.
- The provider checks eligibility. Identity checks, payment-purpose restrictions, recipient requirements, and transaction limits can affect acceptance.
- Funding becomes available. A bank debit, card payment, or prefunded balance supplies the money. Authorization and available funds are not always the same event.
- The provider handles currency conversion and routing. It may use a payout partner and local liquidity rather than send an individual bank wire across the entire route.
- The destination institution credits the recipient. That may be a bank or mobile-money operator.
- The recipient accesses the value. They spend it, move it to a bank, or withdraw cash, subject to destination rules and charges.
An “instant” delivery claim may describe only the destination-credit step. Funding delays, compliance review, unavailable wallet capacity, or an incorrect identifier can still hold up the overall payment.
Build the promised delivery window from funding acceptance to recipient credit. Separately explain any conditions affecting withdrawal or use.
Verify the receiving wallet—not just the phone number
A phone number can be a payment alias, but it is not sufficient evidence of account ownership or payout eligibility. Numbers can change hands, recipients can change operators, and the same country can have several wallet networks.
The required data should come from the provider's current corridor specification. Avoid a single global form that assumes every wallet uses the same fields.
| Field or check | What to establish | Failure it helps prevent |
|---|---|---|
| Destination country and currency | Supported receiving combination | Wrong route or currency |
| Wallet operator or network | Exact supported destination | Misrouted wallet payment |
| Mobile number or wallet ID | Provider-required format | Invalid recipient identifier |
| Registered account name | Match to the intended payee | Payment to another person |
| Verification status | Eligibility for inbound transfers | Restricted-account rejection |
| Transaction and balance limits | Capacity for the incoming amount | Limit-related failure |
| Payment purpose and documents | Requirements for this business payment | Compliance hold |
| Withdrawal or spending access | How the recipient will use funds | Credited but impractical funds |
Collect additional identity or purpose information only where required, through a secure workflow. Revalidate a changed wallet identifier before releasing payments; a message from a new phone number should not itself authorize a beneficiary change.
A self-serve vendor onboarding workflow can organize collection and updates, but collection is not validation. Define which checks must pass before a recipient becomes payable.
Measure total cost through the recipient's intended use
Comparing advertised transfer fees alone can reward the wrong route. Request quotes for the same destination amount, funding method, and delivery option at comparable times.
Separate the cost into:
- Sender charges: Transfer fees and applicable funding charges.
- Currency conversion: The quoted exchange rate and its difference from a consistent reference rate.
- Destination deductions: Receiving or intermediary charges, where applicable.
- Access costs: Wallet withdrawal, cash-out, or onward bank-transfer charges.
Do not count an FX margin twice if it is already reflected in the sender's quoted debit. Record the total sender debit, the promised recipient credit, and any subsequent access cost separately.
The right endpoint depends on the recipient. Wallet credit may be sufficient for someone who pays expenses directly from that wallet. A supplier needing bank cash may care more about the cost and time of moving funds out.
For a consistent procurement method, use a cross-border payment cost review rather than assuming mobile transfers are always cheaper than bank delivery.
Check business eligibility before building a payment run
A consumer app's destination coverage does not establish permission to pay commercial invoices, contractors, or marketplace sellers. Confirm that the provider supports your legal entity, payment purpose, recipient category, and expected volume.
Ask for clear answers to these operational questions:
- Can the company hold the account, or is it tied to an employee's personal identity?
- Are commercial payments allowed through this specific product and corridor?
- Can payment creation and release be assigned to different authorized users?
- Are batch files or APIs supported, and how are duplicate submissions prevented?
- Which reference connects the obligation, provider transaction, and destination result?
- What happens to fees, FX, and principal when a transfer fails or is returned?
Transaction caps, daily limits, and maximum wallet balances are different constraints. A recipient can be eligible for a transfer yet lack sufficient balance headroom to receive it. Do not split payments to bypass provider restrictions or reporting controls.
Hypothetical example: a successful credit that misses the payment need
A company pays a contractor in the contractor's preferred mobile wallet. The provider reports successful credit, and finance marks the transfer complete. The contractor then explains that the invoice proceeds must reach a bank account to cover business expenses.
The wallet route was technically successful but operationally unsuitable if onward transfer costs or restrictions were not understood beforehand.
The better design captures the recipient's intended endpoint during onboarding: wallet spending, bank funds, or cash access. It records what the company promises to deliver and which downstream charges the recipient accepts. If the route cannot meet that agreement, offer a supported alternative before payment—not a second transfer after the first has already succeeded.
A launch checklist for mobile-wallet payouts
- Define the payment obligation. Specify currency, recipient amount, due date, and agreed delivery endpoint.
- Approve the exact route. Verify sender country, destination network, business purpose, and receiving account eligibility.
- Validate recipient data. Check formatting, ownership evidence, required documents, and beneficiary-change controls.
- Confirm limits and liquidity. Check funding availability, sender limits, and destination constraints.
- Capture the quote. Preserve fees, exchange rate, recipient amount, and quote validity where available.
- Run a controlled pilot. Test permitted success and failure scenarios without assuming a small successful payment proves all amounts will work.
- Reconcile the result. Connect the payable, funding debit, provider reference, destination confirmation, and any return.
- Define exception ownership. Assign responsibility for pending transfers, rejected wallets, refunds, and recipient communication.
Keep “submitted,” “accepted,” and “credited” distinct. A timeout is not proof of failure: check the existing transaction before retrying or switching routes. Establish that process using a failed-payment recovery workflow.
Choose mobile delivery when it fits the obligation
Mobile international transfers can make funds accessible through a familiar recipient interface. Their suitability for business payouts depends on the underlying route, permitted use, account limits, costs, and quality of delivery evidence—not the convenience of the app alone.
Start with your recipients' wallet networks and intended use of funds. Then evaluate business-supported delivery and controls. Explore Payouts.com payout automation to discuss how supported routes can fit into a centralized payment operation, and verify each required wallet corridor before committing to rollout.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
3 commentsRelated resources
Multi Currency Payouts: A Failed-Payment Recovery Guide
A returned cross-border payment is not simply the original transaction in reverse. Learn how to preserve the recipient’s currency entitlement, manage FX differences, and retry payments without creating duplicates.
How to Reduce Cross Border Payment Fees: A Finance Playbook
Lower transfer fees do not always mean cheaper payouts. Learn how to negotiate, operationalize, and verify savings across your international payment program.
Cross-Border Payments in Latin America: Country Readiness Guide
Latin America’s domestic payment networks can deliver fast local payouts, but the cross-border operation still depends on funding, FX, and country-specific data. Build a country readiness matrix before promising recipients a delivery time.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Separating mobile initiation from mobile-wallet delivery is critical and something our sales team still doesn't understand. They keep promising "instant mobile payouts" when we're actually doing app-initiated transfers that land in bank accounts 1-2 days later. The disconnect between interface and rail needs to be in every RFP response we write.
Question on the access costs piece: how are other teams handling the reconciliation when the recipient incurs withdrawal fees that weren't visible at send time? We've had contractors complain about net-received amounts, but our AP system only tracks what we debited and what the provider confirmed as delivered.
The table showing "Field or check" versus "Failure it helps prevent" is exactly what we should be using during vendor onboarding. We're currently just collecting phone numbers and assuming the wallet operator, which has already caused two failed payouts this quarter. Going to adapt this for our supplier form.