

My Affiliate Account: Understand Balances and Payout Status
An affiliate account should explain more than what you earned. Learn how to distinguish commission balances from money in transit—and what global payout teams should make visible.
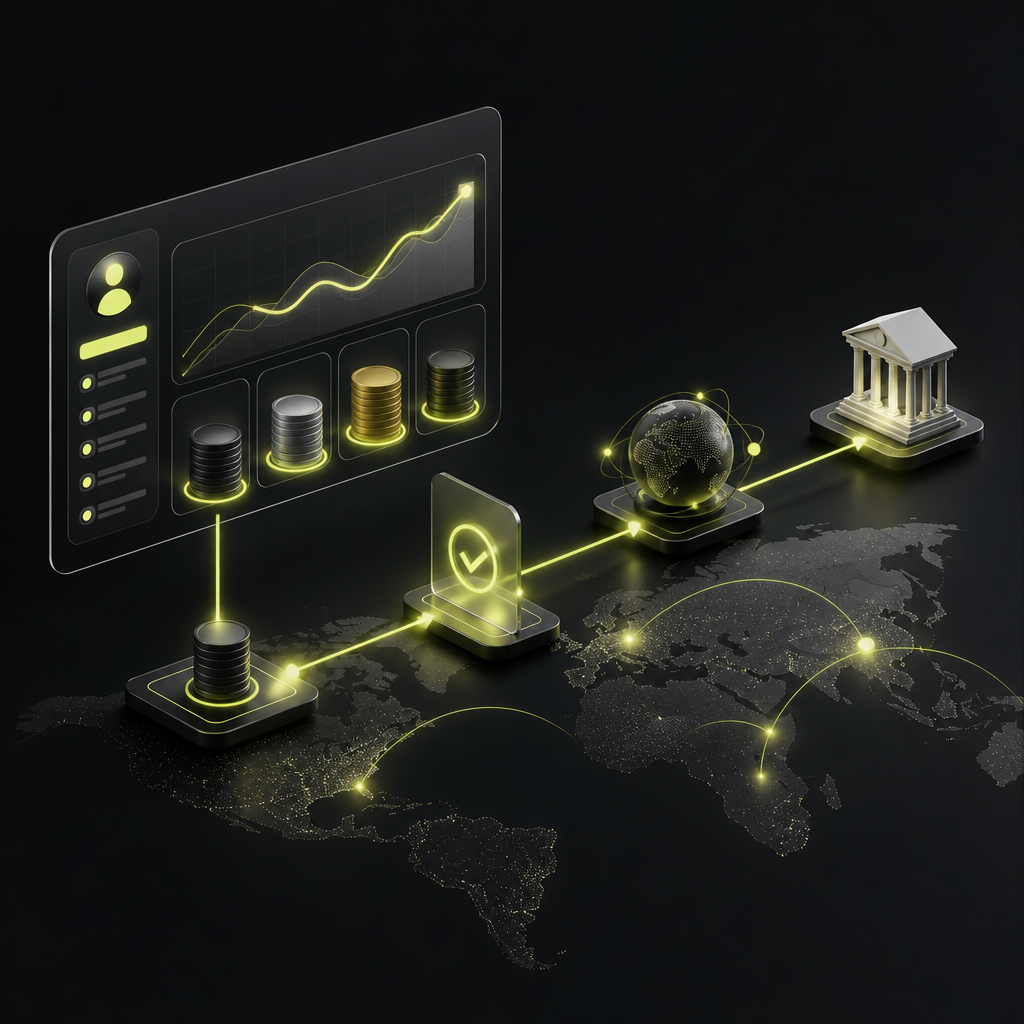
Your affiliate account is the program-specific portal where you track commissions, manage payment details, and check payouts. If you are searching for “my affiliate account” to sign in, use the affiliate link on the merchant’s official website or your verified enrollment email. There is no universal affiliate account login across programs.
Once inside, distinguish recorded earnings, approved commissions, payable funds, and payments already sent. These are different stages, and a positive dashboard balance does not necessarily mean money is available to withdraw.
For finance and operations teams paying affiliates internationally, that distinction is also a design requirement. A useful account view explains where the money is, what happens next, and who must act—without making affiliates decode internal payment terminology.
How do I find the right affiliate account?
Start with the business whose products or services you promote. Its affiliate program may run on its own website or through a separate affiliate network. Your customer login, affiliate login, and payment-provider login may be different.
- Confirm the program: Check the merchant name, network, and account email against your enrollment confirmation.
- Use an official entry point: Navigate from the merchant’s website rather than a sponsored search result or an unsolicited payment message.
- Recover access securely: Use the portal’s password-reset process. Do not send passwords or authentication codes to support.
- Check the payout destination separately: Access to a wallet or bank account does not establish access to the affiliate program itself.
If you belong to multiple programs, keep their statements separate. A commission recorded by one merchant cannot normally be withdrawn through an unrelated program’s account.
What does the balance in my affiliate account mean?
An affiliate dashboard combines commercial activity with payment information. Tipalti’s affiliate payments guide describes affiliate payment operations as broader than sending a transfer: they also involve payee information, payment methods, and payment management. The account view should preserve those distinctions.
The following is a recommended interpretation framework, not a universal set of platform labels. Always check the program’s definitions.
| Account label | What it should mean | What to check next |
|---|---|---|
| Pending commission | Recorded activity awaiting validation | Review or refund-period rules |
| Approved commission | Commission accepted by the program | Release date and eligibility |
| Payable balance | Amount eligible for a payment run | Threshold, holds, and schedule |
| Scheduled payout | Payment planned but not yet submitted | Scheduled date and destination |
| Processing or sent | Instruction submitted or funds moving | Provider status and arrival estimate |
| Completed | Completion under the provider’s definition | Whether beneficiary credit is confirmed |
| Failed or returned | Transfer rejected or funds returned | Reason, correction, and retry status |
A program threshold is not an industry-wide entitlement. Minimum amounts, approval periods, payment schedules, and withdrawal options depend on the program. A threshold can also apply separately by currency or method; the portal should say whether that is the case.
Why approved earnings may not be withdrawable
Commission approval answers whether the program owes the commission under its rules. Payment eligibility answers whether it can release that obligation now. A scheduled release date, incomplete documentation, an unsupported destination, or a review hold can separate the two.
Operators should show each blocker individually. “Payment unavailable” is less useful than “Approved commissions are below the threshold for your selected method,” followed by the applicable policy.
What changes when an affiliate payout crosses borders?
Payment method and receiving account must match
Common affiliate payout options include bank transfers and wallets, but availability differs by program and destination. ReferralCandy’s payout-method overview discusses options including PayPal and Wise; a method appearing in an industry guide does not mean a particular merchant supports it.
The account should identify the selected method, receiving country, payout currency, and masked destination. For bank payments, collect fields required by the actual route rather than presenting one generic international bank form. An IBAN is relevant in IBAN markets; other destinations use domestic account and routing identifiers. Wire instructions may require additional bank information.
For operators, the underlying decision belongs in a local-rail versus SWIFT routing policy. The affiliate-facing view should explain the resulting cost and delivery expectations, not require the recipient to understand correspondent banking.
The commission currency may differ from the deposit currency
A cross-border statement should distinguish the currency in which commissions were earned from the currency sent and received. Before release, show whether the conversion rate is indicative or fixed, who performs conversion, and which fees are known.
- Commission amount: The approved earnings allocated to this payout.
- Deductions: Separately identified adjustments, applicable withholding, and recipient-borne fees.
- Conversion: The currency pair, rate, and time at which the rate becomes binding.
- Recipient amount: Confirmed proceeds or an estimate clearly labeled as such.
Do not promise an exact deposit amount when intermediary or receiving-bank deductions remain uncertain. Equally, do not explain every difference as an “FX fee” when it may be a commission reversal or tax deduction.
Verification is not a single permanent checkbox
Cross-border payment requirements can involve identity verification, sanctions controls, and tax documentation, as outlined in Tipalti’s cross-border compliance overview. Which requirements apply depends on the payer, recipient, jurisdiction, transaction, and provider.
A portal should distinguish “document uploaded” from “document accepted.” It should also explain whether a review affects the whole account or only a particular payout. Avoid blanket claims that every foreign affiliate has the same forms, withholding treatment, or reporting obligations.
What should I do if my affiliate payment is missing?
- Identify the commission period. Check that the earnings belong to the payment cycle you expected.
- Separate approval from release. Look for an approval date, threshold, release rule, or explicit hold.
- Find the payout record. A commission statement alone is not evidence that a transfer was submitted.
- Verify the masked destination. Confirm the method, currency, and account ending without sending full banking credentials over email.
- Check the arrival window. Use the estimate for that payout, including relevant banking days, rather than a general marketing claim.
- Escalate with identifiers. Provide the affiliate ID, payout reference, amount, currency, submission date, and displayed status through the official support channel.
If the payment was rejected or returned, establish what happened to the original transfer before requesting a replacement. Otherwise, a late status update can turn a missing-payment complaint into a duplicate payment. Finance teams can use a structured failed-payment recovery workflow to separate investigation, correction, and resubmission.
For operators: make the account statement explain itself
For programs paying hundreds of international affiliates, the strongest improvement is not another summary balance. It is a traceable explanation connecting earnings to a specific payment.
Maintain separate records for the affiliate identity, commission allocation, payout instruction, and provider status. Link them through stable identifiers. Display a last-updated timestamp so a delayed provider response does not masquerade as current information.
Hypothetical example: An affiliate has approved commissions but changes their receiving account before the next payment run. The portal should retain the approved earnings, show the destination change as awaiting verification, and explain whether the scheduled payout is paused. It should not reset the earnings balance or silently send funds to the new account.
Before launching an account dashboard, check that it can:
- Explain each balance without adding overlapping categories together.
- Show the reason for a hold and the party responsible for resolving it.
- Preserve the destination used for each historical payout.
- Separate estimated arrival from confirmed beneficiary credit.
- Record adjustments and returns without erasing the original transaction.
- Provide a downloadable statement with commissions, deductions, conversion details, and payout references.
Turn account visibility into fewer payout questions
An affiliate should be able to answer three questions from their account: what am I owed, what is preventing release, and where is the payment now?
Finance teams should audit those answers across their main receiving countries and payment methods before adding more dashboard features. If the underlying payment operation cannot supply them consistently, explore Payouts.com’s affiliate payout solution as part of connecting global money movement and financial records. The goal is a clear account history backed by payment evidence—not simply a reassuring status label.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
32 commentsRelated resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
Multi Currency Payouts: A Failed-Payment Recovery Guide
A returned cross-border payment is not simply the original transaction in reverse. Learn how to preserve the recipient’s currency entitlement, manage FX differences, and retry payments without creating duplicates.
AdSense Minimum Payout: Thresholds, Timing, and Cash Planning
The standard AdSense payout threshold is $100 for USD payments accounts, but reaching it does not mean immediate payment. Learn how account currency, finalized earnings, holds, and bank processing determine when cash arrives.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The point about collecting fields required by the actual route versus a generic international bank form is harder to implement than it sounds—we're wrestling with this now because our third-party payout provider still asks for SWIFT codes in domestic ACH markets, and affiliates paste routing numbers into the wrong field, then the payout fails and they assume we messed up their payment.
We hit the same thing with our provider. The workaround was adding frontend validation that hides the SWIFT field entirely when the selected country maps to a domestic rail in our routing table, but that meant maintaining that table ourselves instead of relying on the provider's form spec.
The part about distinguishing 'commission approval' from 'payment eligibility' is critical and often conflated in dashboards. We expose seven different blockers now—threshold, hold, missing tax form, unsupported destination, scheduled date not reached, currency mismatch, and manual review flag—and affiliate confusion dropped significantly once we stopped hiding these behind a single 'unavailable' state.
We track six of those seven but just rolled the currency mismatch into unsupported destination since it's the same remediation flow on our side. Curious whether splitting them actually improved affiliate completion rate or just made the dashboard noisier?
We went through a similar exercise and ended up at nine blockers once we added 'beneficiary account closed' and 'duplicate destination flagged'. The challenge is that some combinations can occur together, so we had to build a priority display logic to surface the one the affiliate can actually fix first.
The section on cross-border statement design is spot-on. We had affiliates open support tickets every month asking why the amount deposited didn't match the dashboard number, and it turned out we were showing gross commission but not itemizing withholding separately from FX conversion. Once we broke those out as discrete line items the ticket volume dropped by about half.
We took the same approach and extended it to show the withholding calculation per jurisdiction inline rather than just the final net amount. Cut tickets by about 60% but now the UI is a lot heavier for affiliates who don't need the detail.
We did the same breakdown and added a separate line for provider fees, which helped but then exposed another issue—affiliates assumed the FX rate we displayed was the one they'd see at their receiving bank, which wasn't always true if the beneficiary bank applied its own conversion. Ended up adding a footnote clarifying where our responsibility for the rate ended.
The threshold-per-method and threshold-per-currency distinction is something we're dealing with right now. Our dashboard shows one global balance but the actual payout logic applies separate minimums for PayPal USD, bank transfer EUR, etc. Affiliates keep hitting 'withdraw' and getting confused why it's blocked—this article nails the recommendation to surface the applicable policy inline.
We had the same problem and solved it by conditionally showing thresholds. If an affiliate has multiple methods configured, we display each one with its specific minimum and current eligible amount before they pick which method to use. Cuts down the failed withdrawal attempts significantly.
We ended up splitting the balance display into separate cards per method-currency pair and hiding pairs that don't meet threshold. It clutters the UI a bit but cut support tickets by maybe half.
The recommendation to collect fields 'required by the actual route rather than presenting one generic international bank form' is harder than it sounds when you support 40+ countries and affiliates can change their destination mid-month. We're still deciding whether to force re-verification on every method change or accept higher failure rates.
We went the other direction—locked the destination at the point the commission is approved rather than at payout submission. Affiliates can update for future cycles but not for funds already in a payable state. Cuts down on the routing logic branching considerably.
We snapshot the destination at the point the payout is batched rather than when it's approved. Lets affiliates update their details for future runs without invalidating in-flight payments, and we only verify once per destination-method combination rather than on every change.
The 'payment method and receiving account must match' section is understated—we've seen affiliates select PayPal as the method but then provide bank details in notes, or vice versa, and it creates a mess downstream. The recommendation to collect fields based on the actual route rather than a generic international form is spot on, but enforcing that at the UI level without frustrating users who don't understand why they're being asked for different information than last time is harder than it sounds.
We took a similar approach—killed the notes field and made the method selection actually control which form fields appear. The bigger problem was explaining to affiliates why we couldn't just 'figure it out' when they mixed inputs. Turns out no amount of error messaging beats not giving them the rope in the first place.
We solved this by disabling the free-text notes field entirely during payout setup and forcing method selection to drive which form fields appear. If they pick PayPal, they only see the PayPal email input. Sounds rigid but it cut our rework volume by about 60%.
The distinction between 'approved commission' and 'payable balance' feels obvious when you write it out like this, but we still get support tickets every week from affiliates who see a number on their dashboard and expect to withdraw it immediately. The real challenge is surfacing the blocker—threshold, hold, incomplete tax form—in a way that doesn't require them to dig through three different settings pages.
We started appending the specific blocker reason directly to the balance label itself—'Approved: $450 (releases March 15)' or 'Approved: $87 (minimum $100 for bank transfer)'. Reduced those tickets by about half, though you still get people who don't read anything.
We took a similar route but also added a progress indicator showing how close they are to threshold when that's the blocker. Reduced repeat inquiries by about half, but we still get confusion when someone has multiple pending periods stacked up and doesn't understand why only one tranche is being released.
The recommendation to show conversion rate binding separately from the execution is good, but in practice we found that affiliates don't understand 'indicative' vs 'fixed' terminology—we switched to 'estimated rate, final rate determined when payout is processed' and it cut support volume by about half on FX questions.
We landed on the same phrasing. The word 'indicative' made affiliates think the rate was a suggestion they could negotiate. Plain language around timing solved it completely.
We did something similar but also surfaced the processing time range alongside the rate estimate. Turns out affiliates were conflating 'when the rate locks' with 'when I receive the money' and that was driving a different category of support ticket entirely.
the distinction between 'processing' and 'sent' vs actual beneficiary credit is real. we had affiliates screenshot 'completed' status from our dashboard while their bank hadn't received anything yet because the correspondent chain took 4 days. lesson learned: don't call it complete until you have confirmation from the rails.
We ended up splitting the status into two fields: internal processing state and beneficiary confirmation. Helped with support tickets but meant reworking the entire payment dashboard UI, which was not a small lift.
We ended up labeling it 'submitted to provider' instead of completed and only updating to 'delivered' after we get a positive callback. Still not perfect since some banks don't confirm the actual credit, but at least the affiliates stopped assuming their money was sitting in their account when it was still in flight.
The point about commission currency vs deposit currency is something we got wrong for two years. We showed affiliates one number in the portal and a totally different figure landed in their account, then spent hours every month explaining FX spreads and intermediary fees over email. Now we surface the conversion rate and all deductions before release and support tickets dropped by half.
We had the exact same issue. The fix for us was showing a range estimate before the payout and only marking it complete once we had confirmation from the provider that funds were credited. Still not perfect when correspondent banks take cuts, but at least affiliates stopped assuming the portal number was what they'd see in their account.
We hit the same wall. The breakthrough was moving FX disclosure upstream to the point where they choose payout method and currency, not buried in a statement three days later. Cut support tickets by about 60%.
Would love to see more discussion of the verification workflow. We're still treating KYC as a one-time gate but regulators and payment providers keep asking for refreshed documents, especially when affiliates change payout methods or cross certain thresholds. How are other teams surfacing those requests without making it feel like constant re-onboarding?
We built status banners that appear in the account when a refresh is needed, but the challenge is timing the ask. If you request documents too early in a threshold cycle, affiliates see it as friction. Too late and you delay their first big payout. We're testing a 30-day pre-threshold nudge now.
Same problem. We built a scheduled refresh queue tied to the provider's webhook events, but the harder part is explaining to affiliates why they need to re-upload a passport when nothing else changed. The article is right that this shouldn't be one checkbox, but most dashboards still show verification as binary green/red.