

OnlyFans Creator Payment Methods: Choosing a Withdrawal Route
OnlyFans withdrawal options depend on the creator’s country and account. Learn how to compare bank transfers and wallets by eligibility, total cost, and time to usable money.
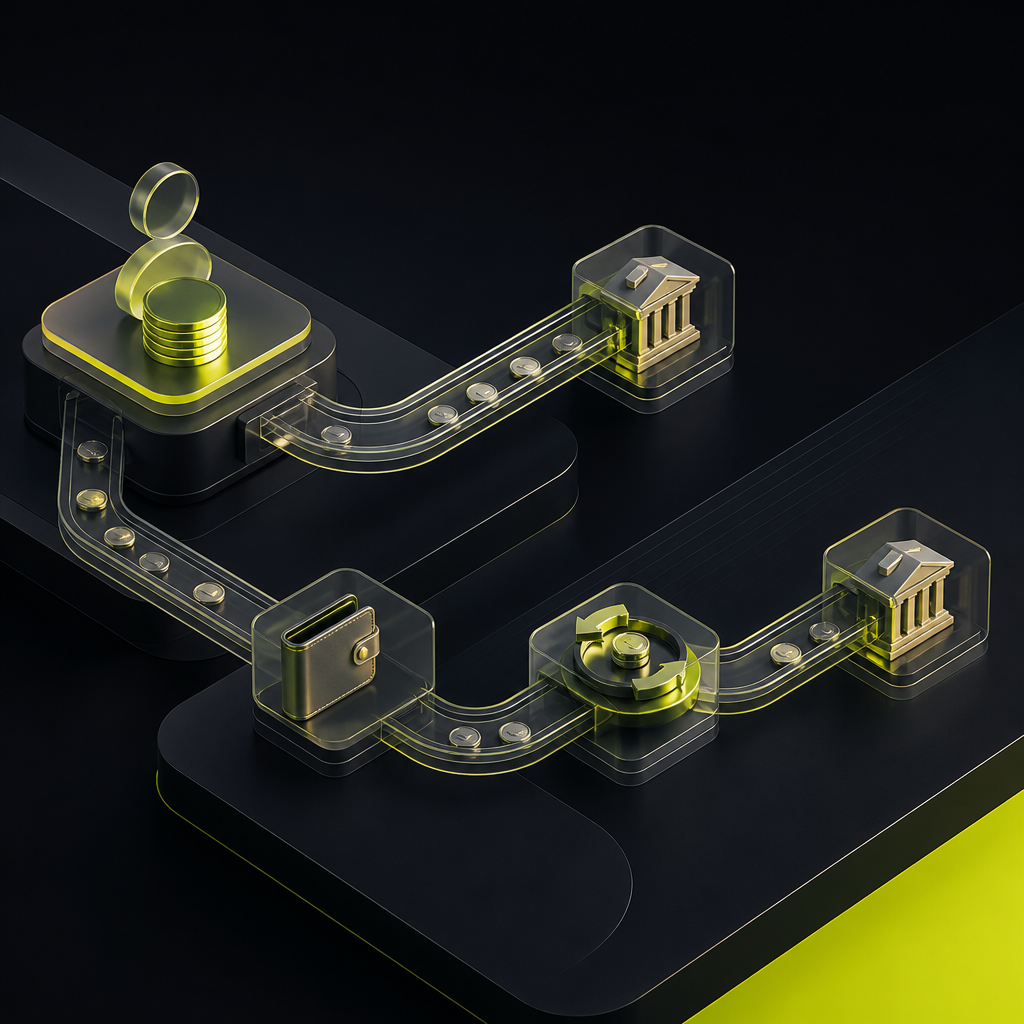
OnlyFans creator payment methods generally include bank transfers and, where available, third-party payout wallets. Secondary guides describe US ACH/direct deposit, European bank transfers, international wires, and wallet options such as Paxum. The options displayed in the creator’s account—not a global list in a blog—determine what that creator can actually use.
These are withdrawals of creator earnings, not the methods fans use to buy subscriptions. PayPal and native cryptocurrency withdrawals should not be treated as supported options based on the supplied research.
For creators, the decision is which available route delivers usable money at an acceptable cost. For product and operations teams studying OnlyFans, the lesson is equally practical: a payout method is not complete until the recipient understands eligibility, deductions, timing, and what happens if delivery fails.
Evidence scope: the research reviewed on October 29, 2026 consists of secondary sources, not authenticated OnlyFans Help Center documentation. Country availability, minimums, fees, and schedules require confirmation in the account and applicable provider terms.
Which withdrawal methods are available?
PaymentCloud’s OnlyFans payment guide describes bank-based creator withdrawals and states that PayPal and native crypto payouts are not supported. Other secondary guides describe additional wallet options, but their availability should not be assumed across countries.
The table below is a decision framework, not a verified account-specific menu. “Best for” and comments are editorial assessments of the payment mechanisms, not provider ratings.
| Reported route | Availability to verify | Best for | Comments |
|---|---|---|---|
| ACH/direct bank deposit | Eligible US account and bank details | Domestic bank receipt | Check account type and receiving fees |
| European bank transfer | Country, currency, and supported rail | Compatible local bank accounts | SEPA and UK Faster Payments differ |
| International wire | Supported destination and currency | Recipients without a suitable local route | Check intermediary fees and minimums |
| Paxum wallet | Account eligibility and local cash-out | Creators with a viable wallet-to-bank route | Wallet arrival is not bank arrival |
| Skrill or Cosmo Payment | Whether the option appears in the account | Conditional alternatives | Verify fees and withdrawal restrictions |
Bank transfers: distinguish the rail from the label
“Bank transfer” does not identify a single payment system. ACH is a US clearing network; SEPA credit transfers move euros within the SEPA area; UK Faster Payments is a separate domestic system. A dashboard label alone may not tell the recipient which rail or conversion process is involved.
Confirm the destination currency, required bank identifiers, and receiving account compatibility. Do not infer that every European creator receives SEPA or that every non-US creator must use an international wire.
International wires can involve intermediary banks and receiving-bank deductions. That makes them worth evaluating carefully for smaller withdrawals: even an otherwise workable route may leave the creator with an unattractive net amount.
Wallets: evaluate both legs of the withdrawal
OnlyMonster’s payout overview discusses bank and wallet withdrawal options, including regional availability and fee considerations. Treat those descriptions as a shortlist to verify, not a promise that every named provider appears in every account.
A wallet creates two separate transfers: OnlyFans to the wallet, then the wallet to a bank or another supported spending destination. Each leg can have its own verification requirements, fees, limits, and processing time.
Before selecting a wallet, establish how the creator will use or withdraw the balance locally. A fast wallet credit is not helpful if the second leg is expensive, unavailable, or subject to additional review.
PayPal and crypto: do not confuse downstream transfers with native payouts
An agency or intermediary may advertise paying creators in cryptocurrency after receiving funds through another channel. That does not establish that OnlyFans itself offers cryptocurrency withdrawals.
Separate the platform’s payout instruction from any later conversion or agency distribution. The latter introduces another counterparty, another fee schedule, and potentially different contractual and compliance obligations. Do not route earnings through someone else’s account to bypass eligibility or provider restrictions.
Why a withdrawal method does not determine the full timeline
Time to usable money contains several distinct stages:
- Earnings release: a transaction moves from pending to withdrawable balance.
- Withdrawal eligibility: the available balance meets the applicable minimum and account requirements.
- Payout initiation: a manual request or an available automatic schedule triggers the payment.
- Delivery: the bank or wallet processes and credits the transfer.
- Cash-out, if needed: a wallet balance reaches the creator’s final destination.
Aruna Talent’s payout guide describes a roughly seven-day pending period before earnings become withdrawable, followed by separate transfer processing. That is a secondary-source description, not a universal account-level guarantee. The supplied research also reports longer initial holds in certain countries with higher reversal risk.
Changing withdrawal methods generally addresses the delivery stage, not the earnings-release stage. A faster bank rail cannot make a still-pending balance withdrawable.
Likewise, automatic payout frequency and bank processing speed are different settings. Confirm which schedules are actually available rather than assuming every creator can select daily, weekly, or monthly withdrawals. Platform teams can use the same distinction when designing reliable payout estimates.
Compare net proceeds, not just the advertised fee
Keep the platform’s revenue share separate from withdrawal costs. When comparing payout methods, start with the same withdrawable balance and ask what reaches the same final destination.
Net usable proceeds = requested withdrawal − transfer charges − intermediary or receiving charges − wallet cash-out charges − currency-conversion costs.
Not every route incurs every deduction. Some costs appear as explicit charges; others are embedded in an exchange rate. Compare quotes in the same destination currency and at comparable times.
Minimums also matter. The supplied secondary sources disagree about current withdrawal thresholds and wire minimums. A universal dollar figure would therefore be misleading. Check the minimum attached to the selected method inside the account before planning cash flow.
Hypothetical example: a cheaper first leg can cost more overall
A creator sees both a bank transfer and a wallet option. The wallet advertises no charge for receiving the platform payout, but moving that balance to the creator’s local bank requires conversion and a withdrawal charge. The bank option has an upfront fee but delivers directly in the required currency.
The creator should compare the final bank credit and total elapsed time—not declare the wallet cheaper because its first leg is free. If either quote omits conversion or receiving costs, the comparison remains incomplete.
A practical withdrawal-selection checklist
- Inspect the actual account menu. Record the available methods, currencies, minimums, and displayed processing estimates.
- Confirm recipient compatibility. Check beneficiary details, supported account types, and applicable rules for receiving creator earnings.
- Identify the final destination. Decide whether success means wallet credit or spendable money in a local bank account.
- Price the complete journey. Include conversion, intermediary deductions, and wallet cash-out charges where applicable.
- Separate the clocks. Record the pending-balance release, withdrawal request, dispatch, and expected receipt separately.
- Keep payment evidence. Retain the request amount, currency, timestamp, status, and transaction reference without sharing sensitive banking credentials.
- Escalate the correct stage. A pending balance, a rejected withdrawal, and a dispatched-but-unreceived transfer require different investigations.
When a payment is missing, ask whether it was actually dispatched before submitting another request. If the platform reports a return or rejection, obtain the reason and resolve it rather than repeatedly changing destinations.
What platform teams should take from this comparison
The strongest lesson is not to offer the longest menu. It is to make every displayed option accurate for that recipient and understandable through to final receipt.
A useful method-selection screen should show eligibility, destination currency, minimum withdrawal, known fees, conversion treatment, and an estimate measured from payout initiation. Unknown receiving-bank charges should be identified as unknown—not silently treated as zero.
Operations teams should also distinguish “sent to wallet” from “received at bank” and assign responsibility for investigating each stage. For broader infrastructure decisions, evaluate payout providers by corridor rather than relying on aggregate country coverage.
Choose the route that completes the journey
The best OnlyFans withdrawal method is the available, permitted route that delivers the required currency with acceptable total cost and predictable access to funds. Verify it in the creator’s account, follow the money through every intermediary, and avoid treating secondary fee tables as binding terms.
For teams building their own creator marketplace, explore Payouts.com’s creator-economy payout capabilities against a documented set of recipient countries, currencies, and delivery requirements. This is an infrastructure evaluation for your platform—not a way to change OnlyFans’ withdrawal options or release rules.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
How to Evaluate a Mass Payout Platform: Test Corridors, Not Country Counts
Country coverage is not proof that a platform can deliver your payment run. Use a corridor-level acceptance test to evaluate costs, recipient requirements, delivery evidence, and failure handling.
Payout Settlement Times by Country: Build Reliable Payment ETAs
An instant domestic rail does not make an international payout instant. Use this country reference and operating framework to set payment ETAs that account for funding, calendars, and recipient-bank availability.
Scoopz Creator Fund: Eligibility, Qualified Views, and Payouts
Scoopz pays eligible US creators for qualified video views, but public view counts do not translate directly into cash. Here is how eligibility, monthly rates, and payout readiness fit together.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.