

PayPal Payouts: Fees, Funding, and Cross-Border Readiness
PayPal Payouts can simplify mass payments to wallet users, but wallet delivery is not the same as local bank settlement. Here is what finance teams should verify before building it into an international payment run.
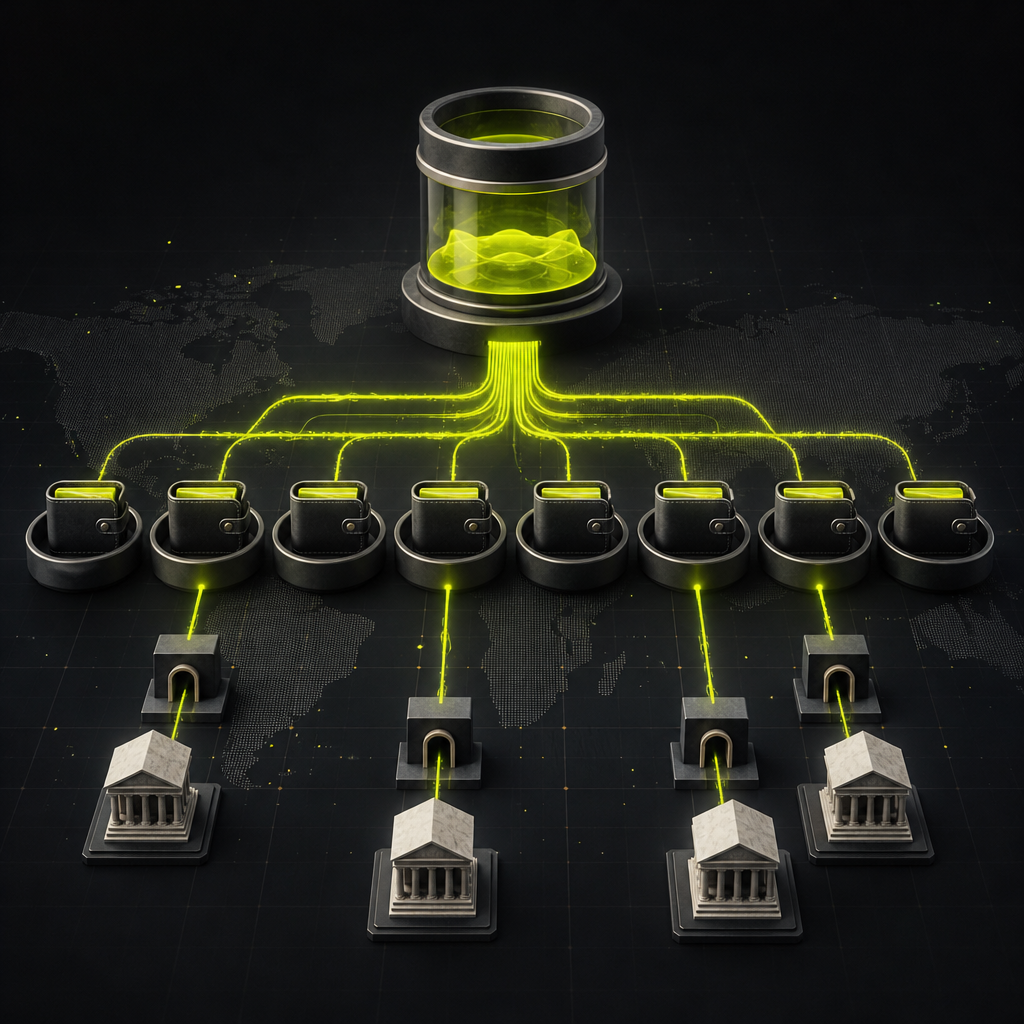
PayPal Payouts lets eligible businesses send mass payments to PayPal accounts and, in the United States, Venmo accounts. It can fit contractor, affiliate, and seller payments when recipients want wallet delivery. For international payment operations, the key constraints are account approval, prefunding, country-specific currency rules, and what recipients must do to turn wallet balances into usable local cash.
Treat PayPal Payouts as a delivery method, not as the entire payables process. Invoice approval, recipient verification, tax documentation, funding, and reconciliation still need clear owners. The practical question is whether its wallet-based payment journey meets your contractual payment obligations.
What PayPal Payouts does—and which product you need
PayPal distinguishes standard Payouts from Enterprise Payouts, powered by Hyperwallet. Standard Payouts focuses on PayPal and Venmo delivery. Enterprise Payouts offers a broader set of methods, including bank accounts and other locally available options, with custom pricing. These are not interchangeable tiers of the same API integration; evaluate their onboarding, coverage, and commercial terms separately using PayPal’s payout solution overview.
Standard Payouts is a sensible candidate when recipients already use supported wallets and accept the payout currency. If a supplier requires a specific amount to arrive in a local bank account, wallet delivery introduces another step that needs explicit agreement.
Likewise, do not assume a payout product automatically provides marketplace split-payment accounting, payroll compliance, or permission to hold customer funds. Those requirements depend on your business model and legal arrangements.
How the payment run works
Obtain access before committing to a launch date
A PayPal Business account alone does not guarantee Payouts access. The feature requires eligibility and approval, and API access involves a separate application process. Confirm production access for the sending entity before promising recipients a new payment method.
For an API implementation, separate the approved payable from the payment request. Your internal record should identify the recipient, obligation, amount, currency, payment method, and approval evidence. The API request executes that decision; it should not create the underlying entitlement.
Prefund the balance, including fees
Standard Payouts is funded from your PayPal balance. That balance must cover the submitted payments plus applicable fees; do not design the run around a bank pull at submission. PayPal’s Payouts developer overview describes the funding and operating requirements.
Build the funding decision around available funds, not cash expected to arrive. Allow for other activity consuming the balance between approval and submission. Assign an owner to fund the account, verify availability, and stop release if the balance is insufficient.
This is a treasury dependency, not merely an integration setting. The same distinction between recorded cash and deployable cash underpins real-time treasury planning.
Track each payment, not just the batch
A batch response is not proof that every recipient has received money. Keep the provider’s batch and item references alongside your own payable identifiers, and reconcile each item to its eventual outcome.
After a timeout, investigate the original submission before creating a replacement. Use the API’s documented duplicate-prevention behavior and your own uniqueness controls. A retry must resolve uncertainty, not create another payment obligation.
PayPal Payouts fees: separate delivery from conversion
The US PayPal business fee schedule lists a domestic Payouts API fee of $0.25 USD per payment. It also lists international PayPal Payouts pricing of 2%, subject to a maximum fee of $20.00 USD. These are US merchant schedule references, not worldwide prices: confirm the applicable submission method, currency, account terms, and schedule before budgeting.
Fee information in the supplied research was collected on November 19, 2026. PayPal can revise its schedules, and senders in other jurisdictions may face different charges.
The base payout fee is only one part of the economic cost. Build a cost worksheet that separates:
- Sender delivery fee: the charge for issuing the payout.
- Sender-side conversion: any currency exchange required before or during delivery.
- Recipient-side conversion: exchange needed to obtain the recipient’s preferred spending currency.
- Withdrawal: any applicable charge for the recipient’s chosen withdrawal method.
- Operational work: funding, support, exception handling, and reconciliation.
Do not apply a generic FX spread to every country. Establish which party converts, which rate applies, and whether the contract promises a gross wallet amount or a net local-currency amount. A fee-free receipt does not necessarily mean cost-free access to bank cash.
Country coverage is a payment-path question
PayPal’s marketing and developer materials report different market and currency totals. Those figures can reflect different products, regions, or supported capabilities. Rather than treating a headline total as a launch checklist, use the country and supported-feature documentation to validate the sender, recipient, currency, and withdrawal path.
For example, Brazilian real has in-country account restrictions. Malaysian ringgit also has restrictions: Malaysian users can send MYR to other Malaysian users, but payouts requiring conversion to or from MYR are restricted. Venmo payout delivery is US-only. These rules make a country name insufficient evidence that your intended payment will work.
| Readiness check | Evidence to collect | Release blocker |
|---|---|---|
| Sending entity | Production Payouts approval | Access not enabled |
| Recipient destination | Verified payout identifier and country | Unsupported or unverified destination |
| Payment currency | Supported country-currency combination | Restricted conversion path |
| Funding | Available balance covering payments and fees | Funding shortfall |
| Recipient access | Accepted wallet and withdrawal expectations | Bank-credit promise cannot be met |
| Reconciliation | Payable-to-payment reference mapping | Outcome cannot be traced |
Collect the payout identifier supported by your chosen method, but retain a separate internal recipient ID. An email address is a delivery instruction, not sufficient proof of legal identity or ownership of the underlying payable. Verify changes to payout details through a trusted workflow.
Define what “paid” means before promising speed
Wallet credit and bank availability are different milestones. Even when delivery to a wallet is fast, a recipient may still need to complete account steps, accept funds, convert currency, or withdraw to a bank.
Your recipient communications should distinguish submission, wallet receipt, and any subsequent withdrawal. Do not advertise an instant local-bank payment merely because the wallet leg can complete quickly.
Hypothetical example: a contractor invoices in local currency but agrees to receive a foreign-currency PayPal balance. Your system marks the payout successful. The contractor later converts and withdraws, receiving less local currency than expected. The delivery can be technically successful while the commercial obligation remains disputed.
Prevent that dispute by recording the agreed payout currency and who bears conversion costs before release. If the contract requires full bank receipt, evaluate a bank route instead. Our guide to paying international supplier invoices in full explains that distinction.
A launch checklist for finance and operations
- Confirm product and approval. Record whether you are implementing standard Payouts or Enterprise Payouts and which entity is authorized to send.
- Validate payment paths. Check destination countries, currencies, account requirements, and current per-payment limits.
- Agree recipient terms. Document wallet acceptance, payout currency, conversion responsibility, and what constitutes payment completion.
- Build the funding control. Verify available balance and fees immediately before release.
- Protect recipient changes. Require verification and appropriate approval before changing payment instructions.
- Test exceptions. Cover invalid destinations, insufficient funds, unclaimed payments, timeouts, and repeated submissions.
- Reconcile outcomes. Link each item to its payable, fee, status, and any return. Do not treat returned funds as automatically canceling the underlying liability.
- Define fallback rules. Confirm the original payment cannot still complete before paying through another method.
Use PayPal where it fits the recipient journey
PayPal Payouts can be effective when recipients prefer supported wallets and your operation can manage prefunding and item-level reconciliation. It is less straightforward when payment terms require exact local-bank receipt or recipients face inconvenient conversion and withdrawal steps.
Start with representative payment paths, not the largest possible batch. Document funding requirements, total costs, recipient expectations, and exception ownership before expanding.
If your recipient base needs wallets alongside bank transfers and other rails, explore Payouts.com’s payout automation as part of a broader payment operation. The objective is a consistent approval and reconciliation process across methods—not forcing every recipient through the same one.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
Real-Time Treasury Explained: How Finance Teams Are Rethinking Liquidity in Motion
Real-time treasury moves beyond batch reporting and end-of-day snapshots, giving CFOs and controllers a live, actionable picture of every dollar in motion. This guide explains the mechanics, the operational payoff, and what it takes to build it.
International Supplier Payments: Pay Invoices in Full
A successful transfer does not always settle a supplier invoice. Learn how to align currencies, fees, payment timing, and remittance data so suppliers receive and recognize what they are owed.
Affiliate Account Meaning: The Profile Behind Commission Payments
An affiliate account connects a partner’s referrals to commission records and payment settings. It is not automatically a bank account, a withdrawable balance, or proof that payment is due.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.