

Ripple RLUSD Stablecoin AI Payments: From API Call to Ledger
Ripple’s RLUSD tooling gives AI agents a path to pay for digital services. Finance teams still need to connect each payment to purchasing authority, service delivery, and an accountable ledger entry.
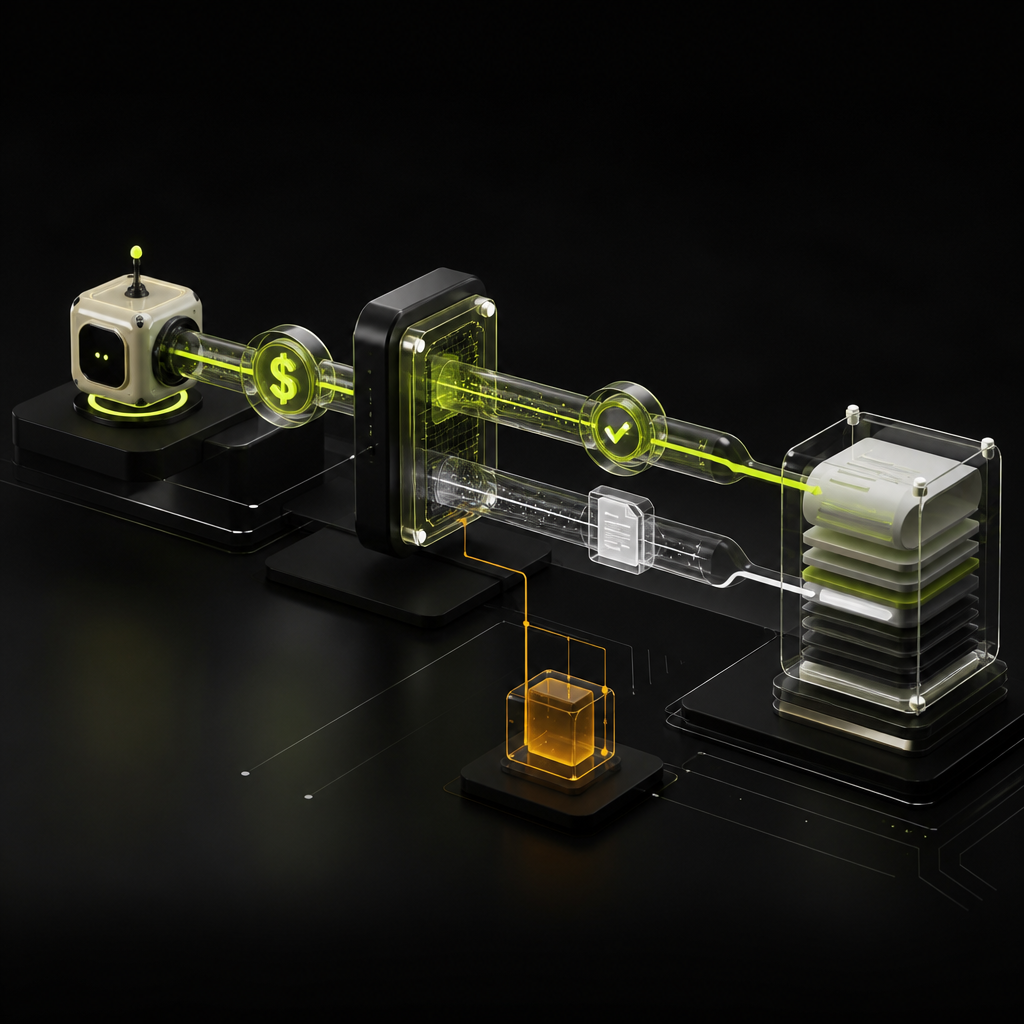
Ripple’s RLUSD stablecoin can serve as a dollar-denominated settlement asset for AI agents buying digital services through supported payment integrations. Ripple’s XRPL AI Starter Kit connects agent tooling with XRP Ledger payments, including x402 support for XRP and RLUSD. It does not, by itself, establish purchasing authority, verify that a service was delivered, or complete your accounting.
For CFOs evaluating Ripple RLUSD stablecoin AI payments, the useful question is therefore not simply whether software can send money. It is whether a paid API call can become a controlled, explainable business expense without someone approving every request.
What RLUSD contributes—and what it does not
RLUSD is Ripple’s US-dollar-pegged stablecoin. It is distinct from XRP, the XRP Ledger’s native asset. An agent can use a stablecoin to denominate a purchase in dollars rather than taking the same price exposure as a volatile settlement asset. Dollar denomination does not eliminate issuer, custody, liquidity, or redemption risk.
Ripple’s XRPL AI Starter Kit announcement describes tooling for wallet creation, balance checks, payments, and x402-based purchases using XRP and RLUSD. This makes paid data access, model inference, and other machine-consumed services plausible starting points.
Keep the components separate:
- RLUSD: the asset used to pay.
- XRP Ledger: the network recording the transfer in this implementation.
- x402: a web-payment pattern through which a service requests payment and a client supplies payment evidence.
- Agent tooling: software that helps an AI system discover and invoke these capabilities.
- Enterprise controls: the independent rules determining whether that purchase is allowed.
These layers are not interchangeable. A valid blockchain transfer can still be an unauthorized purchase, a duplicate expense, or payment for an unusable response.
How an RLUSD-paid API request should work
The XRP Ledger documentation on agentic transactions describes the ledger as infrastructure for autonomous payments. Finance should surround that execution capability with a controlled purchase lifecycle.
- Request the service. An agent identifies a needed resource, such as a data lookup from an approved provider.
- Receive payment requirements. In an x402-style flow, the service communicates its payment requirement. The implementation should bind the quoted price to the requested resource, recipient, asset, network, and expiry.
- Validate outside the model. A policy service checks the vendor, permitted service, remaining budget, and whether this purchase has already been authorized or paid.
- Reserve the budget. Reserve the purchase amount before execution so parallel agent tasks cannot each spend the same available balance.
- Authorize and submit. A controlled signing service executes only the validated payment instruction. Private keys should not enter the model’s prompt or conversational memory.
- Confirm payment and delivery separately. Record the validated transfer, then determine whether the purchased service actually arrived and met its acceptance conditions.
- Reconcile the expense. Connect the purchase authorization, payment, service receipt, and accounting record.
The distinction between an agent asking to buy and a separate system allowing the purchase is essential. For the underlying identity and funding model, see how AI agents get wallets and spend limits.
The finance gap: settlement is not service acceptance
Traditional AP often begins with an invoice and ends with payment. A machine purchase may reverse that order: payment happens first, and useful output arrives afterward. Finance therefore needs evidence of what was purchased, not just evidence that tokens moved.
The following is a recommended control model, not a claim that the starter kit supplies every component.
| Stage | Evidence to retain | Control owner | Exception treatment |
|---|---|---|---|
| Purchase requested | Task, service, quote, vendor | Agent and procurement policy | Reject unapproved services |
| Purchase authorized | Mandate, policy version, budget reservation | Independent policy service | Escalate policy exceptions |
| Payment submitted | Transaction identifier, exact instruction | Signing and payment service | Investigate uncertain status |
| Payment validated | Network, asset, recipient, delivered amount | Payment reconciliation | Do not infer service delivery |
| Service accepted | Response reference, acceptance result | Consuming application | Open fulfillment exception |
| Expense reconciled | Ledger reference, fee record, tax evidence | Finance | Resolve unmatched records |
Use a durable purchase identifier across these stages. A transaction hash identifies a transfer; it does not explain the business purpose or prove the same service was not purchased through another route.
Where the vendor also issues a consolidated invoice, reconcile it against already-paid requests before release. Otherwise, the organization can pay at consumption and again through its ordinary AP automation workflow.
Hypothetical example: payment succeeds, the API times out
An AP agent buys an approved company-data lookup to help validate an invoice. The RLUSD transfer is validated, but the service response times out.
An unsafe implementation treats the timeout as a failed purchase and sends another payment. A controlled implementation retains the original purchase identifier, checks payment status, and asks the provider to retrieve or fulfill the original request using its payment evidence. If delivery remains unresolved, it opens an exception rather than silently paying again.
The agent may automatically match the eventual response to the invoice under an approved rule. It should not independently decide to purchase a more expensive substitute, change the vendor’s payment destination, or waive a mismatch merely to finish its task.
Where RLUSD-specific diligence matters
Asset identity and wallet readiness
Do not approve an asset solely because a wallet displays the ticker “RLUSD.” Validate the network and issuer identifier against an approved configuration. For an XRPL implementation, assess the required trust-line setup, account reserves, and XRP needed for transaction fees. An RLUSD balance alone does not establish payment readiness.
Also confirm whether the vendor receives RLUSD or expects conversion into another asset. Conversion introduces liquidity and execution considerations; exclude it from an initial pilot unless it is part of the approved business case.
Feature availability is not the same as an announcement
September 2026 reporting on the expanded starter kit described Machine Payments Protocol support and payment-channel functionality, while noting that stablecoin payment sessions depended on a proposed XRPL upgrade that was not yet live at that time.
That distinction matters for recurring service consumption. Before committing to a design, verify the current network amendment status, supported asset, software version, and whether a demonstrated feature works on the intended production network. A working XRP flow is not proof that the equivalent RLUSD session is available.
Dollar settlement is not universal business acceptance
Check whether the provider accepts RLUSD, can refund it, and supplies the commercial and tax records your entity needs. Legal review should address the specific jurisdiction, custody arrangement, sanctions obligations, and redemption route. Do not treat regulatory status in one market as permission for every entity or activity.
Compare the complete cost with a prepaid API balance or invoiced vendor account: funding, network fees, custody, conversion, reconciliation, and exception handling. Low network fees alone do not establish a cheaper purchasing process.
A practical pilot acceptance checklist
Start with an approved digital service whose output can be checked automatically. Keep new vendor onboarding, payment-destination changes, and budget increases under human approval.
- Define a narrow mandate. Specify the legal entity, agent, vendor, service, network, asset, expiry, and cumulative spending authority.
- Separate suggestions from permissions. Let the model select within approved options; enforce payment rules in deterministic code.
- Test concurrent spending. Verify that parallel requests cannot exceed the shared budget through simultaneous approvals.
- Test the ambiguous middle. Simulate payment submission without a response, validated payment without delivery, and delivery without a matching receipt.
- Prevent duplicate release. Carry the purchase identifier through retries, provider callbacks, and later invoices.
- Validate accounting treatment. Agree how finance records funding, token holdings, fees, consumption, refunds, and unresolved purchases.
- Prove shutdown behavior. Disabling an agent should stop new authorizations while preserving reconciliation of existing transfers.
- Measure business completion. Track accepted services, duplicate purchases, unmatched payments, total cost, and exception workload—not just transaction counts.
Use configurable approval policies to distinguish routine execution from changes in authority. A human should approve an expanded mandate; the agent should not reinterpret its original mandate to cover a new purchase category.
Make the ledger connection the acceptance test
RLUSD gives agentic payments a dollar-denominated settlement option. The more demanding enterprise requirement is proving that each transfer purchased an authorized service and reached the correct financial record.
Payouts.com’s AI agents with identities, wallets, and spend limits reflect that broader operating model. Any RLUSD-specific integration should be verified separately rather than assumed.
The next step is a bounded pilot with one approved service and explicit acceptance criteria. Expand only when finance can explain what was authorized, what settled, what was delivered, and what remains unresolved.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
How AI Agents Get Wallets and Spend Limits: A Finance Leader's Guide
AI agents can now hold funds, initiate payments, and operate within defined spend limits — but what does that actually mean for financial controls? Here's how the plumbing works and what finance leaders need to think through before deploying autonomous money movement.
Billing Bee AI Invoice: Features, Pricing, and Control Gaps
BillingBee turns plain-language instructions into invoices and advertises automated collections. Here is how to evaluate its usefulness without confusing invoice generation with financial authority.
Template.net AI Invoice Generator: A Finance Team’s Guide
Template.net can help turn billing instructions into editable invoice drafts. Finance teams should evaluate the document workflow separately from accounting, approval, and payment authority.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.