

STC Pay International Transfer Fee: Rates and Total Cost
STC Pay’s Saudi international transfer fees depend on the destination and transfer route. Use the published charges as a starting point, then check VAT, the exchange rate, and the amount the recipient actually receives.
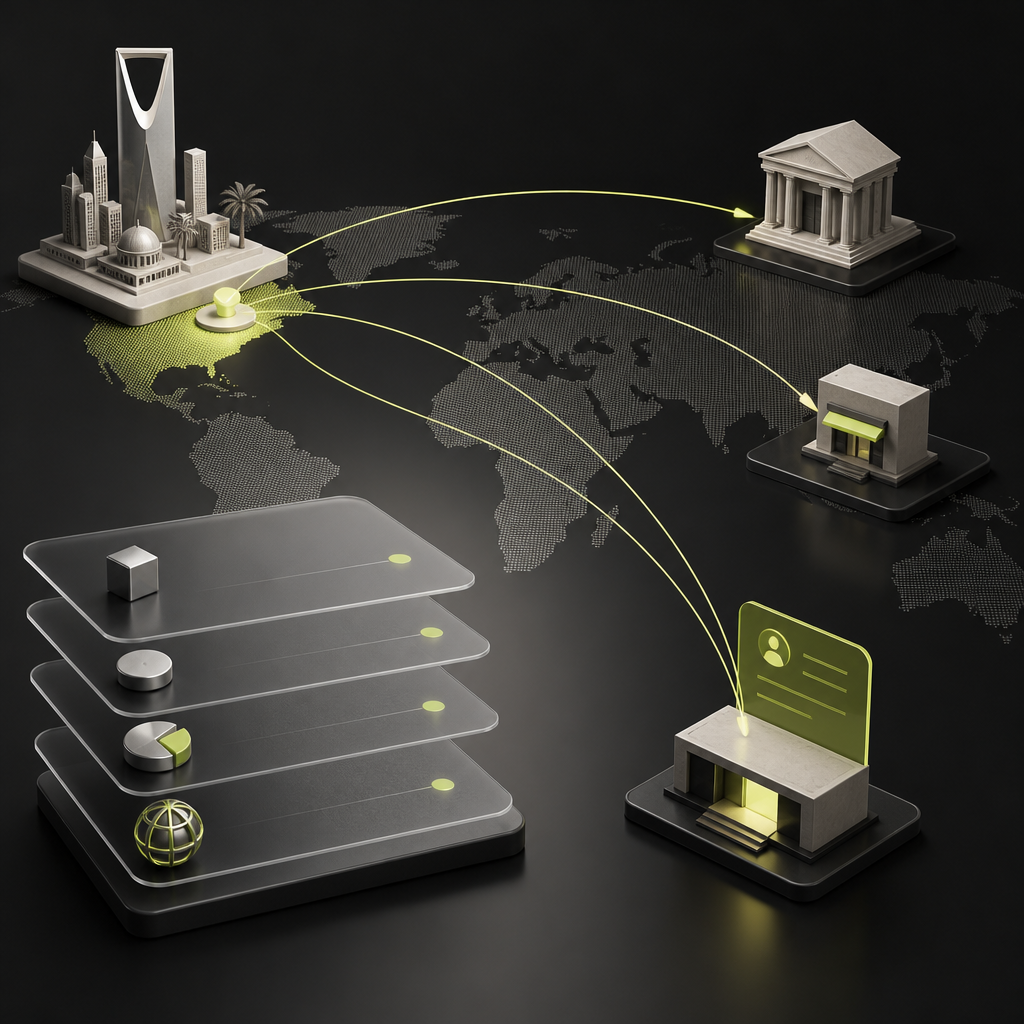
The stc pay international transfer fee for Saudi Arabia’s service, now under STC Bank, generally ranges from SAR 15 to SAR 25 before VAT for Western Union transfers, depending on the destination. Pakistan is an exception: the published transfer fee is zero for amounts of SAR 375 or more, and SAR 15 below that threshold. A separate transfer-to-a-bank-abroad route is listed at SAR 50 before VAT in STC Bank’s product and service fee schedule.
These are transfer charges, not an all-in price. Before confirming, check the selected route, applicable VAT, exchange rate, total account debit, and recipient amount. For finance teams benchmarking contractor or vendor payments, that final delivered amount matters more than the advertised fee alone.
Which STC Pay service does this fee schedule cover?
This guide covers transfers originating in Saudi Arabia. On January 28, 2025, SAMA announced that STC Bank had received no objection to commence banking operations, as reported by the Saudi Press Agency. People searching for the former stc pay wallet’s charges should therefore check STC Bank’s current schedule and the quote displayed for their account.
Do not apply Saudi pricing to Bahrain. The separate stc pay Bahrain fee schedule says international transfer charges are advertised by country in the app. Its fees and jurisdiction are distinct.
The Saudi figures below reflect the supplied research dated October 31, 2026. They are published reference prices, not a guarantee that every account, destination, or delivery method will receive the same quote.
STC Pay international transfer fees by destination
The following selected destinations use the Western Union pricing in STC Bank’s published schedule. All listed charges exclude VAT. The bank-abroad route appears separately because it should not be confused with a destination-specific Western Union charge.
| Destination or route | Published fee | Condition or pricing note |
|---|---|---|
| India, Bangladesh, Philippines | SAR 15 | Western Union route |
| Egypt, Indonesia, Nepal, Sri Lanka | SAR 15 | Western Union route |
| Afghanistan, Sudan, Vietnam, Yemen | SAR 15 | Western Union route |
| Pakistan: below SAR 375 | SAR 15 | Amount-dependent charge |
| Pakistan: SAR 375 or more | No transfer fee | FX still affects delivered value |
| Bahrain, China, Kuwait, Oman | SAR 20 | Western Union route |
| Ethiopia, Iraq, Jordan, Kenya | SAR 20 | Western Union route |
| Lebanon, Morocco, Palestinian Authority, Turkey | SAR 20 | Western Union route |
| Rest of world | SAR 25 | Schedule category; verify availability |
| Separate transfer to a bank abroad | SAR 50 | Different route; verify eligibility |
A bank-account destination does not, by itself, identify the pricing route. Check which transfer service the app has selected. Do not assume every payment delivered to a bank account incurs the separate SAR 50 charge, or that every destination qualifies for the lower Western Union fee.
Is sending money to Pakistan free?
The published Western Union transfer charge is waived when the amount is at least SAR 375. That is a waiver of the explicit transfer fee, not a promise of conversion at a wholesale exchange rate. Compare the Pakistani rupee amount the recipient will receive against the total Saudi riyal debit.
For business payments, do not change invoice amounts or combine unrelated beneficiaries merely to reach a pricing threshold. Preserve the approved payable and confirm that the account and service permit the intended commercial use.
Why the fee is not the total transfer cost
VAT changes the amount debited
STC Bank labels its published fees as exclusive of VAT. An app quote that includes tax can therefore show a higher charge without contradicting the base fee table. Reconcile the fee and tax separately rather than treating the difference as an unexplained surcharge.
For accounting, retain the transaction receipt and any available tax documentation. Do not assume a payment confirmation alone establishes whether tax is recoverable for your business.
The exchange rate changes the amount delivered
A provider’s customer exchange rate can differ from a contemporaneous reference rate. That difference affects recipient value even when the transfer fee is zero. There is no reliable basis here for assigning one universal STC Bank FX markup across all currencies and transfer amounts.
Use a matched comparison instead: same destination, currency, delivery method, and quote time. Comparing a cash-pickup quote with a bank-credit quote can obscure differences in both price and recipient convenience.
Potential deductions need their own check
For a bank-abroad transfer, ask whether intermediary or receiving-bank charges can reduce the credit. The published sending fee alone does not establish that the recipient will receive an invoice amount in full. Conversely, do not assume such deductions apply to every Western Union delivery option.
Our guide to reducing cross-border payment fees explains how to separate explicit charges, conversion costs, and operational expenses when comparing routes.
A better comparison: fix the recipient amount
Finance teams usually owe a specified amount, rather than an approximate foreign-currency equivalent of a Saudi riyal budget. For that use case, compare quotes on a fixed net recipient amount.
- Enter the amount owed in the recipient’s currency, where the service supports this.
- Record the total SAR debit, including the transfer charge and applicable tax.
- Confirm whether the displayed recipient amount is guaranteed or subject to deductions.
- Obtain another quote for the same recipient amount and delivery method at approximately the same time.
- Compare total debit, expected availability, and the evidence available to reconcile the payment.
If the service only accepts a sender amount, adjust the comparison carefully and record the resulting recipient amount. Do not compare identical send amounts while ignoring different fees debited on top.
A useful analytical formula is: effective SAR cost per unit delivered = total SAR debit ÷ net recipient currency received. Within the same currency and comparable delivery conditions, a lower result means a better delivered price. This avoids double-counting FX costs already reflected in the quote.
What finance teams should verify before using the service
A consumer remittance fee is a useful benchmark, but it is not evidence of suitability for paying more than a hundred vendors or contractors. The supplied fee schedule does not establish business-account eligibility, bulk payment functionality, approval workflows, or invoice-level reconciliation.
Before adopting the route, confirm:
- Permitted use: Does the account support your legal entity, payment purpose, and beneficiary type?
- Limits: What transaction and cumulative limits apply to this account and route?
- Recipient requirements: Which legal-name, bank, account, routing, address, and payment-purpose fields are mandatory?
- Timing: What delivery estimate applies to this specific quote, including holidays and any review?
- Exceptions: How are rejected payments, cancellations, refunds, and exchange-rate differences handled?
- Evidence: Can you distinguish submission from recipient credit and export the transaction reference?
Do not turn general speed claims into contractual payment promises. Account verification, beneficiary details, local processing, and compliance checks can affect an individual transfer. For recipient-data planning, use our country-by-country contractor bank payment guide alongside the service’s current requirements.
Pre-transfer checklist
- Confirm you are using the Saudi service, not Bahrain pricing.
- Identify the exact route and destination-specific fee.
- Check the Pakistan threshold where relevant.
- Review VAT, total debit, exchange rate, and net recipient amount together.
- Verify beneficiary details through an approved channel.
- Confirm permitted use, applicable limits, and the quoted delivery estimate.
- Save the quote, receipt, payment reference, and final status against the payable.
The bottom line
STC Pay’s Saudi transfer fee is best understood as a destination-and-route charge: generally SAR 15–25 before VAT through Western Union, with a Pakistan threshold exception and separate bank-abroad pricing. The fee table answers the initial pricing question; the live quote answers what this payment will cost.
For recurring business payouts, first establish eligibility and delivered cost, then assess the operational controls. If manual transfers no longer fit your payment volume, explore Payouts.com’s payout automation and evaluate your actual corridors, approval needs, and reconciliation requirements—not just headline transfer fees.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
38 commentsRelated resources
How to Pay International Contractors: A Country-by-Country Bank Payment Guide
A successful contractor payment delivers the agreed amount—not just a completed transfer instruction. Build a country-specific payment plan around bank details, currency, fees, and the date funds become available.
How to Reduce Cross Border Payment Fees: A Finance Playbook
Lower transfer fees do not always mean cheaper payouts. Learn how to negotiate, operationalize, and verify savings across your international payment program.
QuickBooks Online Supplier Payment on Account: A Guide
A supplier advance should remain traceable until the invoice arrives—not become a duplicate expense or a second payment. Here’s how to record, allocate, and reconcile it in QuickBooks Online.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The point about intermediary deductions on the SAR 50 bank-abroad route deserves more detail. We tested this corridor for USD vendor payments and still got hit with correspondent fees that weren't disclosed at quote time, so the 'published fee' ended up being only part of the actual cost.
We've had the same experience with EUR payments. The correspondent chain isn't disclosed until after settlement, and by then the deduction is already taken. Now we add a 20-25 EUR buffer on top of invoice amounts for that route and reconcile the difference afterward.
The warning about bank-account destinations not automatically triggering the SAR 50 route is gold. We've been assuming that any SWIFT delivery defaults to the bank-abroad pricing and now I'm wondering how many payments we've miscategorized in our cost analysis over the past six months.
Worth pulling every confirmation screen for the past quarter and checking which route identifier appears. We found three payments where the destination bank field was populated but the system still used the WU corridor at SAR 15, not the SAR 50 route.
We're doing the same review now. The app doesn't surface the routing choice clearly enough during setup, so you really have to go back through confirmations and match the actual fee charged against the schedule to reverse-engineer which path was used.
The VAT treatment is already causing reconciliation headaches for us. We book the base fee from the schedule but the actual debit includes tax that isn't broken out cleanly in the confirmation export, so we're having to manually split it for GL coding. Does STC Bank's API or statement download separate the components, or is everyone else doing this manually too?
We had the same problem until we started pulling the full transaction detail from the statement download rather than relying on the confirmation screen. The line-item breakdown there shows fee and VAT separately, at least for our account. Worth checking if your statement format has improved recently.
We had the same problem until we started pulling the full transaction detail from the statement download instead of relying on the confirmation screen. The VAT line item shows up there separately, at least for the past two months. Still manual but at least the split is documented.
The distinction between published fees and total cost is critical but the article doesn't clarify when VAT became applicable to these transfers. We're reconciling Q1 payments now and seeing inconsistent VAT treatment across different transaction dates—does anyone know if there was a rate or applicability change when STC Pay moved under STC Bank's license in January?
We ran into the same confusion. The article doesn't give a specific VAT effective date, but STC Bank's banking license became active in January 2025, so I'd expect VAT treatment to align with whatever SAMA and Zakat, Tax and Customs Authority rules apply to licensed banks versus the old wallet structure. Check whether your Q1 transactions spanned that transition—that could explain inconsistent application.
We ran into this exact issue. SAMA's January 2025 announcement about STC Bank commencing operations seems to be the inflection point—our February transactions show VAT applied consistently, but January was a mix depending on whether the transfer processed under the old wallet structure or the new bank license. Worth checking if your Q1 inconsistency maps to that transition window.
The separate SAR 50 bank-abroad route versus the Western Union pricing is critical. We reconciled three months of vendor payments before realizing we'd been charged the higher fee for destinations that were also available through the WU route at SAR 15. The article is correct that bank account delivery does not automatically mean the SAR 50 charge applies, but the app doesn't make this obvious during selection.
Did you escalate this with the bank or just adjust your process going forward? We're auditing our last six months now and wondering if there's any precedent for disputing routing errors when the delivered amount matches but the fee path was suboptimal.
We caught this same issue last quarter. The app doesn't make the routing obvious at all, and when you enter bank details it feels like it should just pick the cheapest path. Now we verify the route name on every single payment before approving, no exceptions.
The fixed-recipient-amount approach makes sense in principle, but does STC Bank's interface actually support entering PKR or PHP directly, or are you stuck reverse-engineering the SAR send amount to hit your invoice? We've tested a few platforms and most still force you to send SAR then show you what arrives.
Last time I checked, the interface still only accepts SAR input for most corridors. You end up iterating the send amount manually until the recipient side lands close enough to your invoice. It's frustrating and adds time to every batch.
Last I tested it defaults to SAR input for most corridors. You can sometimes toggle to recipient currency entry but it's not obvious and doesn't persist across sessions, so we just built a reverse calculator in our approval workflow to estimate the send amount that nets the correct invoice value.
The Pakistan waiver above SAR 375 is interesting but the article is right to flag the FX spread - we tested this last quarter and the effective cost per PKR delivered was still higher than our corporate FX platform even with the zero explicit fee.
We're seeing the same pattern with INR payments. The waived fee looks good on paper but the spread more than makes up for it. Would be useful if the article included some worked examples showing total cost per 1000 PKR or similar.
Did you document the effective spread as a percentage? We're benchmarking PKR corridors now and trying to build a baseline for treasurer review before we route anything through the wallets.
The distinction between the Western Union route and the separate bank-abroad transfer at SAR 50 is crucial. We nearly routed a Jordan payment through the wrong service because the vendor provided bank details and our team assumed that automatically meant the higher fee. Turned out Jordan qualified for the SAR 20 Western Union bank delivery, saving us SAR 30 per transaction across 40+ monthly payments.
Same trap here. Bank details don't determine the route. We now screenshot the service name shown in the quote before confirming, because the app doesn't always make it obvious which rail you're actually using.
We had a similar near-miss with Egypt. The vendor gave SWIFT details but the app defaulted to the Western Union route at SAR 15 and confirmed delivery to that account. Now we verify the selected service before every submit, not just the destination.
The formula at the end (total SAR debit ÷ net recipient currency received) is simple but we missed it for months. We were dividing send amount by recipient amount and wondering why the reconciliation never balanced with the actual bank statement debit.
We made the exact same error. The fee gets added on top, so you have to capture the full statement debit. Once we switched to that formula our variance reports actually started making sense.
We built a spreadsheet template that pulls the final debit directly from the confirmation screen now. Saves the AP team from having to remember which number to use, and reconciliation time dropped by half.
The point about not changing invoice amounts or combining beneficiaries to hit the SAR 375 threshold is critical. We had a junior AP clerk try to batch two unrelated Pakistan invoices to avoid the fee and it broke our three-way match completely. Now we have an explicit policy that pricing thresholds never override approved payable amounts.
We enforce the same rule now. The threshold optimization broke audit trails and created a mess for month-end close. Better to absorb the SAR 15 and keep the payment tied to a single approved invoice.
We enforce the same rule now. The threshold optimization broke audit trails and created a nightmare when one vendor disputed their amount. Policy is simple: one invoice, one transfer, period.
Does anyone know if the SAR 50 bank-abroad route actually avoids intermediary deductions, or is that just wishful thinking? We've been using the WU route for most Middle East payments specifically because cash pickup gives us certainty, but if the bank route delivers the full amount it might be worth the higher upfront fee for audit trail purposes.
In our experience the bank-abroad route still hits correspondent fees about 60% of the time, especially to smaller regional banks. We ended up asking beneficiaries to confirm what they actually received and built that into our reconciliation workflow. Cash pickup adds friction but at least you know the number upfront.
In our experience the bank-abroad route still hits correspondent fees about 60% of the time. We switched to a regional fintech for Iraq and Jordan payments because at least their quote shows net delivery upfront, even if the margin is higher. The WU cash option through STC made sense for us too until we had compliance flag it for commercial use.
Important detail that VAT is excluded from the published schedule. I've seen AP teams flag 'overcharges' when they were just looking at the base table and didn't account for tax on the actual debit.
We had the same confusion during our first reconciliation cycle. The fee schedule shows SAR 15 or SAR 20, but the GL shows higher debits. Tax treatment also varies by entity structure, so you can't just assume it's recoverable without checking with your auditor.
We build this into onboarding now. New AP staff get walked through one sample quote showing base fee, VAT line, and total debit before they touch live payments. Saves a lot of reconciliation noise later.
The fixed recipient amount comparison is the right approach. We learned this the hard way after reconciling dozens of contractor payments where the SAR send amount was consistent but the USD delivered varied by 3-4%. Now we always quote based on what the vendor invoice says they need to receive, not what we're comfortable spending.
Exactly this. We had the same issue with PHP contractor payments. The transfer fee looked stable but conversion slippage was eating 2-3% on every run. Switched to locking the recipient amount and now variance is actually trackable.
Same experience here. We switched to fixed recipient amounts and immediately caught a pattern where the conversion spread widened during month-end peaks. The article's point about matched comparison timing is critical—quotes from different hours can show variance that has nothing to do with the fee schedule.