

Stripe Affiliate Payouts: Connect or Global Payouts?
Stripe can move affiliate commissions, but attribution, commission approval, and bank settlement are separate jobs. Here is how to choose the right payout architecture and avoid promising more than your setup can deliver.
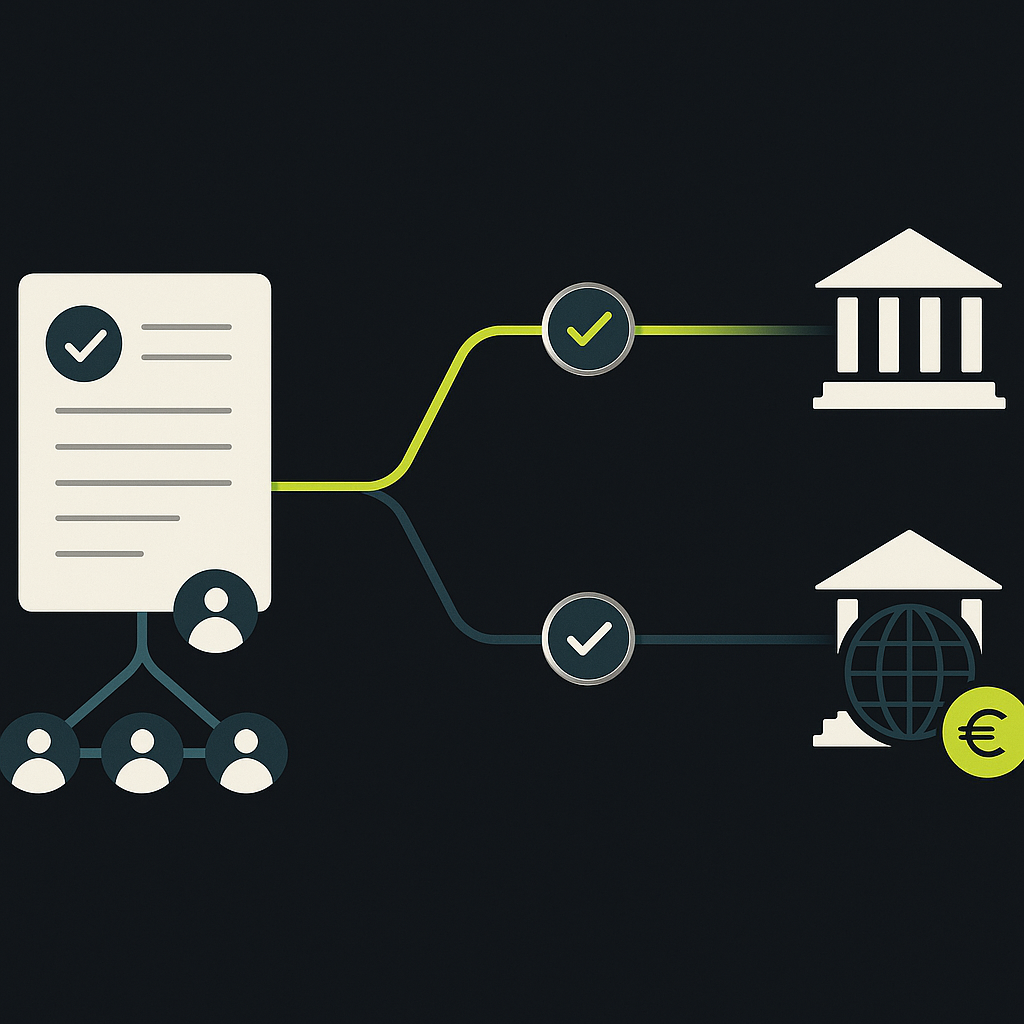
You can use Stripe to pay your own affiliates through Connect or Global Payouts, subject to product eligibility and supported payment routes. Connect uses connected accounts; Global Payouts supports third-party disbursements without recipients needing a Stripe account. Neither choice, by itself, determines which affiliate earned a commission or when that commission becomes payable.
For finance teams paying an international partner base, the key question is therefore not just whether Stripe supports affiliate payouts. It is which product fits your recipient model, how funds reach each destination, and where your commission system hands responsibility to the payment system.
First, distinguish payouts through Stripe from commissions paid by Stripe
If you want to earn money by referring businesses to Stripe, that is a different question. Stripe publishes affiliate terms under which commission rates for qualified leads and opportunities are agreed in an electronic insertion order. Those terms do not establish a universal commission rate or an open-enrollment offer for every applicant. Confirm your eligibility and payment terms directly with Stripe.
This guide focuses on businesses using Stripe infrastructure to pay their own affiliate partners.
Connect vs. Global Payouts: choose the recipient model first
Stripe Connect provides platform and marketplace payment infrastructure built around connected accounts. For an affiliate implementation, your application or affiliate software maps each eligible partner to a connected account and initiates the appropriate movement of funds.
Stripe Global Payouts explicitly supports paying affiliates and other third parties in local currencies without requiring recipients to create Stripe accounts. It is a separate product model, not simply a setting that broadens Connect coverage.
The assessments below are architectural guidance, not product ratings. Availability must be checked for your business and each intended payment route.
| Decision point | Connect | Global Payouts | Editorial guidance |
|---|---|---|---|
| Recipient model | Connected accounts | No recipient Stripe account required | Start with onboarding fit |
| Core use case | Platform payments and distributions | Third-party disbursements | Match the actual funds flow |
| Commission calculation | Separate business logic | Separate business logic | Keep entitlement outside payment execution |
| International eligibility | Configuration and route dependent | Product and route dependent | Verify specific sender-recipient combinations |
| Best for | Programs fitting a connected-account model | Programs prioritizing direct recipient payouts | Validate operational fit before building |
If your business already uses Connect, extending that architecture may reduce duplicated infrastructure. But accepting customer payments through Stripe alone is not a sufficient reason to require every affiliate to become a connected account.
What Stripe handles—and what your affiliate system must handle
Think of the workflow as separate responsibilities:
- Attribution: connect a customer or qualifying transaction to an affiliate.
- Entitlement: calculate the commission using your contract, exclusions, and renewal rules.
- Approval: determine whether the commission has cleared refund, fraud, and documentation checks.
- Execution: submit an authorized payment through the selected product.
- Settlement tracking: establish whether funds reached the intended destination or need investigation.
Stripe payment events, checkout references, metadata, and promotion codes can supply inputs to attribution. They do not independently resolve competing referral claims or decide whether a refunded transaction still earns a commission. Stripe's affiliate and referrals app category is one place to evaluate tools for that separate layer.
A transfer is not necessarily a bank payout
In a Connect flow, moving funds into a connected account and paying funds out to its external bank account are distinct operations. A successful transfer should not automatically generate an email saying the affiliate's bank has received the money.
Your internal record should distinguish commission approval, transfer execution where applicable, payout submission, provider-reported completion, and subsequent failures or returns. Preserve both your commission reference and the provider's payment identifiers so support can locate the actual handoff that stalled.
Refunds require commission policy, not just payment events
Define the commission base explicitly: gross sale value, revenue excluding tax, or another contractually specified amount. Also define treatment of discounts, partial refunds, renewals, and disputes.
A subscription cancellation may stop future commissions without invalidating previously earned ones. A refund after payout creates a recovery question; it does not guarantee that money can simply be pulled back from an affiliate's bank. Set permitted offsets, recovery procedures, and affiliate communications in the program terms.
Validate international coverage as a complete payment route
Do not use Stripe's overall payment currency support or country presence as proof that your specific affiliate payout flow is supported. An affiliate software vendor can also impose narrower restrictions than the underlying Stripe product.
Build a route-level eligibility sheet before inviting affiliates to select a payment method:
- Sender: your contracting entity, account country, and enabled payout product.
- Recipient: residence or business location, individual or company status, and bank country.
- Money: commission currency, funding currency, and requested settlement currency.
- Method: available bank or other payout method and applicable limits.
- Data: required identity, address, beneficiary, account, and routing fields.
- Operations: verification requirements, return handling, and expected delivery range.
Bank-data requirements vary. Some destinations use an IBAN; others require a domestic account number and local routing identifier. Beneficiary names and addresses may also be mandatory. Collect against the chosen product's destination requirements rather than one universal bank-details form.
For an evaluation framework, use this guide to testing payout corridors rather than country counts. An unsupported destination should enter a documented alternative payment process, not disappear into an unowned exception queue.
Separate commission timing, funding, and delivery
An affiliate's wait includes several different periods: commission validation, your scheduled payment run, funds becoming usable, and delivery through the selected method. Compliance reviews, bank holidays, invalid account details, and returns can extend that timeline.
Publish a commitment you control, such as when approved commissions enter a payout run, separately from a destination-specific delivery estimate. Avoid a universal bank-arrival promise based on one domestic route or an affiliate tool's marketing page.
Before approving a batch, confirm usable funding in the required currency and any relevant product-specific funding conditions. Revenue recorded in your accounting system is not necessarily cash available for immediate payout. The payment ETA framework helps distinguish internal release delays from downstream settlement time.
Evaluate the affiliate's net receipt, not one advertised fee
A meaningful cost comparison follows the same approved commission through each eligible route. Ask for the applicable account or platform charges, payout charges, currency conversion costs, cross-border charges, and possible receiving-bank deductions. Not every charge applies to every setup.
Pay particular attention to currency conversion ownership. A commission denominated in one currency, funded in another, and delivered in a third can create unnecessary conversions. Record the approved commission amount separately from the settlement amount, exchange rate, and fees.
Define who bears those costs in the affiliate agreement. Otherwise, a technically successful payout can still trigger a support dispute because the partner expected the full commission amount in their bank account.
Launch checklist: test the boundaries before scaling
- Confirm product eligibility. Validate your entity, use case, recipient locations, currencies, and intended methods with the applicable provider documentation and account configuration.
- Verify the affiliate tool's implementation. Ask which Stripe product it uses, whose balance funds payments, and what its reported payout statuses actually mean.
- Document commission rules. Specify attribution precedence, the commission base, approval conditions, and post-payment adjustments.
- Collect required documentation. Separate payment-provider verification from your own tax reporting and withholding obligations. Determine those obligations by entity, recipient, and jurisdiction.
- Protect payment release. Use approval controls, audit trails for beneficiary changes, and duplicate-prevention keys tied to approved commission obligations.
- Test adverse events. Include a partial refund, incomplete verification, rejected bank details, insufficient funding, and an ambiguous payment response.
- Control alternative payments. Do not resend through another provider while the original payment might still complete. Establish its status first.
- Reconcile the full chain. Match commission liability, provider movement, fees, FX, and returned funds before closing the obligation.
Choose the architecture you can explain to finance and affiliates
Stripe affiliate payouts work best when each layer has a clear owner. Connect fits connected-account workflows; Global Payouts offers a distinct third-party disbursement model. Your commission system still needs to establish entitlement, and finance still needs evidence of funding, authorization, and payment outcome.
Start by mapping your actual recipient routes and testing exceptions before automating the whole program. If your requirements extend across multiple rails and a broader finance workflow, evaluate Payouts.com's affiliate payout solution and payout automation against that same route-level checklist. The goal is not merely to send commissions—it is to make every approved obligation traceable to a defensible outcome.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
40 commentsRelated resources
How to Evaluate a Mass Payout Platform: Test Corridors, Not Country Counts
Country coverage is not proof that a platform can deliver your payment run. Use a corridor-level acceptance test to evaluate costs, recipient requirements, delivery evidence, and failure handling.
Payout Settlement Times by Country: Build Reliable Payment ETAs
An instant domestic rail does not make an international payout instant. Use this country reference and operating framework to set payment ETAs that account for funding, calendars, and recipient-bank availability.
Klarna Launches Stablecoin to Cut Cost of Cross-Border Payments
KlarnaUSD signals a move toward stablecoins inside payment providers’ settlement infrastructure. For finance teams, the opportunity depends on end-to-end economics—not just cheaper blockchain transfers.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The route-level eligibility sheet is the right call but it's a moving target. We maintain one for our creator payouts and have to revalidate quarterly because Stripe changes supported methods, our affiliates move countries, and banks merge or change routing formats. It's become a dedicated ops task, not a one-time setup doc.
The distinction between attribution and entitlement is something most affiliate tools gloss over completely. We ended up having to build a custom decisioning layer just to handle commission conflicts when multiple partners claim the same lead, and none of that logic can live in the payment system itself.
We faced this exact issue and ended up treating the payment system as write-only from the affiliate engine's perspective. All the conflict resolution, multi-touch weighting, and override rules live upstream in a separate service that only submits final approved amounts to Stripe. Keeps the payment layer clean but means you need solid audit logging at the handoff point.
We did something similar. The commission engine has to be stateful and own the entire adjudication process—Stripe only gets invoked once entitlement is final and irrevocable. Trying to merge that logic into payment metadata was a disaster.
The section on refunds creating a recovery question rather than an automatic clawback is something we didn't think through until an affiliate disputed our attempt to offset a chargeback against their next payout. Now we have a formal recovery procedure in the terms but enforcement across jurisdictions is still messy.
We added a clawback threshold to the terms—anything under $500 we can offset automatically, anything above requires notice and consent. Cuts down on disputes and gives us a clearer process when cross-border collection isn't practical.
We added a clawback threshold to the terms—anything under $500 we can offset automatically, anything above requires written notice and a 15-day response window. Still doesn't solve cross-border enforcement but at least it keeps the small stuff from turning into support tickets.
The reminder that Connect transfers and bank payouts are distinct operations is something we had to learn twice. First when we built our marketplace, then again when we tried to bolt on affiliate payouts using the same infrastructure. The status webhooks don't map cleanly to what an affiliate expects to hear, and we ended up building a whole translation layer just to avoid promising settlement before it actually happened.
We ended up adding an explicit affiliate_bank_settled status that only gets triggered after we reconcile the payout.paid event with our own ledger. The intermediate transfer states just confuse support and affiliates both.
We ended up adding an explicit affiliate_bank_settled status that only gets triggered after the payout.paid webhook comes back. Before that we show commission_approved and transfer_completed separately in the dashboard. Cuts down support tickets by about 70%.
The warning about not using Stripe's overall currency support as proof your specific flow works is absolutely critical. We spent three weeks onboarding affiliates in Southeast Asia only to discover that while Stripe technically supports those countries, our specific entity-to-individual-via-bank-transfer route had different documentation requirements than what our provider's UI suggested. Now we maintain a living spreadsheet of tested routes with actual completion times and required fields before we allow selection in the signup form.
We had the same experience launching in Brazil and Philippines. The eligibility matrix in the article is the right answer—now we literally test sender entity + recipient type + bank country + currency combination before we sign anyone. Saved us from repeating that mistake in EMEA.
We hit this exact issue with Philippines payouts. Had to tear down the whole flow and rebuild with a different entity structure. Now we validate the complete route—sender entity, recipient type, currency pair, and method—before we even show a country in the affiliate signup form.
The refund treatment section saved us real headache potential. We had been building an affiliate integration with automatic clawback logic assuming we could just reverse the payout, but our legal team flagged that without explicit offset terms in the partner agreement we'd have no recourse except asking nicely. Now we're adding a reserve clause and clear recovery language before launch.
We went through the exact same exercise and ended up adding a liquidated damages clause to the affiliate agreement that caps our exposure to the trailing 90 days of commissions. It's not perfect but at least gives us a ceiling if someone goes dark after a big refund event.
We went through the exact same exercise and ended up adding a liquidated damages clause to our partner agreements that caps recovery liability at the trailing 90 days of commissions. Doesn't solve the mechanical reversal problem but at least gives us a documented cap if we need to pursue recovery outside the payment rails.
The separation between Connect transfers and actual bank payouts caught us off guard when we first scaled internationally. We were sending affiliates 'payment sent' emails immediately after the transfer call succeeded, then had to field dozens of support tickets from partners whose banks hadn't received anything yet. Now we wait for the payout.paid webhook and even then add a disclaimer about correspondent bank delays.
We solved this by separating the commission approved notification from the funds delivered notification entirely. The first goes out when the transfer succeeds, the second only fires when we see the payout.paid webhook. Reduced support load by about 80%.
We made the same mistake and solved it by waiting for the payout.paid webhook before triggering any recipient-facing communication. Added about 2-3 days of perceived delay but completely eliminated the support burden from confused affiliates checking their accounts.
The recommendation to keep entitlement logic outside the payment execution layer is spot on. We made the mistake of coupling commission calculation too tightly with Stripe webhooks early on, and it became impossible to handle edge cases like partial refunds or multi-touch attribution without hacking around payment events that weren't designed for that purpose.
We had the same problem. Ended up treating the commission engine as a separate source of truth that just hands finalized amounts to the payment layer with an immutable reference ID. Stripe only sees the instruction to pay, not how we calculated it or what refund adjustments already happened upstream.
We ended up treating commission calculation as a completely separate system that emits payment instructions to Stripe rather than reacting to Stripe events. The commission engine decides what's owed, Stripe just executes. That handoff made everything cleaner including when we needed to switch payout providers for certain corridors.
The section on attribution versus execution really nails the handoff problem. Most affiliate SaaS tools want to own the whole flow, but if you're already running Connect for something else, you end up with two parallel ledgers and no clean way to reconcile when a payout fails three days after the commission was marked 'paid' in the affiliate dashboard.
We ran into this exact reconciliation gap. The way we finally handled it was treating the affiliate tool as source of truth for commission entitlement only, then writing payout status back from Stripe webhooks into a separate tracking table. Messy but at least we could see where things hung.
Exactly. We ended up writing a status field that tracks commission_approved, transfer_initiated, payout_submitted, and settlement_confirmed separately. The affiliate dashboard only shows the last one, but finance needs visibility into all four states or we can't diagnose where things broke.
The route-level eligibility sheet recommendation is really practical. We wasted two months onboarding affiliates in Eastern Europe only to discover mid-payout that our entity country + their bank country combination wasn't actually supported for the currency we promised, even though both were theoretically in scope.
We learned the same lesson the hard way. Now we build a route matrix with actual test transactions before onboarding anyone, especially when the affiliate can choose their settlement currency. The gap between theoretical product availability and actual executable routes is surprisingly large.
We now require proof-of-route testing before launch. Literally send $1 test payouts to real affiliates in each target country during onboarding, wait for settlement confirmation, then document the working configuration. Costs almost nothing and catches these mismatches before you have angry partners and compliance exposure.
The point about not using overall Stripe country support as proof your specific payout flow works is something we learned after onboarding 30+ affiliates in Eastern Europe. Turned out the sender-recipient-currency combination we needed wasn't actually supported even though both countries were listed in the docs.
Same. We now require a successful test transaction for every sender-recipient-currency trio before we mark that route as available in our affiliate portal. Saved us from promising payouts we couldn't actually execute.
We built a test matrix before launching any program now—literally a spreadsheet with sender entity, recipient country, currency trio, and whether we've confirmed a live payout succeeded. Saves so much pain later.
Wish this had existed six months ago. We built our entire affiliate program assuming Global Payouts would just work for all the currencies Stripe lists in their docs, then discovered half our routes to Southeast Asia required additional KYC steps we hadn't designed for. The route-level eligibility sheet advice is exactly right—test the full sender-recipient-currency combination before you promise anything.
We hit the exact same thing with beneficiary name formatting. The docs say a country is supported, but then you find out corporate payee names get truncated at 35 characters or need to match a specific registration database format. Now we collect all bank details during onboarding and run test payouts before activating anyone.
We went through the same pain with LATAM routes. Stripe's product docs list capabilities at the payment-method level but the actual country-pair combinations and KYC thresholds live in separate compliance tables that aren't surfaced until you're already in implementation. Now we map every new affiliate geography before onboarding instead of after.
The distinction between transfer and bank payout in Connect is subtle but painful when you get it wrong. We learned this the hard way after sending automated "your payment was sent" emails when the transfer completed, then had to walk back several cases where the actual bank settlement failed or was delayed by verification holds. Now we track both events separately and only send confirmation after the payout status is complete.
We solved this by separating the commission approved notification from the funds delivered notification completely. The first happens when we write the transfer, the second only fires after we see the payout.paid webhook and verify the transaction_id matches our ledger. Still not perfect because of returns, but at least we stopped overpromising.
Same issue here. We ended up building a separate reconciliation step that waits for the payout.paid webhook before triggering any external communication. Added 24-48 hours of delay but eliminated the awkward support tickets when affiliates saw confirmation but never got the wire.
The refund policy section is critical and most affiliate platforms don't make it easy to configure. What's your recommended approach when a customer refunds 30 days after you've already paid the commission? We're currently doing manual offsets against future commissions but it's messy and doesn't scale.
We switched to a 60-day hold before releasing commissions and it helped a lot with this. The downside is partners hate the delay, but having a policy-enforced buffer means refunds usually happen before payout and you avoid the whole clawback process.
We implemented a minimum hold period before releasing commissions—usually 45 days—and that eliminated most of the manual offset work. You still need a policy for what happens if the affiliate churns before you can recover, but at least the happy path is cleaner.