

Supplier Payment Reporting: Build an Audit-Ready AP Dataset
Supplier payment reports are only as reliable as the invoice and payment events behind them. Learn how to build a traceable reporting dataset and test whether AP automation can produce defensible disclosures.
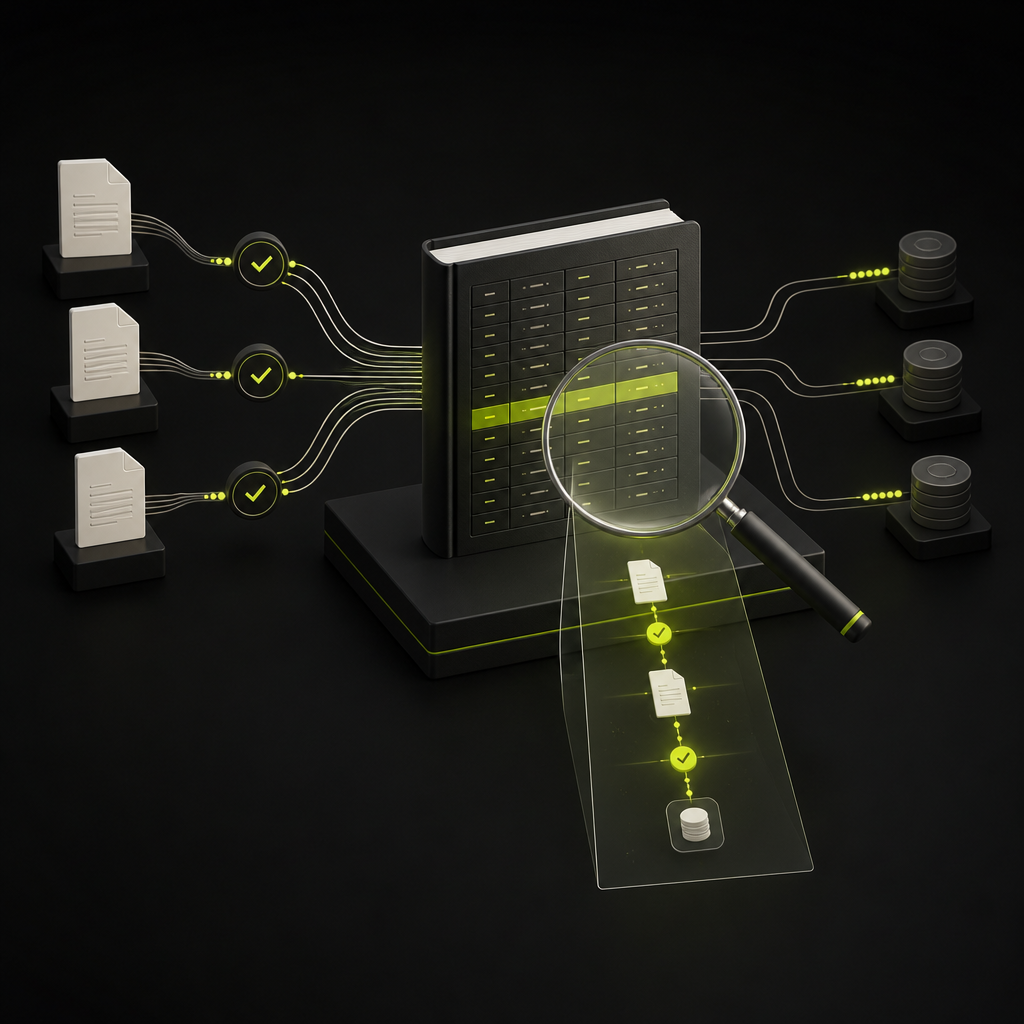
Supplier payment reporting is the measurement and disclosure of how a business pays its suppliers: its payment terms, time taken to pay, overdue obligations, and reasons for delay. It supports internal cash and AP management and, in some jurisdictions, mandatory public disclosures.
For controllers comparing AP automation platforms, the critical question is not whether software produces a dashboard. It is whether every reported figure can be traced to the right invoices, contractual terms, payment events, and reporting rules.
The practical solution is a governed invoice-to-payment dataset that supports both operational analysis and jurisdiction-specific reporting. Those outputs can share evidence, but they should not automatically share calculation rules.
Separate management reporting from statutory disclosure
An internal report might measure approval delays by department or forecast overdue balances. A statutory report uses a prescribed scope, period, and calculation methodology. A useful management metric is not necessarily a compliant disclosure.
Keep distinct reporting layers:
- Operational: What needs intervention, and who owns it?
- Management: Are payment performance and working-capital decisions improving?
- Statutory: What must each reporting entity disclose under the applicable rules?
This distinction prevents a common error: using an ERP's standard aging report as evidence of payment performance. Aging shows outstanding balances at a point in time; it does not, by itself, explain how long paid invoices took to settle.
UK requirements: overlapping obligations, not interchangeable reports
The UK payment practices regime requires qualifying large companies and LLPs to publish reports twice yearly. Changes to the payment practices reporting requirements expanded disclosures for financial years beginning on or after 1 January 2025, including payment-value and dispute-related information. Scope and calculations should be checked against the rules applicable to the entity and financial year.
A separate annual-report requirement now applies. The Companies (Directors’ Report) (Payment Reporting) Regulations 2025 came into force on 1 January 2026 and introduce payment disclosures in directors' reports for financial years beginning on or after that date. These apply to qualifying large companies across the UK; they do not replace the twice-yearly reporting obligation.
For a calendar-year company in scope, the first affected financial year is 2026, with its annual report following in 2027. PwC's explanation of the annual-report rules provides context for the additional disclosure requirement.
There is also uncertainty over the future presentation of these disclosures: the government's announced plan to remove the directors' report could relocate some requirements. Do not treat that announcement as a cancellation of current obligations. Have the company secretary or legal adviser confirm scope, applicable size tests, transition provisions, and current filing requirements.
Public-procurement payment notices and supplier tax reporting are separate regimes. A multinational business should map obligations by legal entity and jurisdiction rather than label one export a universal compliance report.
Build the evidence before building the dashboard
The reporting foundation should connect each invoice to its lifecycle events. Preserve source timestamps rather than replacing them whenever an invoice changes status.
| Evidence group | Fields to retain | Reporting purpose |
|---|---|---|
| Entity and scope | Buyer entity, supplier ID, contract reference, scope classification | Define the report population |
| Invoice receipt | Invoice ID, original receipt timestamp, source record | Establish the relevant starting event |
| Contractual terms | Agreed terms, due date, amendments, effective dates | Evaluate payment against terms |
| Workflow | Validation, approval, hold, and release events | Locate internal delays |
| Disputes | Reason, affected amount, opened and resolved timestamps | Support dispute classifications |
| Payment execution | Instruction ID, status history, completion evidence, returns | Distinguish release from completion |
| Allocation | Invoice-payment links, partial amounts, credits, currency | Handle split and consolidated payments |
| Report lineage | Period, rule version, exclusions, adjustments, approver | Reproduce the published result |
Use an allocation structure that supports multiple payments against an invoice and multiple invoices within a payment. A single payment-date field cannot adequately represent both situations.
Payment status also needs a documented interpretation. An instruction accepted by a bank is not necessarily evidence that the supplier received funds. Retain the available events and map the required payment-date definition to the relevant reporting rule. Do not silently substitute a convenient timestamp.
Assess ERP and accounting integrations for event coverage, not merely whether balances synchronize. A connector that transfers only the latest status can erase the history needed to explain a reporting result.
Write a metric contract for every reported figure
A metric contract is a short specification describing exactly how a result is calculated. It should identify the population, numerator, denominator, date basis, exclusions, currency treatment, and treatment of adjustments.
Define the population before the formula
Payments completed during a period and invoices received during that period are different populations. So are invoices outstanding at period-end. Combining them can make a percentage look precise while answering the wrong question.
For an internal average-time-to-pay metric, document the chosen starting and ending events and whether the calculation is invoice-weighted or value-weighted. For a statutory metric, implement its prescribed methodology rather than adapting the internal average.
Keep elapsed time separate from contractual lateness
A payment can take a long time without breaching agreed terms. Conversely, a shorter payment interval can still be late under a tighter contract. Report elapsed time and performance against terms separately.
Also distinguish count-based and value-based measures. A good invoice-count result can coexist with a large overdue balance if the unpaid items are concentrated among high-value suppliers.
Make disputes and exceptions explicit
A disputed invoice should not disappear from the dataset. Record the dispute and apply the relevant inclusion or exclusion rule. Otherwise, a team can appear to improve performance simply by moving difficult invoices into a hold queue.
Separate disputes from missing approvals, invalid bank details, funding shortages, and failed payments. These conditions need different owners and corrective actions. A documented invoice approval workflow helps explain approval-stage delays without misclassifying them as supplier disputes.
Hypothetical example: the failed-payment trap
Suppose an invoice is approved and included in a bank batch before its due date. The payment is returned because the receiving account is closed. AP corrects the details and submits a replacement after the due date.
If the report uses batch submission as its payment event, it may classify the invoice as paid on time. If the dashboard retains only the latest status, it may show a completed payment without explaining the delay.
A defensible dataset preserves the original instruction, return, replacement, invoice allocation, and relevant completion evidence. The reporting engine then applies the appropriate date rule. The operational report identifies the bank-detail issue separately from approval performance.
The control is not simply a better formula. It is preserving enough history to apply and explain the formula correctly.
Test reporting capability during the AP software evaluation
Ask vendors to demonstrate reporting with your representative, anonymized edge cases—not only clean invoices. Include a partial payment, consolidated payment, disputed invoice, credit note, returned payment, and transaction spanning a reporting boundary.
- Trace a figure backward. Open an aggregate metric, identify its invoice population, and inspect the supporting events.
- Test missing evidence. Remove a receipt timestamp or payment allocation. The system should flag the gap rather than invent a date or silently exclude the record.
- Reconcile the population. Bridge report totals to AP records and payment activity, with documented reasons for differences.
- Reproduce a closed period. Confirm that later changes do not silently rewrite an approved report.
- Inspect corrections. Require adjustment reasons, supporting evidence, and authorization.
- Export the evidence. Check that finance can retrieve calculations and source references without relying on screenshots.
These tests extend the broader AP platform acceptance checklist into reporting-specific controls. Clarify whether the vendor supplies transaction data, configurable calculations, filing-ready outputs, or submission functionality. Those are different deliverables.
Close the report like a financial control
Assign AP ownership of invoice completeness and exception classification, treasury ownership of payment-event evidence, and the controller ownership of reconciliation and metric definitions. Route statutory interpretation and sign-off through the appropriate legal and governance roles.
Before approval, freeze the source extract, resolve or document missing data, reconcile totals, record exclusions, and retain the calculation version. Investigate changes in performance before attributing them to automation: a shift in supplier mix or contractual terms can change results without making processing faster.
The next step is to request a report-reproduction demonstration using one closed period. Explore Payouts.com AP Automation for connecting invoice capture, approvals, and payment, then validate the evidence and reporting requirements specific to your entities. Better supplier payment reporting starts when the workflow preserves the facts—not when a dashboard formats them.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
36 commentsRelated resources
Invoice Approval Workflow: Build a Matrix That Holds Up
An effective invoice approval workflow defines who can approve, what evidence they need, and when approval must reset. Use this framework to turn an email-based process into enforceable rules.
Accounts Payable Automation Platform: A Buyer’s Acceptance Checklist
The right AP platform should reduce work across the invoice-to-payment cycle—not move it into another queue. Use this acceptance checklist to turn vendor demonstrations into a defensible buying decision.
Sage Supplier Payments: Native Tools, Add-Ons, and AP Fit
Recording a supplier payment in Sage is not the same as executing and reconciling it. Here is how to evaluate native workflows and add-ons against your actual AP requirements.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The invoice-to-payment allocation structure described here is exactly what we're missing. Our current system assumes one payment per invoice and we've been manually reconciling split payments in spreadsheets for quarterly close, which is obviously not scalable or audit-friendly.
We had the same gap and ended up creating a many-to-many relationship table between invoices and payments with allocation amounts and effective dates. The part that gets messy is when you also need to account for credit memos and partial reversals, because then you need allocation history with temporal validity.
We built a payment allocation table last year for exactly this reason. The trick was getting the treasury team to send us structured remittance data instead of unstructured payment references. Once we had that, the many-to-many relationship between invoices and payments became much easier to handle programmatically.
The recommendation to document interpretation rules for payment status is something we learned the hard way during our first UK payment practices filing. Our AP team classified a payment as complete when it left our treasury system, but the auditor insisted it should be when the supplier's bank confirmed receipt. We had no documented rule, so we had to rebuild the entire dataset from scratch with new timestamps. Cost us three weeks and almost missed the filing deadline.
We had the same debate internally. The compromise we landed on was to define payment completion as when funds cleared the supplier's account, but we also log the treasury release timestamp in a separate field for internal metrics. That way statutory reporting uses the stricter definition while AP can still track their own process efficiency.
We faced the exact same ambiguity during our audit prep. The resolution for us was to distinguish between payment release (when we instructed the bank) and payment settlement (when funds cleared the supplier's account), then map each reporting obligation to the correct event. The metric contract approach in the article would have saved us weeks of back-and-forth.
The warning about not substituting a convenient timestamp is critical and undersells the risk. We found invoices marked paid when the payment file was generated, not when funds cleared, which created a systematic 2-3 day error across our entire disclosed average. Legal only caught it during a compliance review when someone manually traced a sample back to bank confirmations.
We had the opposite problem where our payment provider gave us cleared timestamps but our ERP only stored instruction dates. Took weeks to align on a single source of truth for the published metric, and even now we maintain a reconciliation schedule between the two systems every reporting period.
We had the opposite problem where our payment provider gave us cleared timestamps but our ERP only captured instruction dates. The mismatch surfaced during an internal audit when reconciling disclosed averages against bank statements. Had to retroactively build a mapping between payment instruction IDs and actual settlement confirmations just to prove what we'd already published.
The distinction between an instruction accepted by the bank versus actual supplier receipt is a nightmare in practice, especially with international payments where intermediary banks can sit on funds for days. We've started requiring MT103 confirmation for anything over a certain threshold, but that adds manual steps that partially defeat the automation.
We ran into the same issue with cross-border payments to APAC suppliers. The problem gets worse when you're trying to reconcile against statutory reporting windows because the same payment can fall into different periods depending on which timestamp you use. Have you found a scalable way to classify which events require MT103 versus relying on status confirmations from your banking platform?
We ran into the same issue with cross-border payments to APAC suppliers. The problem gets worse when you have to decide whether the reporting timestamp is when you released funds or when the supplier actually got credit. For statutory reporting we ended up defaulting to payment instruction date because we couldn't reliably prove receipt across every jurisdiction, but our internal metrics use confirmed receipt wherever we can get it.
The section on distinct reporting layers really exposes how poorly most AP automation vendors handle this in practice. Most platforms give you one calculation engine and expect you to just filter or rename columns to meet different requirements, which works until your first audit or regulatory review. Has anyone found a vendor that actually lets you configure separate rule sets per reporting purpose without custom dev work?
This hit us hard when we tried to use the same metrics for both internal forecasting and our first payment practices report. The vendor's support team actually told us to 'just export twice and adjust the dates in Excel' which is exactly the kind of shadow reporting process you're trying to avoid with automation in the first place.
We discovered this when our auditors asked us to reproduce a figure from six months prior and the vendor's dashboard had been updated in the meantime. The calculation logic changed but nothing in the UI indicated it, so our current export didn't match the filed report. Now we version every metric definition and keep snapshots of the raw data used for each filing period.
The UK reporting changes are a real operational headache for groups with multiple qualifying entities. We have four legal entities in scope and the combination of twice-yearly PPR filings plus the new directors' report requirement means we're now maintaining three different calculation pipelines for what looks like the same question but uses different populations and date rules. The advice to get company secretary confirmation on transition provisions is critical because we nearly missed that calendar-year companies don't hit the annual-report requirement until FY2026.
We're dealing with the same multiplier effect. The thing that caught us off guard was that each reporting layer needs its own audit trail—you can't just run the statutory calculation and call it done for management purposes. Have you found a way to reuse the underlying event data across all three pipelines, or are you essentially building separate datasets for each?
We're in a similar position with three UK entities. The real trap is that the twice-yearly PPR and the directors' report requirement use different calculation periods and slightly different scope tests, so you can't just reuse the same output. Have you found a way to modularize the evidence layer so at least the raw event data can feed all three pipelines?
The point about maintaining separate reporting layers is critical, but I think the article undersells how much organizational friction this creates. In practice, AP teams will always reach for the management report first because it's more actionable, and then finance scrambles when the statutory filing deadline approaches and discovers the definitions don't align. The real challenge isn't technical, it's getting stakeholders to accept maintaining what looks like duplicate reporting infrastructure.
We handled this by publishing both reports simultaneously on a fixed calendar, with the management report explicitly marked as draft if statutory isn't locked yet. Forces the conversation about what can change and what can't before anyone starts making decisions.
This is real, and it's worse when the AP team and statutory reporting team don't even sit in the same function. We ended up having to version-control the metric definitions and require sign-off from legal before any changes to the statutory layer, which added overhead but prevented last-minute reconciliation nightmares.
The recommendation to assess ERP connectors for event coverage rather than just balance synchronization is something we learned the hard way. Our AP automation vendor's integration pulled current invoice status but overwrote the approval timestamps every time something changed, which made it impossible to reconstruct approval delays when we needed to explain a spike in late payments to the board.
We had the exact same issue with status overwrites. The workaround we ended up using was creating a shadow audit table that captures every state change with immutable timestamps before the connector runs. Not elegant, but it was cheaper than rebuilding the integration from scratch.
We had the exact same issue with status overwrites. The workaround we ended up using was creating an event log table in our data warehouse that captures every state change via scheduled snapshots, which is clunky but at least preserves the timeline for audit purposes.
The metric contract section is gold. We've had so many arguments between AP, treasury, and FP&A because nobody documented whether 'days to pay' starts at invoice receipt, approval, or GL posting. Every team was running their own version of the truth.
We had the same chaos until our controller forced everyone into a room and made us define the starting event by use case. Internal performance tracking starts at approval, statutory disclosure starts at invoice date per the regulation, and treasury forecasting uses expected payment date. Three different clocks, all documented, no more arguments.
Same problem here. We finally documented it when our auditors rejected the payment performance analysis we'd been using internally for two years. Turns out we were mixing invoice date as the start for some suppliers and PO approval date for others depending on which system they came from.
"A single payment-date field cannot adequately represent both situations" - this is the exact problem we hit when moving from legacy AP to a modern system. Our data model had invoice.payment_date and we thought we were fine until we started doing payment runs that consolidated 20+ invoices. Now we have a junction table and it's messy but at least we can trace everything. Would be interested to know if the author has seen any off-the-shelf systems that actually handle this correctly out of the box.
We solved this with a junction table between invoices and payments that holds allocation amounts and timestamps. Each row represents one invoice-payment link. Sounds like you're discovering the same pattern the hard way.
We solved this with a junction table between invoices and payments that holds allocation amounts and timestamps. The trick is making sure the payment instruction completion event gets captured separately from the allocation record creation, otherwise you lose the actual settlement evidence the article talks about.
The point about aging reports not explaining paid invoice settlement time is something I've had to explain to auditors more than once. Our ERP exports a beautiful aging bucket report but it tells us nothing about our actual payment velocity on closed invoices, which is what the UK reporting actually asks for. We ended up building a separate extract that links invoice receipt dates to payment completion and it's been a constant maintenance headache.
Exactly this. We ended up building a separate dataset that logs every invoice status transition with timestamps, because the standard AP aging view just wasn't designed for payment velocity analysis. The metric contract section in the article is basically the spec we wish we'd had from day one.
Exactly this. We ended up building a separate dataset that logs every invoice status transition with timestamps, because the ERP only shows current state. When the auditors asked us to demonstrate our average payment terms last year, we had nothing defensible without those historical events.
Strong agree on keeping management reporting separate from statutory disclosure. We made the mistake of trying to use our internal KPIs (which we calculated one way for cashflow forecasting) as the basis for our first payment practices report and got pushback from legal. Had to rebuild the whole calculation pipeline with different date definitions and exclusions. The metric contract idea would have saved us weeks.
We went through the same thing. Our finance team assumed the ERP's standard payment report would work for the UK filing and only realized three weeks before deadline that the calculation basis was completely different. Ended up manually reconstructing the data from AP subledger exports.
We hit the same wall when legal reviewed our first draft. The issue for us was the date basis—we were measuring from invoice approval for internal purposes but the regs required measurement from receipt. Completely different populations and timings.