

SWIFT Cross Platform: Connecting Payment Data Across Systems
SWIFT connects financial institutions, but that does not automatically connect your finance workflows. Learn how to preserve payment data, approvals, and settlement evidence across your ERP, payout platform, and banks.
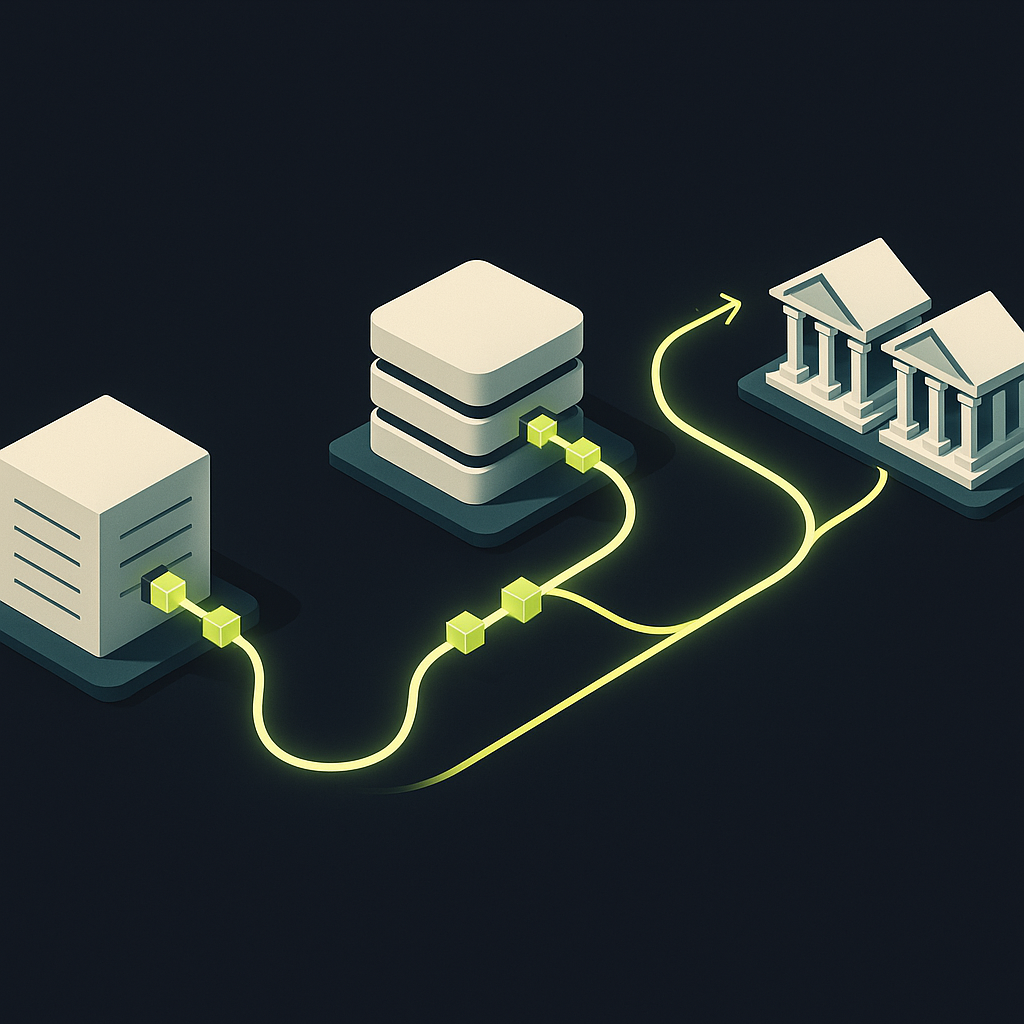
In global payments, SWIFT cross-platform interoperability means exchanging payment instructions and related data across banks and financial systems. SWIFT provides financial messaging; banks and payment infrastructures handle the movement and settlement of funds. Connecting your ERP, payout platform, and banking partners still requires consistent data, identifiers, and status definitions.
This guide addresses the payments meaning of “swift cross platform,” not the Swift programming language. Treat the phrase as a description of interoperability, rather than the name of a single payment service.
For finance teams paying hundreds of international recipients, the practical question is not simply whether a provider supports SWIFT. It is whether the amount, beneficiary, approval, and payment outcome remain understandable and traceable as the instruction crosses systems.
What SWIFT connects—and what it does not
As Currencycloud explains in its overview of SWIFT payments, SWIFT is a messaging network, not the institution transferring the money. Banks exchange instructions through the network, while settlement depends on banking relationships, account balances, and applicable payment infrastructure.
A business payout can therefore cross several distinct boundaries:
- Business systems: The ERP or accounts payable system establishes the obligation and approval.
- Payment interfaces: A platform or bank converts the approved instruction into a supported submission format.
- Banking infrastructure: Sending, intermediary, and receiving institutions process the transfer.
- Reporting systems: Status messages, account statements, and reconciliation records return to finance.
These boundaries explain why a technically successful integration can still produce operational failures. An API request may be accepted even though the payment later fails validation. A bank account may be debited before the recipient is credited. A statement entry may arrive without the invoice reference needed to close the payable.
Connectivity is the ability to exchange information. Operational interoperability is the ability to preserve its meaning.
ISO 20022 improves the language, not every handoff
SWIFT’s review of its 2025 milestones identifies November 22, 2025 as the transition milestone ending MT/ISO 20022 coexistence for cross-border payment instructions. That milestone should not be read as proof that every corporate file, domestic payment system, or internal bank application uses the same format.
ISO 20022 supports richer, structured payment information. That can help institutions distinguish debtor and creditor details, retain remittance information, and process instructions more consistently. But richer messages cannot repair missing source data.
If your ERP stores an entire beneficiary address in one free-text field, someone must still map it into the fields required downstream. If a connector truncates an invoice reference, a standards-compliant bank message will not restore it.
Create a canonical payout record
Define one internal representation of a payment before mapping it to individual providers. Keep the original business instruction separate from provider-specific fields and responses.
| Data group | Preserve across systems | Control at the handoff |
|---|---|---|
| Business identity | Payout ID, invoice reference, legal entity | References survive transformation |
| Beneficiary | Legal name, address, account details | Destination-specific validation |
| Money | Invoice, debit, and delivery currencies | No silent currency substitution |
| Commercial terms | FX quote, fees, charge instruction | Changes trigger policy checks |
| Authorization | Approved details and approval record | Submission matches authorization |
| Execution evidence | Provider references, bank references, events | Events attach to the correct payout |
| Accounting | Principal, fees, FX differences, returns | Cash movements reconcile separately |
Country requirements belong in validation rules, not a universal bank-details form. An IBAN is not a worldwide account identifier, and a SWIFT/BIC identifies an institution rather than replacing the beneficiary’s account details. Local routing codes, purpose information, and supporting documents may also be required by destination, currency, or bank.
Use the country-by-country bank payment guide as a starting point, then confirm the exact requirements with the executing provider.
Make status meanings explicit across platforms
One of the most consequential integration errors is mapping every positive response to “paid.” Require a written status dictionary from each provider and preserve its raw events alongside your normalized status.
- Accepted: The receiving interface accepted the request. Confirm whether validation is complete.
- Submitted: The instruction was handed to the next processing stage.
- Debited: Funds left the funding account; this is not necessarily beneficiary credit.
- Credited: Evidence indicates the beneficiary account received funds. Record the evidence source.
- Rejected or returned: Distinguish an instruction that did not execute from funds sent back after processing.
- Unknown: Available evidence does not establish the outcome. Investigate before resubmission.
Where available, store the SWIFT Unique End-to-end Transaction Reference alongside your internal payout ID and provider reference. Ask what tracking information the provider exposes; a reference alone does not guarantee that your team can access every downstream event.
Also retain event timestamps and receipt timestamps. Updates can arrive late or out of order, and a late “processing” event should not overwrite stronger evidence of credit. For delivery promises, distinguish network progress from actual availability to the recipient, as discussed in the guide to reliable payout settlement estimates.
Carry cost and approval controls through the connection
A payment can preserve its beneficiary details while losing its commercial meaning. For example, the invoice may be denominated in one currency, the funding account in another, and the recipient account configured to convert incoming funds.
Record the intended delivery currency and amount, the funding amount, the FX quote and expiry where applicable, disclosed fees, and the chosen charge instruction. OUR, SHA, and BEN describe charge allocation; do not treat the code alone as proof of the recipient’s final credit.
Decide which changes require renewed approval. A changed beneficiary account, expired FX quote, or different funding entity should not pass silently through a connector simply because the original invoice was approved.
When evaluating ERP and accounting integrations, inspect both directions: what the connector submits and what it writes back. Reconciliation needs more than a transaction marked “successful”; it needs enough evidence to explain the payable, cash movement, fees, and any remaining balance.
What newer SWIFT initiatives change
Retail payment rules can improve predictability
The Swift payments scheme establishes a framework for participating institutions to improve cross-border retail payment outcomes, including cost certainty, full-value delivery, and traceability. Its scope should not be generalized to every SWIFT payment.
Before incorporating these benefits into a payout promise, confirm the participating institutions, eligible corridor, payment type, and terms. A bank’s participation does not establish that every corporate supplier payment qualifies.
Shared-ledger development is not universal availability
July 2026 reporting on SWIFT’s shared ledger described preparations for live pilot transactions involving tokenized deposits. As of the September 2026 research informing this guide, that was not evidence of broadly available commercial coverage.
For finance teams, the important distinction is between an infrastructure initiative and a service your banking partner can actually deliver. Confirm access, settlement assets, liquidity requirements, operating hours, and legal terms before changing treasury assumptions.
A cross-platform acceptance checklist
Before moving a production payout workflow onto a new connection, test the handoffs—not just the happy-path transfer.
- Validate the source record. Check beneficiary data against the actual destination and currency requirements.
- Inspect transformed instructions. Confirm that names, addresses, currencies, and remittance references survive mapping.
- Test uncertain submissions. Simulate a timeout after submission. Verify how the provider checks for an existing instruction before permitting a retry.
- Challenge status mapping. Confirm which evidence supports “credited” and how delayed events are handled.
- Test commercial changes. Check quote expiry, fee changes, and beneficiary amendments against approval policy.
- Reconcile exceptions. Trace a rejection and a return through cash records, fees, and the open payable.
- Assign investigation ownership. Specify who contacts the provider, what references they need, and who authorizes any replacement payment.
Build around payment evidence, not connection counts
SWIFT enables communication across financial institutions. A dependable cross-platform payout operation must also preserve the instruction, authorization, commercial terms, and evidence of what happened.
The next step is to trace a representative payout from approved obligation to beneficiary credit and accounting close. Identify every point where data is transformed or a status changes meaning. When exploring Payouts.com’s payout automation, use that trace as your evaluation checklist: each handoff should be explainable, controlled, and reconcilable.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
40 commentsRelated resources
How to Pay International Contractors: A Country-by-Country Bank Payment Guide
A successful contractor payment delivers the agreed amount—not just a completed transfer instruction. Build a country-specific payment plan around bank details, currency, fees, and the date funds become available.
Payout Settlement Times by Country: Build Reliable Payment ETAs
An instant domestic rail does not make an international payout instant. Use this country reference and operating framework to set payment ETAs that account for funding, calendars, and recipient-bank availability.
Tax Reporting for Independent Contractors: Reconcile Global Payments
Reliable contractor tax reporting depends on connecting each payment to the right recipient, jurisdiction, and reporting treatment. Here is how finance teams can build a defensible process across currencies and payment rails.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The framing of SWIFT as a messaging layer rather than a settlement guarantee is important, but the article doesn't quite address how to handle the reconciliation when an intermediary bank deducts unexpected fees or changes the routing mid-flight. We've had cases where the beneficiary receives less than debited and the only evidence is a manual bank statement three weeks later.
We track this in a separate fee variance line in the accounting record. When the beneficiary confirms receipt, we compare their credited amount to our debited amount minus our known fees, and anything left over gets coded to intermediary bank charges. Not perfect, but at least it doesn't sit in suspense forever.
We track this in a separate fee variance line in the accounting record. When the beneficiary reports short payment we log it against the original payout ID and reconcile monthly with the provider, but honestly it's still manual detective work most of the time. Would love to know if anyone's actually getting structured fee breakdowns from intermediaries in the status callbacks.
The idea of preserving 'payment outcome' alongside instruction and approval is something we learned the hard way. We had a payout debited from our account, provider marked it successful, but the beneficiary never received it due to an intermediary bank rejection two days later. Now we require evidence of credit before closing the loop, but most platforms don't surface that automatically—you have to ask for it in the contract.
We had a similar gap until we required the provider to surface all downstream MT status codes, not just their own interpreted status. Now we treat 'debited' as cash movement but won't close the payable until we have either a credit confirmation or a correspondent bank acknowledgment.
We had a similar gap until we required the provider to surface all downstream MT status codes, not just their internal workflow states. Turns out the rejection happened at an intermediary we didn't even know was in the chain. Now we treat 'debited' as a cash event but hold the payable open until we see credited evidence or a return.
The section on status meanings is worth printing out and handing to anyone building a payment integration. We've had three different providers use 'completed' to mean three different things—one meant debited, one meant credited, and one just meant they forwarded it to their partner bank. Until we built a provider-specific status normalization layer and stopped trusting their labels at face value, our reconciliation was a mess.
We had the exact same mess. One provider's 'completed' just meant they sent the file to their downstream bank—no guarantee the recipient was even valid. Now we don't update our payables status until we see either a credited event or a return, whichever comes first.
We had the exact same issue with a provider whose 'submitted' status actually meant three different things depending on the destination country. Turned out their routing logic determined whether it went to a partner, a correspondent, or direct—but the status webhook didn't differentiate. We only caught it when reconciliation broke for certain corridors.
The part about defining a canonical payout record before mapping to providers saved us from a painful migration last year. We had three different systems defining 'beneficiary' in three different ways, and it was a nightmare until we forced everything through one internal schema first. The table showing what to preserve versus what to control at the handoff should be printed and taped to every integration developer's monitor.
We ran into the same thing during a platform migration. The versioning advice is key though—our canonical schema had to evolve when we added Brazil payments, and suddenly older payouts in the reconciliation queue couldn't map cleanly. Did you version your schema or just handle transformations on read?
We did something similar but also had to version the canonical schema itself because business requirements changed over time. Now we track which schema version each payout was submitted under, otherwise older records became impossible to interpret correctly during audits.
The advice to preserve the original business instruction separately from provider-specific fields is something we learned the hard way. When a payout fails three systems downstream, you need to know what the AP team actually approved versus what got transformed by various connectors—especially when beneficiary addresses get mangled by field-length limits or character restrictions that differ by provider.
We built a simple audit table that logs both the approved record and every transformation event with timestamps. When providers push back on failed payments, we can show exactly what left our system versus what they claim to have received. Saved us twice in disputes over FX rate application.
We built a simple audit table that logs both the approved record and every transformation at each handoff. When disputes come up—especially with FX variance or fee allocation—having the exact snapshot from each system boundary has saved us multiple times. The overhead is minimal compared to trying to reconstruct what happened after the fact.
The distinction between connectivity and operational interoperability is something I wish our integration vendor understood. We can send files all day long, but if invoice references get truncated or FX details disappear between systems, we're still doing manual reconciliation work that should be automated.
We had the exact same problem with a gateway that advertised full SWIFT support. Turned out their API accepted our remittance data but their backend only passed the first 35 characters to the actual MT103. No error, no warning, just silent truncation that we only caught during month-end reconciliation.
Same experience. We discovered our integration was silently dropping the second invoice reference when there were multiple POs on one payment. Everything showed green in monitoring but AP was drowning in supplier inquiries.
The ISO 20022 section is a reality check we needed. Our vendor kept telling us the November cutover would 'solve' our remittance truncation issues, but the format upgrade doesn't fix garbage data coming out of our AP system in the first place.
Exactly. We're dealing with the same thing—our AP exports beneficiary addresses as a single concatenated field, and no amount of ISO 20022 structured messaging downstream is going to parse that cleanly. The real work is fixing the extract logic before the handoff.
We hit this exact issue. The structured fields help once the data is clean, but the lift is all on the mapping side. Ended up writing custom extraction logic to split concatenated address blocks before they even reach the payment file, otherwise the bank just rejects or truncates at their own field limits.
The comment about storing event timestamps AND receipt timestamps separately is something we learned the hard way. We had a bank MT103 come back marked 'rejected' three days after our provider already showed 'completed' in their dashboard, and because we only kept the provider's timestamp we couldn't prove the sequence when finance asked why the payable was still open.
The warning about not treating every positive response as 'paid' hits hard. We had a situation where our treasury team reconciled against debited status for three months before realizing one intermediary bank was holding funds in a suspense account due to missing regulatory codes. By the time we caught it we had twelve payments stuck and vendors threatening to pause shipments.
We went through something similar but it was the provider's status mapping that created the blind spot. They were returning 'completed' once the correspondent bank acknowledged receipt, not when funds actually reached the beneficiary. Now we treat anything upstream of credited-with-evidence as provisional and flag it for manual follow-up if it stays in that state more than two business days.
We had a similar suspense account issue, but ours was a missing beneficiary tax ID for a Brazilian payment. The funds sat for six weeks before the correspondent bank sent a paper notice to our sending bank, who then emailed our relationship manager. By that point the invoice was already marked overdue and our supplier had stopped shipments.
The section on status meanings is the most underrated part of this whole workflow. We've seen providers return 'submitted' when they actually mean 'queued for next-day validation' and it creates chaos in the AR side when customers expect same-day confirmation. Now we force every provider to document exactly what state transition each webhook status represents before we turn on automation.
Exactly this. We had a vendor whose 'accepted' status just meant the file passed schema validation, not that the payment itself was viable. When we started requiring a full state machine diagram upfront, we caught three vendors who couldn't actually tell us when funds left our account versus when they entered theirs.
We built a status reconciliation layer for exactly this. Every provider webhook gets logged raw, then we map to our internal states only after checking the timestamp and comparing to prior events. Saved us from overwriting 'credited' with a delayed 'processing' message more than once.
The section on carrying cost and approval controls through the connection is cut off, but this is actually where most of our payment policy violations happen. We can validate beneficiary details and amounts all day, but if the FX rate or fee structure changes between approval and execution, finance sees a different debit than what was authorized. Would love to see more on how to lock commercial terms at the approval stage and reject execution if they drift.
We solved this by requiring the platform to echo back the locked quote ID and all cost components in the debit confirmation. If those don't match what was approved, we treat it as a new transaction requiring re-approval. Adds friction but the policy compliance is worth it.
We handle this by writing the quote ID, rate, and total estimated cost into the approval record itself, then blocking submission if any of those values differ at execution time. Forces treasury to re-approve if market conditions change, but that's better than discovering overruns during reconciliation.
Curious how others handle the beneficiary validation gap mentioned here. Most providers only validate format, not whether the account actually exists or accepts the currency. Do you run test payments first, or just accept a 2-3% failure rate on new recipients?
We accept the failure rate but flag new beneficiaries for manual review on the second attempt. The article's point about country-specific requirements is exactly why—sometimes the account exists but the provider didn't collect the right supplementary details (tax ID, purpose code, etc.) so it bounces at the correspondent bank level.
We don't do test payments but we do run format validation stricter than most providers offer—basically pre-flight checks against known country rules before submission. Still get about 1-2% rejected at the bank level for reasons that weren't detectable up front, usually regulatory holds or account restrictions the provider can't see.
The point about mapping status to 'paid' is critical. We burned hours reconciling because our middleware treated 'debited' as delivery confirmation, then had to chase down funds stuck at intermediary banks. Now we wait for actual credit evidence or at least a 'funds available' flag before updating the payable.
We had the same problem until we started treating debited as a financial event but not a delivery event. Two separate flags in our ledger now, and reconciliation only closes on credited or a signed MT910 equivalent. The timestamp lag between debit and credit can be days depending on correspondent chains.
Same issue here. We now separate the accounting entry (cash out) from the payable close trigger. The payable stays open until we get MT910 confirmation or equivalent proof from the provider, not just their internal debit event.
Good framing on canonical payout records, but I'd add that your ERP snapshot needs to include the FX rate lock timestamp. We've had disputes where the approved rate in NetSuite didn't match what the payment provider executed, and without that timestamp we couldn't prove whether slippage was our delay or theirs.
We log the FX rate AND the quote expiry in our canonical record for exactly this reason. The other thing that saved us once: capturing whether the rate was client-initiated or auto-accepted by the platform. Turns out our payout system had a 60-second auto-accept window we didn't know about, which explained random slippage on batches that sat in our approval queue.
We've started requiring the provider to return the rate timestamp in every status callback, not just the initial acceptance. Helps when you need to trace whether the quote expired during internal approval routing before submission.