

TDS on Supplier Payment: Rules and AP Automation Controls
Supplier TDS is not a single rate applied at payment release. Finance teams need transaction classification, cumulative threshold tracking, and a deduction trail that starts before cash leaves the bank.
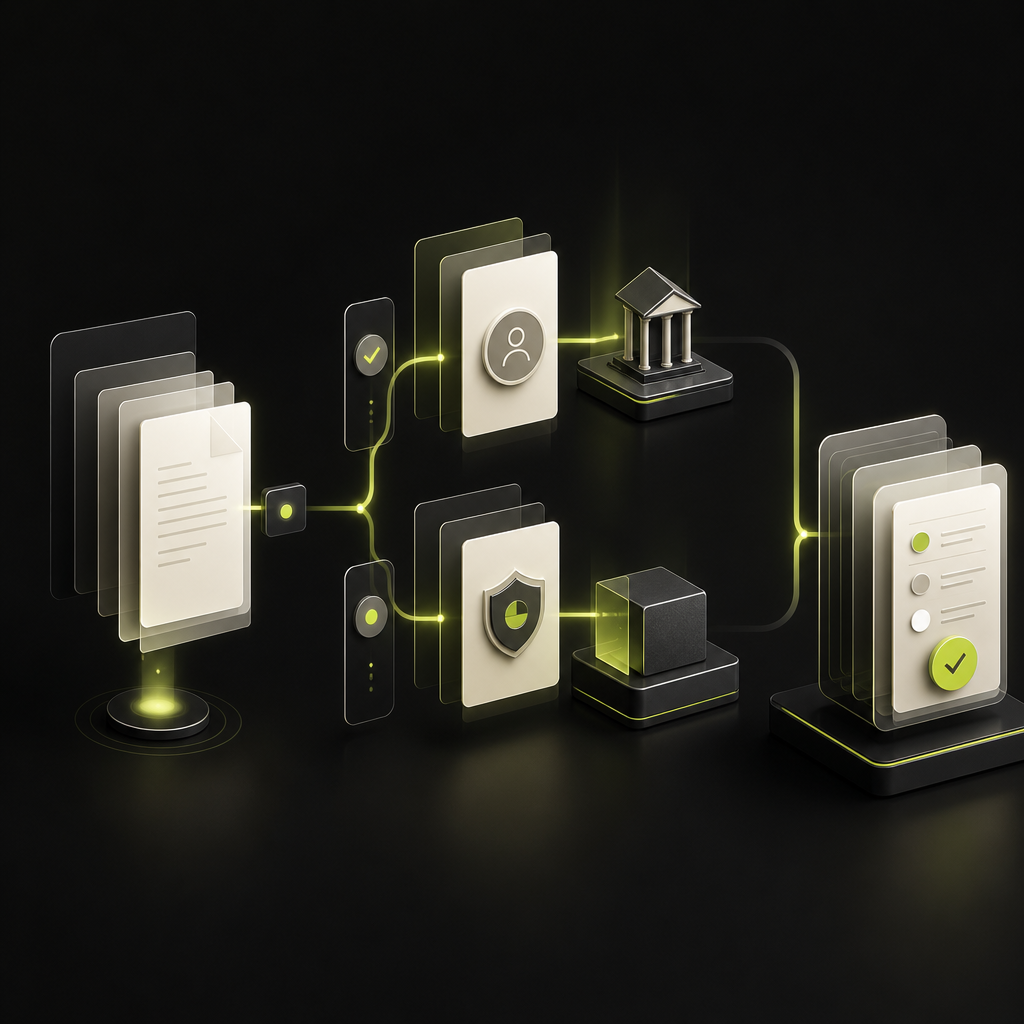
TDS on supplier payment in India depends on what you are buying, who you are paying, and whether your business is required to deduct. For qualifying resident contractor payments, the standard rates are 1% for individuals or Hindu Undivided Families (HUFs) and 2% for other entities. Deduction generally applies when a single payment exceeds ₹30,000 or the financial-year aggregate exceeds ₹1,00,000, at the earlier of credit or payment. These contractor rules do not automatically apply to every goods supplier.
For controllers evaluating AP automation, the operational implication is straightforward: a payment-run tax calculation is too late if the deduction obligation arose when the payable was recorded. The system must connect classification, accounting events, withholding, and settlement.
Scope: India, with an emphasis on resident contractor payments. Legislative references reflect secondary guidance available in October 2026. Confirm current statutory provisions, exceptions, and filing requirements with your Indian tax adviser before configuring production rules.
First classify the payment—not just the supplier
A vendor record labelled “supplier” does not determine TDS treatment. The same counterparty might sell goods, perform installation work, and provide professional advice. Those transactions may require different tax classifications.
Start each decision with these questions:
- Is the payer covered? Establish whether the paying entity has a deduction obligation; do not infer this from the invoice alone.
- Is the payee resident in India? Non-resident payments require a separate assessment rather than the resident contractor rate.
- What is the transaction? Distinguish goods purchases, contractual work, professional or technical services, and commission.
- Does an exception apply? Retain evidence supporting any exemption or special treatment.
The familiar legacy labels include Section 194C for contractual work, Section 194J for professional or technical services, and Section 194Q for qualifying goods purchases. They should not be treated as interchangeable. A goods purchase outside contractor withholding is not necessarily outside TDS altogether.
Keep legacy and current legal references separate
From 1 April 2026, contractor-payment withholding is described in the supplied secondary guidance as falling under Section 393 of the Income-tax Act, 2025, replacing the familiar Section 194C reference. That contractor TDS transition guide reports that the standard rates and thresholds carry forward.
Keep both references searchable in your tax configuration, but attach an effective date to each rule version. A renamed provision should not erase the historical basis for an earlier deduction.
Contractor TDS rates, thresholds, and timing
The following summarizes the standard resident contractor framework, not every category of supplier payment. Tax2win's contractor TDS guide covers Section 194C.
| Rule | Standard treatment | AP control needed |
|---|---|---|
| Individual or HUF contractor | 1% deduction | Validated legal status |
| Other resident contractor entities | 2% deduction | Entity-specific classification |
| PAN not furnished | Generally 20% under the higher-rate rule | PAN exception workflow |
| Single-payment threshold | Exceeds ₹30,000 | Transaction-level test |
| Financial-year threshold | Aggregate exceeds ₹1,00,000 | Cumulative contractor tracking |
| Deduction event | Earlier of credit or payment | Accounting and payment triggers |
| Eligible goods transporter | Conditional exemption | Supporting evidence, not PAN alone |
Threshold wording matters: “exceeds” is not the same as “equals.”
Where the aggregate threshold is crossed after earlier below-threshold transactions, the deduction assessment must include the earlier qualifying amounts—not just the excess over the threshold. That creates a catch-up requirement which invoice-by-invoice calculations can miss.
Transporter exemptions also require care. A valid PAN alone is not a universal exemption for every transport business; the prescribed eligibility conditions and supporting evidence must be checked.
Build TDS into the accounting event
Tax withholding should be a controlled accounting outcome, not a spreadsheet adjustment uploaded beside the bank file. An approval delay does not necessarily postpone the tax obligation, and an advance can trigger deduction before the invoice arrives.
Maintain a transaction-level tax record
For each assessed transaction, retain:
- Paying legal entity, supplier identifier, PAN, residency, and entity type.
- Transaction category and the evidence supporting it.
- Applicable provision, rule version, and effective date.
- Credit date, payment date, taxable base, and deduction rate.
- Cumulative qualifying amount and tax already deducted.
- Exemption evidence, overrides, and the approving person's identity.
- Links to the invoice, accounting entry, payment, and tax remittance record.
Aggregate duplicate supplier records at the appropriate tax-identity level within the deductor's reporting scope. Do not combine unrelated paying entities simply because they share an ERP, or let duplicate vendor IDs fragment one contractor's annual total.
Separate commercial approval from tax approval
The budget owner confirms that the work was authorized and received. The tax reviewer resolves unclear classification, missing PAN information, and exemption claims. These are different decisions.
An invoice approval workflow should route tax exceptions to an accountable specialist without making that specialist approve every routine invoice. Ambiguous legal treatment should not become an unreviewed model decision.
Prevent deduction twice on the same obligation
When an advance has already attracted TDS, the later invoice must reference that deduction. Likewise, payment release should use the withholding already booked rather than calculating the full amount again.
Ask integration teams to demonstrate what happens when an accounting event is retried. A repeated message must not create another withholding entry. This is a financial control requirement, not merely an API reliability feature.
Hypothetical example: crossing the annual threshold
Assume a covered Indian company engages a resident corporate contractor with a valid PAN. Each initial qualifying payment is below the single-payment threshold, and the initial financial-year aggregate is below the annual threshold. Additional work later takes the financial-year aggregate above ₹1,00,000.
The workflow should reassess the cumulative qualifying amount at the applicable 2% rate, account for deductions already made, and identify the catch-up amount. It should not apply TDS only to the portion above ₹1,00,000.
If earlier invoices are already settled, create a visible tax-recovery exception. The tax liability and recovery from the supplier are separate operational questions. An insufficient remaining payable must not make the obligation disappear or silently push an unexplained negative payment into the next bank file.
The supplier communication should explain the affected invoices, withholding basis, and recovery treatment. Preserve the original ledger history rather than rewriting settled transactions to make the current payment look simpler.
Test AP software with tax exceptions, not a clean invoice
The useful buying question is not “Does this platform support TDS?” It is “Which system owns each calculation, posting, remittance, and correction?” An AP platform may orchestrate the process while an ERP or specialist tax system remains the calculation or filing authority.
That division should be explicit. MYND's guidance on TDS in AP and procure-to-pay supports embedding deduction and compliance into the operating process rather than treating them as a year-end exercise.
Use this acceptance checklist during demonstrations:
- Mixed purchases: Can one supplier have different transaction-level tax treatments?
- Threshold crossing: Can the system explain the cumulative base and catch-up deduction?
- Advance and invoice: Does it recognize prior withholding without duplicating it?
- Provision before payment: Can it assess relevant credit events before cash release?
- Missing PAN: Does it flag the higher-rate assessment rather than silently using the standard rate?
- Correction: Can a reversal preserve the original calculation and approval trail?
- Reconciliation: Can finance connect deductions to deposits, reporting records, and supplier certificates?
Use the broader AP platform acceptance checklist to test workflow ownership alongside these India-specific tax cases.
Close the loop after the supplier is paid
A successful supplier transfer does not prove TDS compliance. Finance must separately track tax deducted, tax deposited, reporting completed, and certificates issued. Late deduction, late deposit, and inaccurate reporting are different failures requiring different remediation.
Maintain a tax calendar owned by the tax function, with current rules for the relevant deductor, period, and payment category. Do not hard-code one universal deposit deadline: period-specific exceptions and legislative changes can matter.
The next step is to document your withholding decision flow before choosing software. Identify the authoritative calculation system, the accounting trigger, the exception owner, and the evidence needed to close each obligation. Then evaluate Payouts.com AP Automation for the surrounding invoice, approval, and payment workflow, explicitly verifying how India-specific TDS calculations and statutory reporting will be handled. Automating payment release is useful; automating it without preserving the tax decision is not.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
Invoice Approval Workflow: Build a Matrix That Holds Up
An effective invoice approval workflow defines who can approve, what evidence they need, and when approval must reset. Use this framework to turn an email-based process into enforceable rules.
Accounts Payable Automation Platform: A Buyer’s Acceptance Checklist
The right AP platform should reduce work across the invoice-to-payment cycle—not move it into another queue. Use this acceptance checklist to turn vendor demonstrations into a defensible buying decision.
New Vendor Onboarding Process: Ready for the First Invoice
A completed vendor form is not the same as a supplier ready for invoice processing. Build an onboarding workflow with explicit handoffs, payment controls, and a first-invoice acceptance test.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.