

Virtual Cards for Supplier Payments: From Acceptance to Reconciliation
Virtual cards can connect approved invoices to controlled payments, but supplier acceptance and settlement need their own operating rules. Here is how finance teams can evaluate the economics and manage the full payment lifecycle.
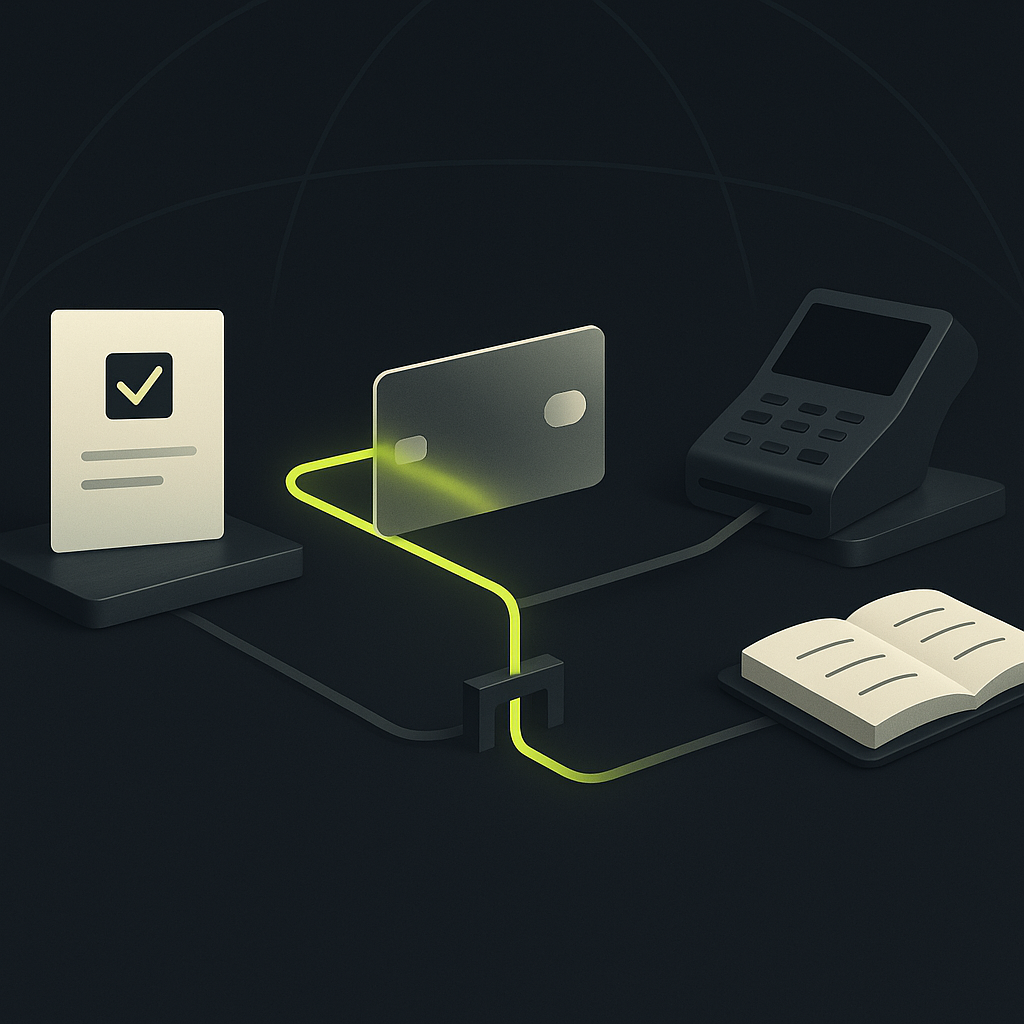
Virtual cards for supplier payments are digitally generated card credentials used to pay approved vendor invoices through card networks. They can provide transaction limits, restricted usage, and invoice-level payment references. They work best when the supplier accepts the specific card product, the economics are agreed, and AP can track the transaction beyond card issuance.
They are not bank transfers, and sending a card number does not mean the supplier has been paid. For international finance teams, the decision is therefore not simply whether to replace wires with cards. It is which invoices qualify, who bears the costs, and what evidence allows AP to close the payable.
How a supplier virtual card payment works
A virtual card typically has a card number, expiration date, and security code without a physical card. Depending on the issuing program, it may be single-use or support multiple transactions within defined limits. Some programs are credit-funded; others require prefunding. Do not assume every virtual card provides working-capital float.
The supplier must be able and willing to process the credential through its merchant payment setup. As Versapay explains in its supplier-side overview, accepting virtual cards involves card processing rather than simply receiving funds into a bank account.
- Approve the invoice: Validate the supplier, invoice, purchase authorization, and payment terms before issuing a credential.
- Create the payment: Associate the card with an invoice or documented invoice group and configure supported amount, usage, and expiration controls.
- Enable collection: Deliver credentials securely or use an agreed integration through which the supplier processes the charge.
- Reconcile the result: Match card transaction events, issuer records, and remittance details to the payable.
Issuance, authorization, capture, and settlement are different events. Authorization approves a charge; capture submits it for clearing. The supplier's acquirer then funds the supplier under its own terms. An issuer transaction record alone does not establish exactly when cash became available in the supplier's bank account.
Qualify suppliers before issuing cards
The first control is acceptance, not a spending limit. A vendor that accepts cards domestically may reject a foreign-issued commercial card, impose contractual conditions, or lack a practical process for handling emailed payment instructions.
Record acceptance by supplier legal entity, receiving location, card product, and transaction currency. A general “cards accepted” flag is too coarse for a global supplier base.
| Qualification check | Evidence to collect | Hold issuance when |
|---|---|---|
| Card acceptance | Confirmation for the intended card product | Acceptance remains unconfirmed |
| Commercial terms | Agreed fees, discounts, and payment date | Costs or terms are disputed |
| Currency compatibility | Invoice and accepted charge currencies | Conversion responsibility is unclear |
| Collection workflow | Named recipient or processing integration | No one owns card processing |
| Capture behavior | Full, partial, or shipment-based charging | Card controls conflict with billing |
| Remittance matching | Invoice references and allocation rules | The supplier cannot identify the invoices |
| Fallback readiness | Verified alternative payment instructions | A failed charge would strand payment |
This qualification process makes cards a selective payment method rather than a blanket mandate. Keep local transfers or wires available for suppliers whose acceptance costs, transaction sizes, or operational requirements make cards unsuitable. The broader corridor routing policy should document those alternatives.
Evaluate economics on both sides of the invoice
Buyer value: more than a rebate
Potential benefits include less manual handling, tighter payment controls, easier matching, and contractual rebates. MineralTree's discussion of virtual cards in AP describes control and reconciliation benefits, but those depend on the surrounding workflow. A card number disconnected from invoice data still creates reconciliation work.
Evaluate the buyer's net benefit as eligible rebates plus supportable processing savings and financing value, less issuer fees, FX costs, financing charges, lost supplier discounts, and exception-handling costs. Use your contract and actual workflow costs rather than a headline rebate percentage.
Credit-funded cards may separate the supplier's collection date from the buyer's cash repayment date. That benefit depends on billing terms, available credit, and repayment discipline. Keep it distinct from supplier invoice terms and confirm the accounting treatment rather than automatically describing it as higher days payable outstanding.
Supplier value: net receipts and collection effort
Suppliers incur merchant acceptance costs and may also face manual processing, settlement delays, or reconciliation effort. Mastercard's supplier-focused discussion frames card acceptance as a balance between buyer preferences and supplier business needs. As a network perspective, it is useful context—not proof that every supplier benefits.
Agree whether card acceptance changes pricing, discounts, or payment timing. Do not assume suppliers can or will pass through processing costs: contractual terms and applicable rules matter. A buyer rebate is not evidence of lower total cost across the relationship.
Cross-border value: identify every conversion
Map the invoice currency, card charge currency, issuer billing currency, and supplier settlement currency. These can differ. Confirm who converts each amount, how the rate is determined, and which cross-border or conversion fees apply.
A card charged in the invoice currency can still create FX costs for the buyer or supplier. Ask for the applicable issuer terms and have the supplier validate its acquiring terms. Compare the resulting cost with an alternative bank payment on the same invoice—not a domestic card benchmark.
Build controls around the entire payment lifecycle
Virtual cards can limit credential exposure, but they do not validate the underlying invoice. A fraudulent invoice can pass through a tightly restricted card just as easily as a bank payment if approval controls fail.
Keep invoice validation, supplier changes, approval, and credential release separate. Connect payment eligibility to the approved record in your AP automation workflow, rather than issuing cards from an independently maintained spreadsheet.
Check what the issuer actually enforces
Distinguish descriptive metadata from authorization controls. Storing a supplier name against a card does not necessarily prevent another merchant from charging it. Ask whether the program supports merchant-specific restrictions, merchant-category restrictions, amount limits, transaction counts, and expiration rules—and how each behaves.
Also confirm whether controls apply in the transaction or billing currency. An exact limit can conflict with currency conversion or split shipments. Do not loosen limits automatically to solve declines; first determine whether the invoice or payment configuration needs correction.
Treat unused cards as unresolved payments
A delivered credential may sit unprocessed while the invoice approaches its due date. Track issued-but-unused cards separately from authorized and captured transactions. Assign an owner to follow up with the supplier and maintain a due-date-aware escalation queue.
Define the evidence required for each accounting transition. Card issuance should not, by itself, mark an invoice paid. Preserve the connection between invoice ID, payment instruction, card reference, transaction events, and the eventual issuer liability or cash movement.
Prevent duplicates during fallback
Hypothetical exception: A supplier reports that its virtual card cannot be processed and asks for a wire. AP sends the wire, but a previously authorized card charge later clears. The invoice has now been paid twice.
Before switching rails, stop further card use where supported and investigate authorizations, captures, and pending events. Card cancellation alone may not eliminate exposure to an already authorized transaction. Require a documented exception decision when the original transaction remains uncertain, and link both payment attempts to the same invoice.
For refunds, confirm how credits to expired or closed credentials are handled. Route them back to the original invoice record rather than treating an unmatched credit as unexplained cash.
A practical rollout checklist
- Select by fit: Start with willing suppliers whose charging patterns and invoice currencies suit the program.
- Document acceptance: Confirm the card product, costs, processing owner, and agreed payment terms.
- Test realistic exceptions: Include partial capture, declines, unused credentials, refunds, and a request to switch rails.
- Protect credentials: Use controlled delivery and restricted access; keep sensitive card data out of general AP notes.
- Validate integration behavior: Ensure retries do not create duplicate cards or duplicate payment instructions.
- Prove reconciliation: Trace approved invoices through transaction events, issuer records, and ledger entries.
- Measure completion: Track eligible-spend acceptance, unused-card aging, exceptions, reconciliation effort, and realized net benefit.
Make cards an invoice-level decision
The strongest virtual card program is not the one issuing the most credentials. It is the one that pays suitable invoices on agreed terms, preserves supplier relationships, and closes each payment with defensible evidence.
Use acceptance, net economics, currency compatibility, and lifecycle visibility as release conditions. To assess the card component of that workflow, explore Payouts.com corporate and virtual cards and map the required controls against your supplier payment process before expanding issuance.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
3 commentsRelated resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
ACH Wire Transfer Time: A Cutoff and Escalation Playbook
ACH and wires run on different clocks. Learn how to set release deadlines, identify where a payment is waiting, and decide whether an urgent replacement is safe.
Tax Reporting for Independent Contractors: Reconcile Global Payments
Reliable contractor tax reporting depends on connecting each payment to the right recipient, jurisdiction, and reporting treatment. Here is how finance teams can build a defensible process across currencies and payment rails.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
I appreciate the emphasis on reconciliation beyond issuance. Too many AP teams treat card issuance as payment completion, but authorization is not settlement. We've had cases where a supplier authorized a charge but didn't capture for weeks, leaving the payable open and our controller asking why we showed it as paid in the ERP. The gap between issuer transaction records and actual supplier cash receipt is real and often ignored in vendor pitches.
The qualification table is exactly what we needed when we rolled out virtual cards last year. We hit every single one of those edge cases—suppliers who said they accepted cards but then rejected commercial cards, suppliers who could only process in one currency, and one who just forwarded the card details to their AR team who had no idea what to do with them. Now we maintain a supplier acceptance matrix by entity and product type before we even generate the credential.
The economics section is critical but I'd add one more cost: the internal effort to manage exceptions when suppliers partially capture or split charges across shipments. Our rebate looked great on paper until we factored in the AP analyst time spent chasing down mismatched authorizations and asking suppliers to reprocess failed charges.