

When Does Amazon Pay Sellers? Trace a Pending Payout
A scheduled Amazon payout is not the same as spendable cash. Learn how to trace proceeds through delivery-based reserves, disbursement, and bank settlement—and identify what is blocking payment.
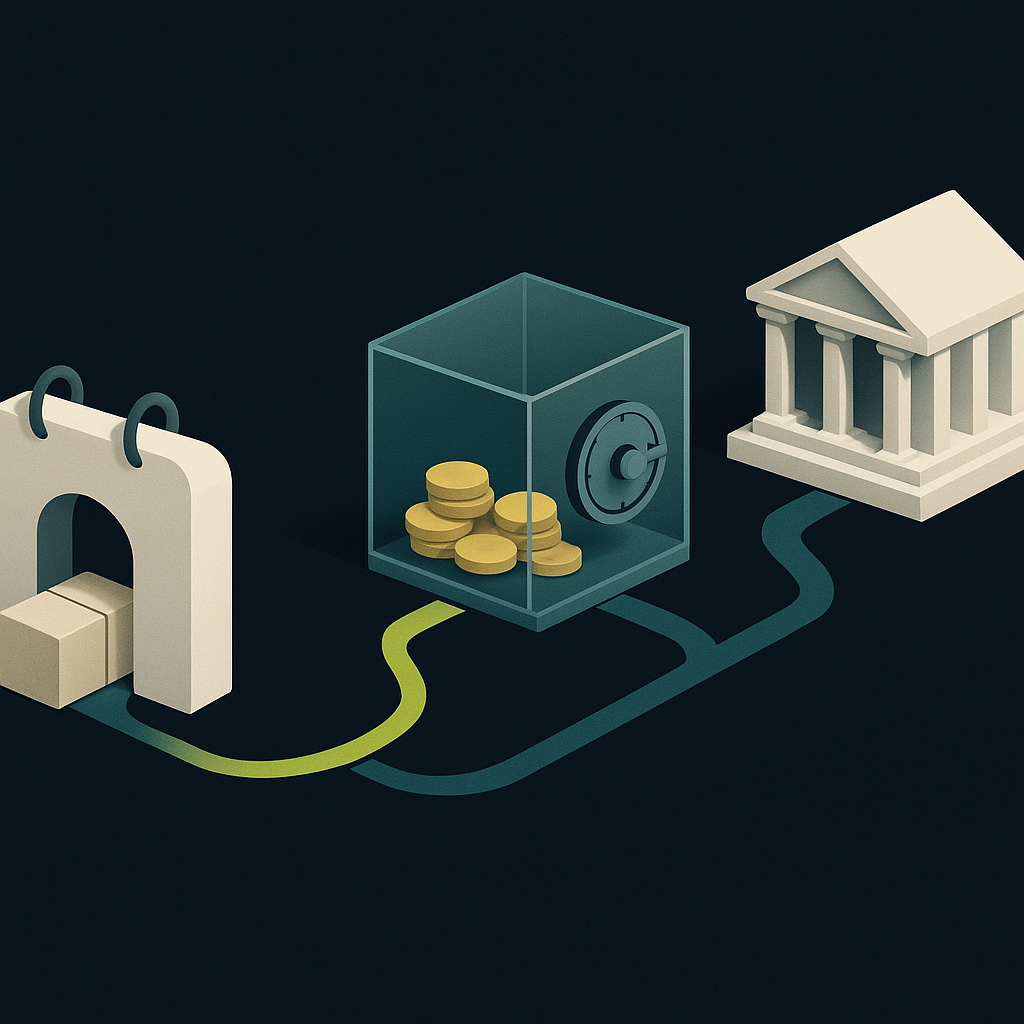
Amazon generally settles seller accounts every two weeks, but that does not mean each sale reaches your bank within two weeks. Only eligible proceeds can be disbursed after fees, refunds, and applicable reserves. After Amazon initiates payment, funds can take up to five business days to appear in your bank account, according to Amazon’s explanation of seller payments. Your account’s Payments dashboard is the place to confirm its next scheduled disbursement.
To answer “when does Amazon pay sellers” for a specific order, trace three separate events: when proceeds become eligible, when Amazon sends them, and when the receiving bank credits them. A delay at each stage requires a different response.
This guide focuses on third-party marketplace sellers, primarily Amazon.com in the United States. It does not cover Amazon Associates commissions, AWS Marketplace disbursements, Amazon Pay merchant processing, or wholesale vendor invoice terms.
Start by locating the money, not counting days since the sale
A sales total is not a payout promise. An order may appear in your reporting while its proceeds remain unavailable for transfer. Conversely, Amazon may have sent a payment that your bank has not yet posted.
Use this diagnostic map before opening a support case or changing your cash forecast. Labels can differ across marketplaces and account interfaces.
| What you see | Likely stage | What to check next |
|---|---|---|
| Order proceeds are deferred | Eligibility not reached | Delivery date and release information |
| Balance exists but is unavailable | Reserve or account restriction | Reserve details and account notices |
| Available balance, no transfer | Awaiting disbursement | Scheduled date and request options |
| Transfer initiated, no bank credit | Bank processing | Transfer reference and destination |
| Payment failed or returned | Destination or processing exception | Failure reason and deposit details |
The important distinction: eligibility is not disbursement, and disbursement is not bank receipt. A faster transfer method cannot solve a reserve hold.
How delivery-based reserves affect your payment date
DD+7 starts from delivery—not the order date
Under a delivery-date-based reserve, commonly called DD+7, proceeds are generally held until seven calendar days after delivery before becoming eligible for disbursement. “DD” means delivery date, not disbursement date.
Webgility’s explanation of Amazon’s payout schedule changes describes the March 12, 2026 transition affecting legacy North American accounts. Many sellers were already on delivery-based terms. Treat that transition date as context, not proof that every marketplace or account has identical terms; confirm the reserve policy and notices applicable to your account.
Once a transaction clears its delivery-based hold, it still needs to enter an eligible disbursement. If it becomes available after the relevant cutoff, it may miss that transfer. Bank processing follows afterward.
For orders without confirmed tracking, an estimated delivery date may be used under the applicable policy. Check the date Amazon actually uses rather than assuming your shipping date started the clock.
FBA and seller fulfillment change the delivery step
Fulfillment by Amazon and merchant fulfillment can produce different order-to-cash timelines because transit times and delivery visibility differ. Faster delivery may bring the eligibility date forward, but it does not eliminate the reserve or guarantee an immediate bank deposit.
A universal “FBA pays in this many days” estimate therefore obscures the real variables. For a particular order, inspect delivery evidence, the applicable hold, disbursement timing, and the receiving bank separately.
Other reserves and restrictions can still matter
Delivery-based deferral is not the only reason money may be unavailable. Amazon may retain funds to address refund, claim, or chargeback exposure, and account verification or deposit-method issues can also interrupt payment. SellerEngine’s guide to reserves and disbursement issues explains why reserve balances and payment holds need separate investigation.
Do not turn a reserve balance into a fixed additional number of days without evidence. Also, do not subtract the same held proceeds twice when reconciling reports that display them in different views.
Find your next actionable payment date in Seller Central
- Choose the correct marketplace. Confirm which store, currency, and legal entity generated the proceeds.
- Open the Payments dashboard. Note the available balance, reserve or deferred amounts, and next scheduled disbursement information.
- Inspect the underlying transactions. Locate the order or group of orders you expected to be paid. Check delivery information and any displayed release date.
- Review account notices. Look for verification requests, deposit-method changes, or restrictions that explain why otherwise eligible funds have not moved.
- Check transfer history. Establish whether Amazon actually initiated the payment. Save the reference, amount, currency, destination account, and status.
- Match the bank receipt. Reconcile the credit to the transfer record, allowing for documented currency conversion or deductions.
This sequence prevents a common operational error: asking the bank to locate money that Amazon has not released, or asking Amazon to remove a reserve when the transfer is already in transit.
What can—and cannot—make a payout faster?
If your account offers an on-demand disbursement request, it can help move available funds sooner than waiting for a scheduled transfer. It does not make deferred proceeds available or override an account restriction. Check the conditions shown in your account before relying on it.
Likewise, faster bank-transfer options address the last part of the journey, not the delivery-based hold.
For eligible sellers managing U.S.-store proceeds, Amazon Seller Wallet provides another way to manage funds after disbursement. Amazon states that U.S. sales proceeds can appear in Seller Wallet within minutes of disbursement. That is wallet availability—not a promise that a subsequent external bank transfer has completed.
Before choosing an option, identify the delay you are trying to remove: waiting for eligibility, waiting for a transfer run, or waiting for bank credit. Compare costs and restrictions at that specific stage.
Cross-border sellers need a second reconciliation
When marketplace proceeds and operating expenses use different currencies, knowing when Amazon sends money is only half the answer. Finance also needs to know which currency arrives, where conversion occurs, and when the funds can cover local obligations.
- Confirm the payout destination. Check account ownership, supported country, currency, and required bank details against the marketplace’s requirements.
- Locate the conversion step. Establish whether Amazon, a receiving provider, or the bank converts the proceeds.
- Record the net receipt. Compare the disbursed amount with the credited amount using the actual conversion and fee records.
- Separate onward transfers. Money received into a collection account is not necessarily available yet in the account used to pay suppliers.
Do not assume every foreign-marketplace payout becomes U.S. dollars or that every international payment travels by wire. The configured receiving arrangement determines the route.
For the bank-processing portion, use the same discipline described in our guide to building reliable payout settlement estimates: distinguish initiation, processing, and beneficiary availability. Multi-currency infrastructure such as Global Accounts can support broader collection and treasury workflows, but confirm Amazon acceptance and account eligibility separately.
Turn payment status into a usable cash forecast
Maintain separate operational categories for deferred proceeds, available proceeds, transfers in transit, and cleared bank cash. These are forecasting categories, not a substitute for your accounting recognition policy.
For each expected receipt, capture the marketplace, currency, source transaction, eligibility information, scheduled transfer, transfer reference, and actual bank credit. Mark dates as confirmed or estimated. This makes a missed receipt explainable rather than simply “late.”
Hypothetical example: an order clears its delivery-based hold after the scheduled transfer cutoff. Its proceeds remain available for a later disbursement, while an earlier batch has already reached the bank. The right response is to revise that order’s expected receipt—not escalate the earlier batch as missing or assume all sales have been withheld.
Before committing supplier payments, test whether cleared cash covers the obligation if the expected Amazon receipt slips. If it does not, agree on a funding or rescheduling decision before payment release. An AP automation workflow can organize invoice approvals and payment execution, but it cannot shorten Amazon’s reserve period.
Next step: trace one missing receipt end to end
Choose one payment you expected to receive and identify its current stage. If it is deferred, inspect delivery and release information. If it is available, check disbursement timing and restrictions. If it has been sent, use the transfer reference to investigate bank receipt.
When escalating, provide the marketplace, affected transactions, expected and actual status, amount, currency, and relevant dates through a secure support channel. The most useful question is not simply “When will Amazon pay?” It is “Which condition must be satisfied before this money can move to the next stage?”
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Related resources
Payout Settlement Times by Country: Build Reliable Payment ETAs
An instant domestic rail does not make an international payout instant. Use this country reference and operating framework to set payment ETAs that account for funding, calendars, and recipient-bank availability.
Digital Payment Agents: Turning Payout Data Into Decisions
Digital payment agents can coordinate cross-border payouts, but their decisions are only as reliable as the data behind them. Build around evidence freshness, corridor requirements, and verifiable payment outcomes.
Global Cross Border Payments Statistics: Benchmarks for Finance
Global payment statistics reveal persistent cost and speed gaps, but not every headline is a useful benchmark. Here is how finance teams can turn the data into a meaningful payout scorecard.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Discussion
0 commentsBe the first to join the discussion.