

How to Pay an International Invoice: An AP Execution Guide
Paying an overseas invoice requires more than entering bank details. Build an invoice-level payment record that connects approval, currency conversion, transfer execution, and accounting.
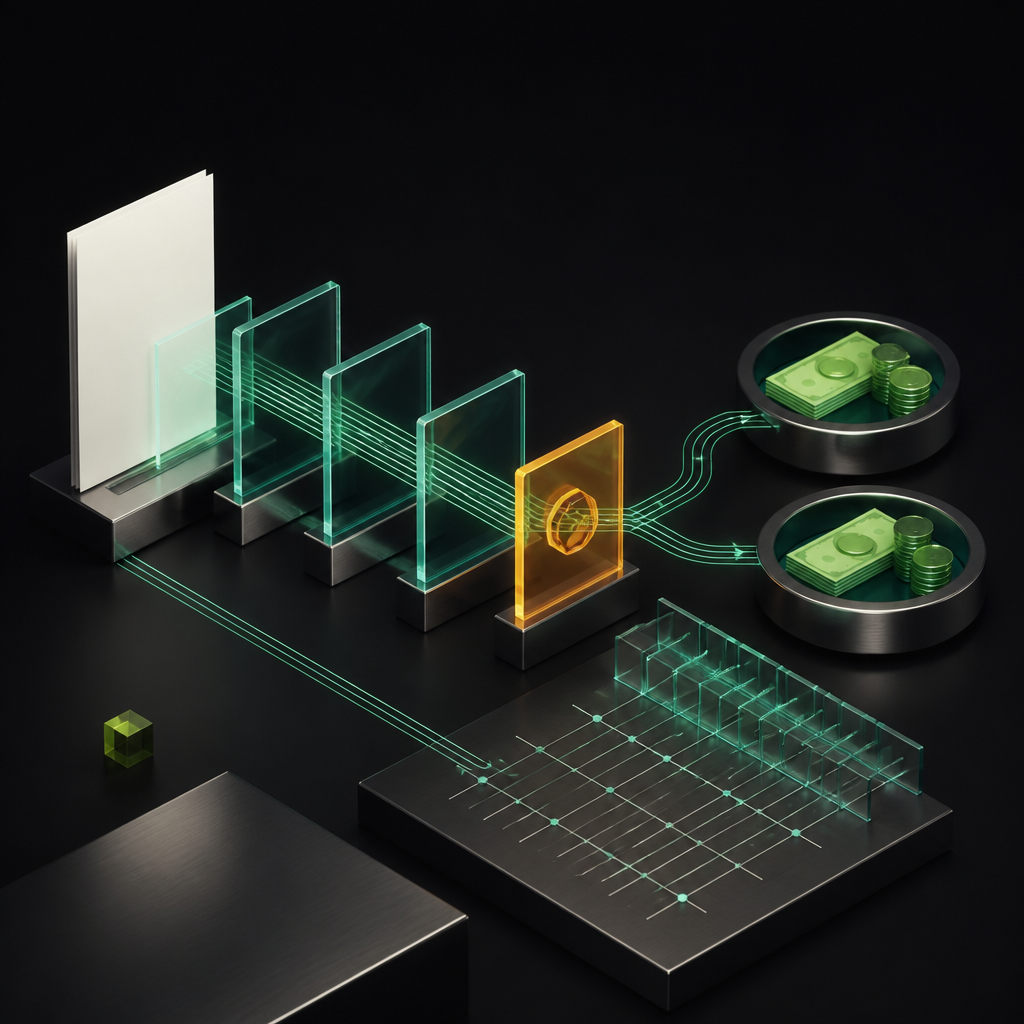
To pay an international invoice, validate the bill, independently verify the supplier’s payment details, confirm the invoice currency and applicable tax treatment, and choose a supported payment method. Then approve the total funding cost, submit the transfer through your business bank or payment platform, and reconcile the payment against the invoice.
For accounts payable teams, the challenge is keeping those steps connected. An approved invoice is not necessarily ready for payment, and a submitted transfer is not proof that the supplier received funds. This guide focuses on the individual invoice: what to collect, what to approve, and what evidence to retain through reconciliation.
1. Build a complete invoice payment record
Start with the underlying obligation, not the bank portal. Match the invoice to the purchase order, contract, receipt of goods, or accepted service milestone. For non-PO invoices, obtain approval from the responsible budget owner and document the accounting allocation.
Check whether the invoice has already been paid, credited, partially settled, or covered by an advance. International invoices can enter AP through several channels, making a forwarded PDF look like a new obligation. Your duplicate invoice checks should account for supplier aliases and inconsistent invoice-number formatting.
Capture the following information in a structured record rather than leaving it inside email attachments.
| Information | What AP should establish | Hold payment when |
|---|---|---|
| Invoice identity | Supplier, invoice number, date, paying entity | Duplicate or entity mismatch is unresolved |
| Commercial basis | Contract or PO, delivery evidence, approval | Amount or milestone is disputed |
| Amount and currency | Currency code, tax, credits, open balance | Currency or balance is ambiguous |
| Beneficiary details | Verified account holder and routing data | Account change is unverified |
| Payment conditions | Due date, fee allocation, required reference | Instructions conflict with agreed terms |
| Tax and compliance | Applicable documentation and review status | Required review remains incomplete |
Use an explicit currency code such as USD or CAD, not a bare dollar symbol. The supplier’s location does not establish the invoice currency, and its bank account may accept a different currency from the one billed.
2. Verify bank details and jurisdiction-specific requirements
Obtain the beneficiary’s legal name, account details, bank information, and any required payment reference. The required routing fields depend on the destination and payment method: an IBAN where supported, a SWIFT/BIC for relevant international bank transfers, or local account and clearing codes.
Do not treat bank details printed on an invoice as independently verified. Confirm new or changed instructions using a trusted contact channel already on file—not a phone number supplied in the change request. Keep the verification evidence with the supplier record.
A structurally valid account number does not prove account ownership. If the beneficiary differs from the contracting supplier, investigate the relationship and obtain appropriate authorization before release.
Separate payment data from tax decisions
Tax documentation, withholding, sanctions controls, and purpose-of-payment requirements depend on the payer, payee, income type, and jurisdictions involved. Tipalti’s international AP overview describes tax and regulatory compliance as part of managing overseas payables, alongside currency and payment-method selection.
For US payers, an appropriate W-8 form may be relevant for documenting foreign status. Do not assume that every foreign invoice requires withholding or Form 1042-S reporting. Have the tax owner establish the applicable treatment, including income sourcing and any treaty considerations. Bank acceptance is not a substitute for that determination.
3. Choose a payment method the receiving account supports
Ask the supplier which methods and currencies its account can receive, then confirm that your bank or provider supports that exact route. A platform is the service layer; the underlying transfer may still use a local clearing system or correspondent banks.
- International bank transfer: Useful when the supplier requires a bank wire or local payout is unavailable. Confirm routing instructions, intermediary requirements, fee allocation, and the expected delivery window.
- Local bank payout through a cross-border provider: Consider this when the provider can deliver the invoice currency into an eligible local account. Validate transaction limits and whether the invoice reference survives delivery.
- Card payment: An option only if the supplier accepts business card payments. Check any surcharge, currency conversion, and how the supplier will allocate the receipt.
As BVNK explains in its discussion of SWIFT alternatives, SWIFT is a messaging network rather than the mechanism that itself settles funds. A fast payment instruction therefore does not establish when the beneficiary can use the money.
Compare delivery estimates for the actual route, including funding availability, cutoffs, holidays, and possible review. Do not plan around a universal international-transfer timeline.
4. Approve the total cost—not just the invoice amount
Before release, obtain a payment quote showing the funding currency and amount, conversion rate, explicit fees, expected recipient amount, and quote expiry. Confirm whether the recipient amount is guaranteed or estimated.
Compare quotes on the same basis: the same invoice currency, intended recipient amount, funding currency, and delivery requirement. A low transfer fee can be offset by a less favorable exchange rate.
Clarify who bears sending, intermediary, and receiving-bank charges. Where the supplier expects the invoice amount in full, ask the provider whether its fee arrangement actually protects that outcome. Do not assume selecting a sender-pays option eliminates every possible deduction.
Exchange-rate changes can also alter the functional-currency cost between recognition and settlement. Stampli’s guide to foreign exchange in AP discusses this currency exposure and forward contracts as a potential management tool. Hedging belongs under treasury policy, not an improvised AP decision at payment time.
Separate commercial approval from payment release. The budget owner approves the expense; the authorized payment approver reviews the funding requirement and execution conditions. Configure approval policies so material changes to the beneficiary, amount, currency, or payment cost trigger renewed review.
5. Submit once, then track the payment separately
In the bank portal or payment platform, select the verified beneficiary, enter the approved amount and currency, supply required purpose information, and include a usable invoice reference. Review the final confirmation screen against the approved record before submission.
Save the provider transaction identifier immediately. Maintain separate invoice and payment-attempt records: the invoice represents the obligation, while each attempt records execution and status.
If submission times out, investigate the existing attempt before creating another. A browser error is not proof that the provider rejected the instruction. Where APIs support idempotency, use it to prevent repeated requests from creating duplicate payments.
Send remittance advice with the invoice allocation, currency, amount, and payment reference. Describe the status accurately: submitted, processing, credited, returned, or another provider-defined state. Do not label a submission receipt as beneficiary confirmation.
6. Reconcile the invoice, cash movement, and FX difference
Match the supplier invoice to the payment allocation, provider record, and bank or account statement. Separate the invoice settlement from transfer fees and currency differences under your accounting policy. If settlement spans reporting periods, apply the appropriate foreign-currency remeasurement treatment.
For partial payments or batches covering several invoices, retain explicit allocations. A single cash debit is not enough to establish which liabilities were discharged.
Hypothetical exception: A supplier’s invoice passes commercial approval, but its attached bank instructions differ from the verified supplier record. AP holds payment for verification. When verification is complete, the original FX quote has expired. The team obtains a new quote and checks whether the changed funding cost requires approval before submitting. Neither invoice approval nor bank verification alone authorizes the final transfer.
Use the workflow to evaluate AP automation
When comparing systems, ask vendors to demonstrate one foreign-currency invoice through capture, approval, execution, and reconciliation—including an exception. This is more revealing than a generic payment dashboard.
- Can capture distinguish invoice currency from an ambiguous currency symbol?
- Does a bank-detail change block release without erasing commercial approval?
- Can the system retain the approved quote and detect material changes?
- Can operators investigate an uncertain payment status without resubmitting?
- Can accounting retrieve invoice allocations, fees, and FX differences together?
Measure cost per completed international invoice using AP labor, exception handling, platform costs, payment charges, and conversion costs. Keep those categories visible: reducing manual entry does not necessarily reduce FX expense, and a cheaper transfer can create costly reconciliation work.
Final release checklist
- Commercial obligation and outstanding balance confirmed.
- Beneficiary independently verified; changes resolved.
- Currency, routing details, and required documentation complete.
- Applicable tax and compliance decisions recorded.
- Funding, quote, fees, and delivery expectations approved.
- Payment reference and duplicate-submission controls ready.
- Tracking, remittance, and reconciliation owners assigned.
The goal is a traceable path from invoice to settled liability—not simply a successful portal submission. Explore Payouts.com AP Automation to connect invoice capture, approvals, and payment, and use this checklist to structure a demonstration around your actual international invoice requirements.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
3 commentsRelated resources
Duplicate Invoice Detection: Evaluate the Control, Not the Alert
A duplicate alert is not the same as a prevented payment. Learn how to evaluate matching accuracy, exception handling, and payment-release controls before choosing AP automation.
Supplier Payment System: Define What Each System Owns
A supplier payment system should connect approved liabilities to controlled payments and reliable accounting. Before choosing software, define which system owns each record, decision, and exception.
Supplier Payment Reporting: Build an Audit-Ready AP Dataset
Supplier payment reports are only as reliable as the invoice and payment events behind them. Learn how to build a traceable reporting dataset and test whether AP automation can produce defensible disclosures.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
How are you handling the quote expiry piece in practice? Our treasury team gets a rate quote, routing it through three approval layers takes 18-24 hours, and by then the quote has expired or the rate has moved 2%. We end up either rushing approvals (not great) or re-quoting and restarting the approval cycle. Would love to hear if anyone has solved this without just giving AP broader discretion on FX exposure.
The currency code clarity is something we learned the hard way—had an invoice that said 'dollars' and our system defaulted to USD, but the supplier's Canadian account expected CAD. Bank accepted it as USD, supplier got shorted on the conversion, and we spent three weeks reconciling the shortfall and sending a second payment. Now we reject any invoice that doesn't explicitly state the three-letter currency code.
The point about structurally valid account numbers not proving ownership is huge. We caught a BEC attempt last year when finance re-verified a 'bank change' email using our original contact. The new IBAN was perfectly formatted and would have passed through our automated validation, but it belonged to a completely different entity. Now we require dual-channel verification for any payment detail changes over $5k.