

How to Pay International Vendors: From Invoice to Transfer
Paying an overseas vendor starts with the invoice currency, receiving account, and payment obligations—not the transfer button. Follow this practical workflow to choose a method, prepare the payment, and close the invoice.
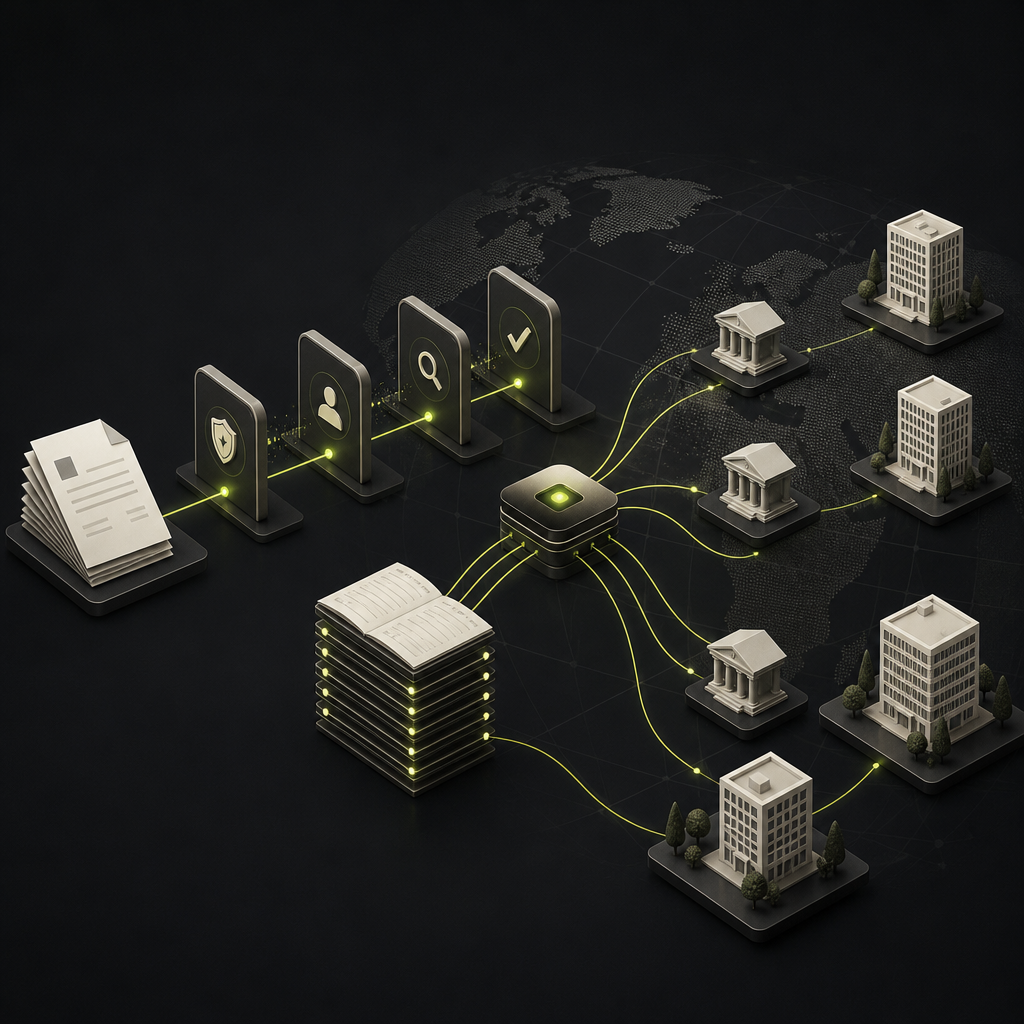
To pay international vendors, confirm the invoice and agreed currency, verify the vendor’s banking and tax information, choose a supported payment method, compare the total cost, and release the transfer through an approved provider. Then track delivery and reconcile the payment against the invoice, including fees and exchange differences.
For finance teams paying hundreds of overseas recipients, the challenge is making those decisions consistently. A software subscription, an inventory deposit, and a professional-services invoice may require different documentation and payment methods—even when the vendors share a country.
The practical starting point is a payment brief for each obligation: what you owe, whom you owe, which currency settles the debt, where the money must arrive, and what evidence authorizes payment.
1. Establish what the invoice requires
Before requesting a transfer quote, match the invoice to the contract or purchase order and confirm delivery or the agreed payment milestone. Identify whether the payment is an advance, a final balance, a recurring charge, or a credit-adjusted amount.
- Payee: Does the invoicing legal entity match the approved vendor?
- Currency: Is the debt denominated in the vendor’s local currency, your functional currency, or another agreed currency?
- Timing: Does the due date mean payment initiation or receipt of funds?
- Charges: Who bears transfer fees and any receiving-bank deductions?
- Reference: What invoice or customer-account reference does the vendor need to allocate the payment?
Do not change payment currency simply because your bank offers a convenient conversion. A USD payment does not necessarily settle a euro-denominated invoice unless the vendor accepts the conversion basis. Likewise, local currency is not automatically preferable if the vendor has contracted for USD and holds a compatible account.
2. Choose a method the vendor can actually receive
Common options include international wires, local bank transfers, cards, and electronic wallets. Airwallex’s overview of international vendor payments describes this broader method landscape. The right choice depends on account compatibility, invoice terms, cost, and the receiving business’s acceptance policies.
The table below gives editorial guidance on practical fit, not provider rankings or guaranteed delivery times.
| Method | Best for | Main limitation | Check before release |
|---|---|---|---|
| Local bank payout | Recurring supported-currency invoices | Country, currency, and account restrictions | Local clearing eligibility |
| International wire | Vendors requiring cross-border bank receipt | Potential correspondent fees and reviews | Currency, routing, and charge instructions |
| Credit or virtual card | Card-accepting subscriptions and purchases | Acceptance, surcharges, and FX treatment | Vendor consent and card limits |
| Business wallet | Vendors already using that wallet | Withdrawal costs and account restrictions | Business eligibility and cash-out route |
| Transfer from a local currency balance | Recurring obligations in a held currency | Funding and balance-management overhead | Available funds and outbound rail |
A local currency balance is a funding arrangement, not a payment rail. The actual transfer still travels over a supported network. Similarly, “Global ACH” generally describes a service using local clearing systems; it is not one worldwide ACH network.
Do not infer speed from the method’s name. Ask the provider for an estimate covering funding, conversion, screening, bank cutoffs, and recipient credit. For repeatable method selection, use a documented local-rails-versus-SWIFT routing policy.
3. Collect details for the specific receiving account
Request banking instructions through a controlled onboarding channel rather than copying details from an email thread. Capture the beneficiary’s legal name, bank country, account currency, account identifier, and the routing information required by the selected method.
Country alone does not determine the required fields. A vendor’s domestic-currency account and foreign-currency account may use different instructions.
- Euro payments through SEPA: Typically use an IBAN for an eligible account; euro denomination alone does not establish eligibility.
- UK domestic transfers: Commonly use a sort code and account number.
- US ACH payments: Require an ACH-compatible routing number and account number; wire instructions may differ.
- International wires: May require a BIC/SWIFT code, beneficiary address, and intermediary-bank details.
- Other corridors: May require local bank or branch codes, tax identifiers, payment-purpose information, or supporting documents.
These are examples, not complete country specifications. Validate requirements against the provider’s current country, currency, and method-specific schema.
Check format and account compatibility, but recognize that valid formatting does not prove ownership. Verify new or changed instructions through a known vendor contact using independently held contact details. Payments to a different legal entity, including a factor or collection agent, need documented authorization and review.
4. Resolve tax and compliance questions before release
Separate vendor identity checks, sanctions obligations, and tax treatment. Passing one does not establish compliance with the others. Apply screening and escalation procedures appropriate to the payer, provider, jurisdictions, counterparties, and transaction.
For US payers, foreign-vendor documentation depends on the payee and payment. W-8BEN generally documents foreign individuals, while W-8BEN-E generally applies to foreign entities; other forms can apply. Duke University’s foreign-vendor documentation guidance illustrates why payment classification and documentation must be considered together, although its procedures are institution-specific.
Do not treat every foreign invoice as subject to the same withholding rule. Goods, services, royalties, and other payments can receive different treatment. Services performed entirely outside the United States are generally foreign-source, but the facts and applicable reporting rules still matter. A W-8 form does not itself create an exemption, and a missing form does not make every overseas payment subject to an identical withholding rate.
Have your tax adviser establish the relevant documentation, withholding, and reporting rules. Non-US payers need their own jurisdiction-specific analysis.
5. Compare quotes on an equivalent basis
The advertised transfer fee is only part of the cost. Corpay’s explanation of wire transfer fees describes how transfer charges, intermediary costs, and FX pricing can affect the overall expense.
Ask each provider to quote the same beneficiary amount, receiving currency, funding method, and delivery requirement at approximately the same time. Capture:
- The total debit from your funding account.
- The exchange rate, its expiry, and any separately stated conversion fee.
- The amount expected to reach the vendor.
- Whether recipient or intermediary deductions remain possible.
- The estimated credit date and conditions that could delay it.
- Return, investigation, and cancellation charges.
For wires, confirm whether available charge instructions allocate fees to the sender, share them, or deduct them from the beneficiary’s proceeds. Do not assume a sender-pays instruction guarantees the exact receipt amount without provider confirmation.
Holding recurring invoice currencies through multi-currency global accounts can reduce repeated conversions when matching funds are available. The tradeoff is liquidity spread across balances and exposure to currency movements while funds are held.
6. Approve, fund, and send the payment
Keep invoice approval separate from payment release. Approval of a purchase does not authorize subsequently changed bank details, an unreviewed FX quote, or a different beneficiary.
At release, check available funding, the approved beneficiary record, the amount, the currency, and duplicate-payment controls. For batches, validate each payment individually: a successfully uploaded file does not mean every instruction was accepted.
Maintain a durable payment identifier linking the invoice to each submission attempt. If a request times out, check its status before resending. A technical timeout is not proof that no money moved.
Send remittance advice with invoice references, payment currency, amount, and an appropriately qualified arrival estimate. Avoid describing an initiated transfer as received.
7. Reconcile the obligation, not just the bank debit
Connect the invoice, approved payment, provider transaction, bank movement, fees, and any return. Distinguish provider acceptance, processing, recipient credit, and failure using the evidence available for that method.
Record FX differences and charges under your accounting policy. If the vendor reports a shortfall, investigate deductions and conversion before issuing another payment. A rejected transfer should reopen the payment workflow without creating a second payable.
At scale, AP automation should help connect invoice capture, approvals, and payment records. The essential control is preserving that relationship through exceptions—not merely generating a payment file.
A reusable international payment checklist
Attach this checklist to each payment brief, with the evidence and responsible owner:
- Invoice, contract, and delivery or milestone evidence agree.
- Settlement currency, due-date meaning, and fee responsibility are clear.
- Beneficiary identity and banking instructions are verified.
- Account details meet the chosen method’s current requirements.
- Applicable tax, sanctions, and documentation questions are resolved.
- Total debit, expected receipt, and delivery estimate are approved.
- Funding is available and duplicate-submission controls are active.
- Remittance, tracking, reconciliation, and exception ownership are assigned.
The best way to pay international vendors is to make each obligation payment-ready before choosing the transfer. Start with your next batch: build the payment brief, identify missing evidence, and compare methods only for eligible accounts. Once that process is consistent, evaluate Payouts.com’s payout automation against the corridors, currencies, and controls your vendors actually require.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
40 commentsRelated resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
QuickBooks Online Supplier Payment on Account: A Guide
A supplier advance should remain traceable until the invoice arrives—not become a duplicate expense or a second payment. Here’s how to record, allocate, and reconcile it in QuickBooks Online.
Affiliate Account Meaning: The Profile Behind Commission Payments
An affiliate account connects a partner’s referrals to commission records and payment settings. It is not automatically a bank account, a withdrawable balance, or proof that payment is due.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The instruction to verify new banking details through independently held contact details is critical, but in practice who actually owns that contact list? In our org it's split between procurement, AP, and sometimes the original requester, and there's no single source of truth. We've had cases where AP calls a number from the invoice itself, which defeats the whole point.
The framing in the intro—'payment brief for each obligation'—is exactly the mental model we needed to standardize. We were treating every international payment as a one-off fire drill until we forced AP to answer those five questions before even touching the payment system.
We did the same thing and the biggest unlock was actually getting procurement and legal to agree on the currency and charge-bearer fields upfront in the PO. AP can't answer those questions if the contract doesn't specify them.
Same. We templated those five questions into our AP intake form and it cut our back-and-forth with treasury by half. The currency question alone forces people to actually read the contract instead of guessing.
Section 4 is critical but feels incomplete—what about payment-purpose codes for countries like India or China that require regulatory documentation for cross-border transfers? We've had payments stuck in compliance review for weeks because we didn't include the right category code upfront.
Good point. We now maintain a reference table of regulated corridors that flags India, China, Brazil, and a few others during payment entry. Our provider supplies the purpose-code list, but we still need AP to classify the invoice correctly before submission—which means training them on what counts as 'professional services' versus 'technical consulting' in regulatory terms, not just accounting terms.
Agree completely. India requires purpose codes for every outbound remittance, and China's SAFE documentation requirements are even stricter. We now have a pre-flight checklist by country that forces the AP team to attach supporting docs and select the correct payment category before the transfer even hits the provider. Would have saved us a lot of frozen payments early on.
The table in section 2 is useful but I'd add one more column: 'reconciliation complexity.' We've found that card and wallet payments create way more downstream work because the confirmation details don't map cleanly to our AP system's expected fields, especially when the charge posts in a different period than the invoice date.
Totally agree. We've had to build custom field mappings for each wallet provider and the variance in how they format transaction IDs versus invoice references is maddening. Wires are slower but at least the remittance data comes through structured.
Agreed. We track reconciliation effort by method and wallets consistently take 2-3x longer per transaction because the statement descriptor rarely includes the invoice reference we submit, so someone has to manually match amounts and dates. Cards are better but still require more touch than a wire with a proper remittance field.
The bit about routing policy documentation is spot on. We finally stopped the endless back-and-forth with our payment ops team by creating a simple decision matrix: SEPA for EUR in eligible countries, local rails for GBP/AUD/CAD, SWIFT for everything else unless the amount is under $500 and the vendor accepts card. Cut our payment prep time by about 40%.
The $500 threshold makes sense for minimizing fixed wire costs, but did you find vendor pushback on switching methods based on amount? We tried a similar tiering approach and got friction from vendors who wanted consistency regardless of invoice size.
The $500 threshold is interesting—do you apply that to avoid wire fees, or is it more about reducing review overhead for low-risk payments? We've been debating whether to set a floor like that but haven't settled on the right amount.
The observation that a local currency balance is a funding arrangement, not a payment rail, is a subtle but important distinction that most providers gloss over. We had a vendor expecting same-day credit because we held EUR balances, but the actual payout still went through TARGET2 with standard settlement timing.
We ran into the same thing with GBP balances. Holding the currency helped with FX stability but the Faster Payments cutoff still applied, and our vendor didn't understand why 'instant' wasn't actually instant when we funded after 5pm.
Exactly this. We had the same confusion with our GBP multi-currency account—finance assumed holding the balance meant instant payout, but Faster Payments still has its own processing window and our provider's cutoff times still applied. Now we distinguish 'balance funded' from 'payment released' in our internal SLAs.
The practical workflow makes sense, but the real bottleneck in our org is step 3—vendors regularly send incomplete banking instructions or use personal email addresses we can't verify against our approved contact list. How are others enforcing the 'controlled onboarding channel' when vendors just reply to the AP mailbox with a PDF of their bank details?
We built a vendor portal that won't let them save banking details unless all required fields for their country/method are filled. It pushes the validation burden upstream and cuts down on the back-and-forth. Still need the callback verification step the article mentions, but at least the instructions arrive complete.
We added a required step where AP initiates the banking-details request through our procurement system, which generates a unique tokenized link. The vendor can only submit instructions through that link, and it auto-expires after 72 hours. It's not perfect but it at least gives us an audit trail and forces the conversation into a documented channel instead of random email threads.
The article's distinction between invoice currency and payment currency is critical, but I'd add that the disconnect often starts earlier—at the contract negotiation stage. If your procurement team agrees to EUR settlement but only captures USD amounts in the PO system, AP is stuck reconciling a structural mismatch that no payment provider can fix.
Completely agree. We've had the same issue where procurement locks in EUR pricing but our ERP only stores the USD equivalent at contract date. By the time AP processes the invoice months later, the variance flags trigger manual review every time. We finally added a required 'settlement currency' field that flows from contract through PO to invoice—solved most of the reconciliation pain.
Completely agree. We've had the same issue where procurement locks in EUR pricing but our ERP only accepts USD PO amounts. Now we require dual-currency entry at PO creation—contract currency plus functional equivalent—and flag any invoice where the two don't reconcile within tolerance. It's extra admin but it stops AP from having to reverse-engineer intent from incomplete records.
The warning about not changing payment currency just because your bank offers convenient conversion is critical. We had a vendor in Poland reject a USD payment on a PLN-denominated invoice because their bank applied a terrible FX rate and they ended up short on the contracted amount. Now we always confirm the settlement currency with the vendor before initiating, even if it means an extra email.
Yep, and this happens a lot with EUR invoices too. The vendor expects a specific amount in their account, and if you send USD on a EUR invoice, you're essentially shifting FX risk to them without consent. We now flag currency mismatch as a hard stop in our approval workflow.
Exactly this. The article's point about conversion basis is underrated—just because the vendor accepts USD doesn't mean they agreed to *your bank's* USD-to-PLN spread on settlement day. We now lock the currency and rate expectations into the contract terms upfront to avoid those disputes.
The section on tax forms is good but honestly understates the complexity—W-8BEN-E alone has nine entity classifications and some of our vendors have no idea which box to check. We end up doing their homework for them or delaying payment while we wait for corrected forms, and that creates its own vendor-relations problem when you're already pushing 60-day cycles.
We route any uncertain classification to our external tax advisor now, but that still takes 3–5 days and kills the payment timeline. Have you found a vendor that can pre-qualify their own W-8 status reliably, or is this just always going to be manual cleanup?
We've started requiring vendors to complete the form during onboarding before any payment is approved, with internal classification guidance based on their incorporation docs. Still not perfect but it shifted the delay upstream where it causes less friction than blocking live invoices.
The distinction between 'payment initiation' and 'receipt of funds' in the timing section is critical and often gets glossed over in contracts. We had a vendor penalty last year because our contract said 'payment due within 30 days' but didn't specify whether that meant we send the wire or they receive cleared funds—ended up costing us a 2% late fee on a six-figure invoice because the correspondent bank added three days.
We hit the same issue with a logistics provider in Singapore. Our legal team now defaults to 'funds received by beneficiary' language in all international vendor agreements, which pushes us to build in an extra 2-3 days for SWIFT transfers. It adds buffer but eliminates the ambiguity.
We now specify 'beneficiary credit date' in all contracts with net terms to avoid this exact ambiguity. The article's point about checking whether the due date means initiation or receipt should honestly be step zero in any cross-border vendor negotiation.
Would be helpful to see more detail on the routing policy documentation you mention in section 2. We're paying about 300 international vendors monthly and the method selection is still ad hoc and inconsistent across our AP team.
We created a simple matrix: SEPA-eligible vendors default to local EUR transfer, US/UK/AU/SG vendors go local rails if currency matches their bank account currency, everything else routes through SWIFT unless the amount is under $500 and the vendor accepts card. Took about two weeks to document and another month to train the team, but it cut our method-selection questions by probably 70%.
We built a simple decision tree in our payment workflow: if the vendor's country is on our local-rails list AND invoice currency matches AND amount is under threshold, route locally; otherwise escalate for wire review. Took about two weeks to document and reduced our method-selection time by half.
The point about valid formatting not proving ownership is something we learned the hard way. We now require verbal confirmation through a known contact for any new wire instructions, even when they arrive on what looks like official letterhead. Saved us from a redirected $80K payment last year.
We use a callback protocol now too, but getting procurement and AP to follow it consistently is still a challenge. The invoice gets approved upstream, lands in the queue marked urgent, and there's pressure to just execute. Do you have the verification step built into your workflow system or is it still a manual check?
We implemented the same verification step after a close call with a spoofed email that changed beneficiary details on a recurring vendor. The challenge now is getting AP to actually make the call instead of treating it as a box-ticking exercise—has your team found a way to make this feel less like overhead?
I appreciate the call-out that local currency isn't always preferable if the contract specifies USD. We have several Asian vendors who explicitly want USD because they've already hedged their exposure, and our well-meaning AP team kept trying to 'help' by converting to local currency.
We had the exact same friction. Adding a 'contracted currency' flag in our vendor master finally stopped AP from second-guessing the terms, but it took a few botched payments and angry vendor calls to get there.
Same issue here. Our treasury team finally added a field in the vendor master to flag 'contractual currency' and now AP checks that before initiating. Saved us from unwinding a bunch of mismatched payments last quarter.