

Marketplace Split Payments: From Checkout to Seller Settlement
Splitting a checkout payment is only the start. Build a marketplace money flow that keeps seller entitlements, release conditions, FX, and refunds connected through settlement.
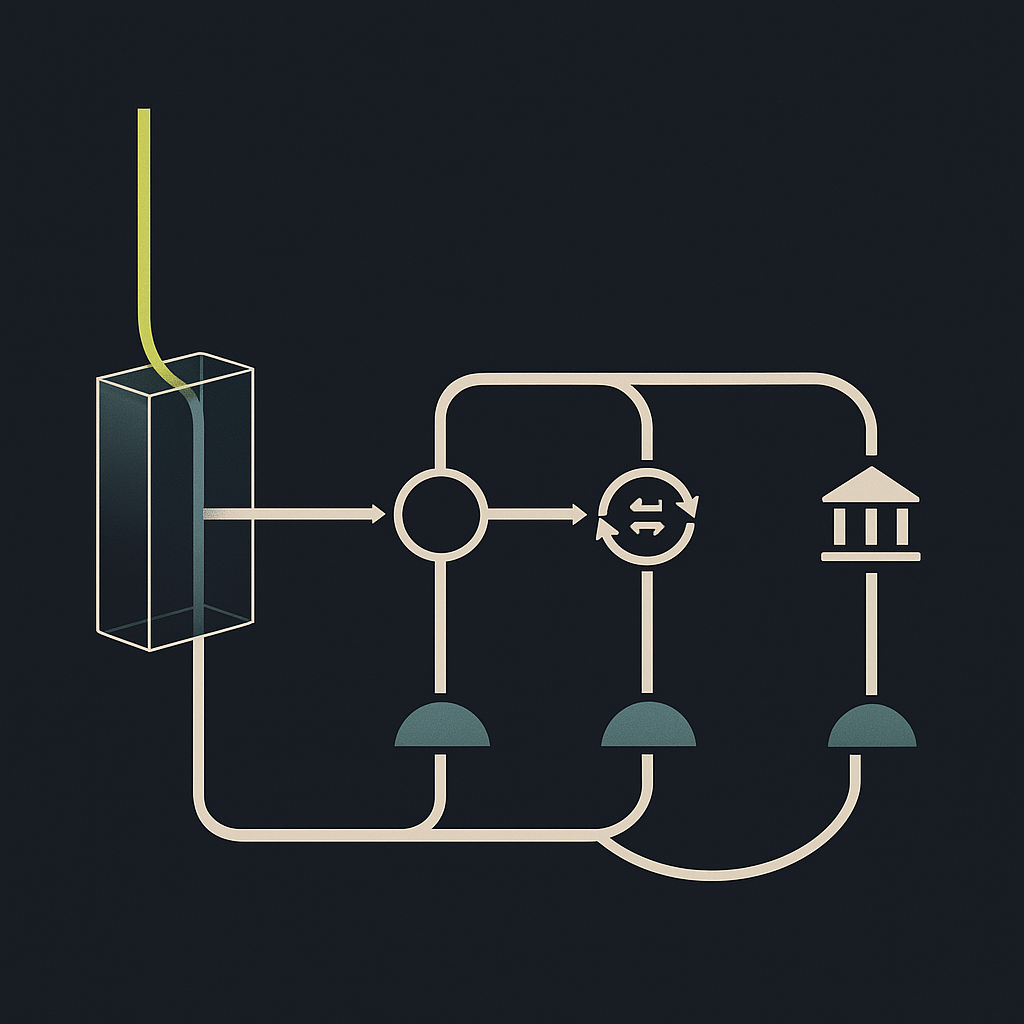
Marketplace split payments allocate a buyer’s payment among the parties entitled to it, typically sellers and the platform. Depending on the transaction, the allocation may also account for taxes, processing costs, or other partners. A payment provider can manage these allocations within its platform infrastructure, but allocating money does not necessarily mean sending it immediately to each seller’s bank account.
For finance teams paying sellers internationally, that distinction matters. The split determines who is owed money; the payout determines when, how, and in which currency they receive it. A reliable operation connects both decisions without treating a successful checkout as proof that every seller can be paid.
How marketplace split payments work
A multi-seller order creates several financial obligations from one collection. The marketplace identifies the seller behind each order line, applies the relevant commission and fee rules, and records each party’s share. The payment infrastructure then supports transfers or settlements according to the configured funds flow.
Stripe’s guide to implementing split payment systems describes the underlying requirement: distributing a payment among recipients requires payment infrastructure, allocation logic, and integration with the business’s systems. It is not simply an instruction to divide the checkout total evenly.
Keep the following events separate in your operating model. Providers may use different names for them, so map their statuses to your own ledger definitions.
| Stage | What it establishes | Required control |
|---|---|---|
| Collection | Buyer payment captured | Link payment to order lines |
| Allocation | Each party’s entitlement | Version commission and fee rules |
| Funds availability | Funds available under provider rules | Distinguish pending from available |
| Release eligibility | Seller balance approved for payout | Check holds, verification, and reserves |
| Payout execution | Payment sent toward seller | Validate destination and prevent duplicates |
| Reconciliation | Outcome matched to obligations | Match settlements, returns, and fees |
An internal allocation is not necessarily a bank transfer, a legally segregated account, or escrow. Those characteristics depend on the provider arrangement and applicable law, not the labels in a dashboard.
Choose the funds flow before writing the split rules
Provider-managed allocations and transfers
A marketplace payment provider may maintain seller balances and execute transfers under its regulated infrastructure. This can reduce the need for a marketplace to build payment infrastructure itself, but product coverage varies by platform location, seller country, currency, and transaction type.
Before selecting a model, establish who is the merchant of record, whose balance bears refunds and disputes, and which entity owes the seller. Do not assume those answers follow automatically from using connected accounts or a split-payment API.
Collection followed by later distribution
Some arrangements separate collection from seller distribution. That supports release after fulfillment or aggregation across orders, but the legal structure needs particular attention if funds enter an account controlled by the marketplace.
Receiving and forwarding third-party money can raise licensing and safeguarding questions. The analysis depends on jurisdiction, contracts, exemptions, and the actual possession or control of funds. As Stripe’s discussion of European payment regulation explains, the commercial agent exemption is a specific regulatory issue for platforms—not a general permission to handle seller money. Confirm the applicable rules and any reform transition dates with counsel rather than designing around an assumed exemption.
Architecture rule: draw the legal funds-flow diagram alongside the technical sequence diagram. Each account, balance, transfer, and liability should have an identified owner.
Build the seller ledger around entitlements
A checkout total alone cannot explain a seller balance. Store allocations at order-line level, then aggregate them for payout. Each entry should retain the seller ID, order and payment references, allocation currency, commission-rule version, tax treatment, and links to subsequent adjustments.
A practical balance model separates:
- Pending earnings: allocated amounts not yet eligible for release.
- Available earnings: amounts that meet funding and release conditions.
- Reserved amounts: seller funds withheld under the applicable agreement.
- Payouts in flight: amounts committed to a payment attempt.
- Adjustments: refunds, disputes, fee corrections, and recoveries.
Moving money into an in-flight state should remove it from the spendable balance. Otherwise, overlapping payout jobs can pay the same obligation twice.
Use balanced ledger entries and compensating adjustments rather than overwriting historical amounts. Store monetary values using currency-aware precision, and define a deterministic rounding rule so the sum of allocations always matches the amount being allocated.
Keep tax liabilities distinct from seller proceeds
A tax amount collected at checkout is not automatically seller earnings or platform revenue. Responsibility depends on the transaction and jurisdiction. Stripe’s marketplace tax guide explains how marketplace facilitator and deemed-supplier rules can place collection and remittance obligations on platforms.
Record who owes the tax and how refunds adjust that liability. Separately assign responsibility for seller reporting and documentation; payment processing does not resolve every tax obligation.
Apply FX and payout routing after the entitlement is clear
International splits introduce distinct currency decisions: what the buyer pays, what the seller is owed, and what reaches the seller’s destination account. Specify each explicitly.
Define when the seller’s exchange rate becomes fixed
If you promise a destination-currency amount at checkout but convert later, someone bears the intervening FX movement. If you convert at payout, the seller may not know the final amount until release. Neither policy is universally better; the contract, treasury process, and seller statement must agree.
Record the source amount, destination amount, applied rate, disclosed conversion cost, quote reference, and execution time. Where supported and legally appropriate, holding matching-currency liquidity can avoid unnecessary conversion. Multi-currency accounts can support that treasury workflow, but account availability alone does not establish permission to hold third-party seller funds.
Validate the seller’s actual corridor
Country coverage is not enough. Validate the combination of sending entity, seller location, destination currency, account type, payment purpose, and rail. Required beneficiary information may include local clearing identifiers, an IBAN where applicable, account-holder details, or jurisdiction-specific identifiers.
Maintain provider-validated field requirements by corridor. Collect information before release, not after a payout fails. Then choose routing based on total delivered cost, eligibility, expected availability, and return handling. The local payment rails versus SWIFT routing guide provides a framework for that decision.
Separate the release date from the expected arrival date. A fast domestic rail does not eliminate collection settlement, compliance checks, FX funding, or payout eligibility requirements.
Design refunds and failures before launch
Hypothetical example: a buyer purchases from two sellers in one checkout. One seller completes fulfillment and receives a payout in another currency. The other item is canceled while its seller’s allocation remains pending.
The cancellation should reverse the affected order-line allocation and adjust the associated commission and tax treatment. It should not reduce both sellers’ balances proportionally simply because they shared a checkout.
If the fulfilled item is subsequently refunded, the seller’s money has already left. The platform needs a contractual recovery mechanism, such as an available reserve or permitted offset against future earnings. The buyer refund and seller recovery are separate financial events; one can succeed while the other remains outstanding.
For cross-currency refunds, preserve the original conversion and book the refund conversion separately. Define who bears FX differences rather than silently changing historical seller earnings.
- Ambiguous payout status: investigate or query the provider before retrying; a timeout is not proof of failure.
- Returned payout: restore availability only after the return is confirmed and applicable fees are reconciled.
- Changed bank details: revalidate the beneficiary and apply appropriate approval controls before release.
- Dispute after payout: record the platform exposure and seller recovery separately, according to the agreement.
For operational recovery patterns, see the multi-currency failed-payment recovery guide.
Marketplace split-payment launch checklist
- Approve the funds flow. Identify account ownership, regulated-provider responsibilities, and refund and dispute liability.
- Version allocation rules. Cover commissions, discounts, shipping, fees, taxes, and rounding at order-line level.
- Gate release. Require funds availability, seller verification, fulfillment conditions, and reserve checks.
- Publish currency rules. State the entitlement currency, conversion point, fee bearer, and FX treatment of refunds.
- Test exception paths. Include partial cancellations, post-payout refunds, duplicate events, expired FX quotes, and payment returns.
- Reconcile end to end. Tie order allocations to provider balances, payout attempts, bank movements, and accounting entries.
- Make statements explainable. Show gross earnings, deductions, reserves, conversion details, and payout status without implying unconfirmed receipt.
Make every seller balance explainable
The strongest marketplace split-payment design can explain what a seller is owed, why that amount is available or held, and what happened when it was sent. Faster transfers cannot compensate for unclear entitlements or missing recovery rules.
Start by tracing a multi-seller order through allocation, cross-border payout, and a subsequent partial refund. Once that flow reconciles, evaluate Payouts.com’s payout automation for the disbursement layer. Keep acquiring, legal funds custody, split accounting, and payout execution explicit in the integration scope.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
3 commentsRelated resources
Local Payment Rails vs SWIFT: Build a Corridor Routing Policy
The right payout route depends on the recipient’s currency, bank reachability, funding, and payment purpose—not just the transfer fee. Here is how finance teams can turn that decision into a repeatable corridor routing policy.
Multi Currency Payouts: A Failed-Payment Recovery Guide
A returned cross-border payment is not simply the original transaction in reverse. Learn how to preserve the recipient’s currency entitlement, manage FX differences, and retry payments without creating duplicates.
How to Reduce Cross Border Payment Fees: A Finance Playbook
Lower transfer fees do not always mean cheaper payouts. Learn how to negotiate, operationalize, and verify savings across your international payment program.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
Appreciated the section on FX timing. We let sellers choose their settlement currency but were fixing the rate at payout execution instead of allocation, which created exactly the exposure gap you flagged. Moved to locking rates when the entitlement is recorded and it's been much cleaner for both our books and seller expectations.
The distinction between allocation and payout is underappreciated. We built our first split logic assuming allocation meant settlement, and ended up double-paying sellers when refunds hit before their original payout cleared. The ledger state machine you describe would have saved us about three weeks of reconciliation hell.
Question on the commercial agent exemption point: are you seeing marketplaces actually lose that status during regulatory reviews, or is this more theoretical? We're operating in the EU and our counsel has been fairly comfortable with our setup, but your framing makes me wonder if we should be pushing harder on the specifics before PSD3 lands.