

Vendor Onboarding: From Document Collection to Approval
A complete vendor file is not necessarily an approved vendor. Build an onboarding workflow that distinguishes collected documents from verified evidence—and makes every unresolved issue actionable.
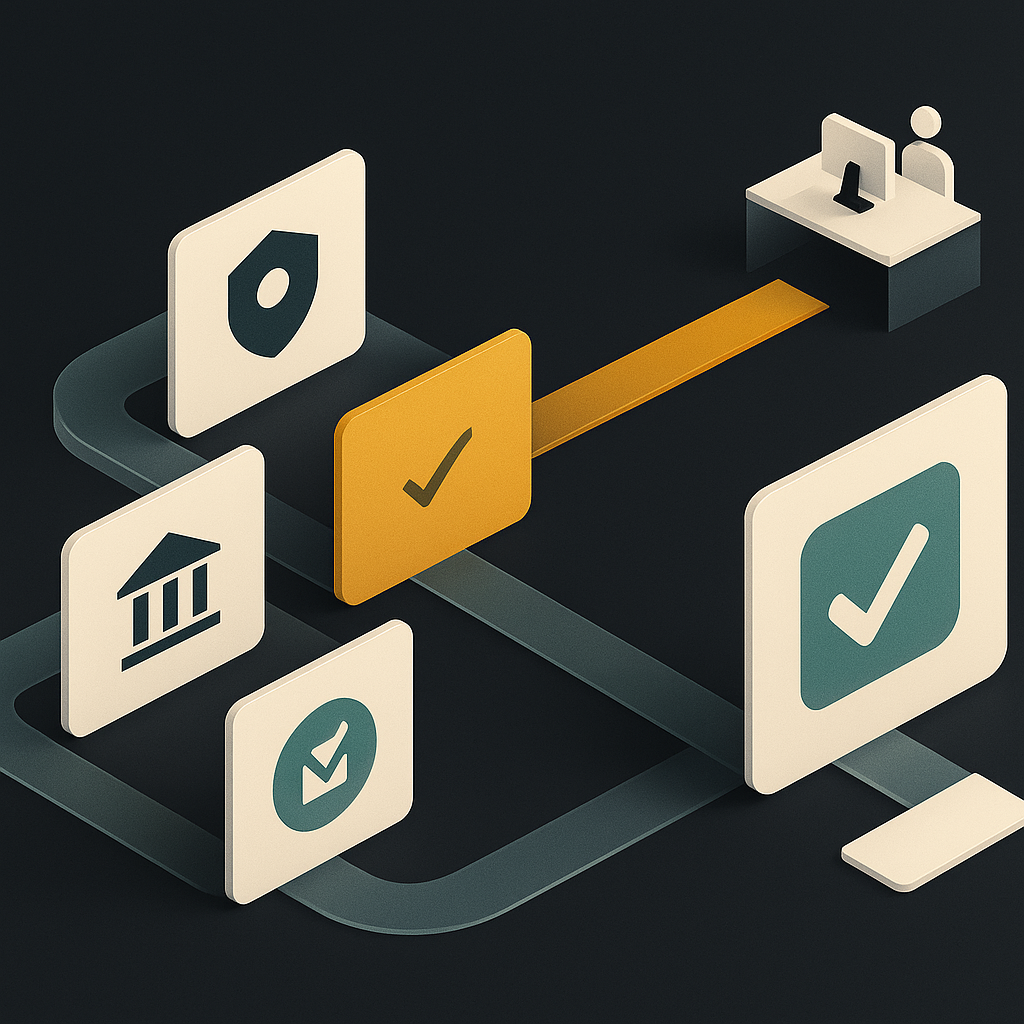
Vendor onboarding is the process of collecting a supplier’s information, verifying the evidence, completing applicable risk reviews, and approving the supplier for business activity and payment. For AP managers and compliance officers, the essential output is not a folder of documents. It is a documented decision about what the vendor is authorized to do, supported by current evidence.
A practical workflow covers business identity, tax documentation, bank details, risk-based due diligence, approval, and renewal. The most important distinction is simple: submitted does not mean verified, and verified does not automatically mean approved for payment.
Define the onboarding outcome before building the form
Start by separating permission to engage a supplier from permission to pay it. Procurement may approve a commercial relationship while AP is still resolving banking information. A tax reviewer may accept a form while compliance is investigating a potential sanctions match.
A single “complete” checkbox hides those differences. Instead, maintain separate statuses for business identity, tax review, bank verification, compliance review, and payment eligibility. Each status should identify its owner, supporting evidence, decision date, and reason for any restriction.
This structure turns onboarding into a manageable queue. AP can see whether the next action belongs to the vendor, an internal reviewer, or an external verification provider—without reopening every attachment.
A vendor onboarding checklist with acceptance criteria
Ask for information because a decision requires it, not because it appears on a generic checklist. A local goods supplier and a foreign service provider with access to sensitive data should not receive identical questionnaires.
The following is a suggested operating model, not a universal legal requirement. Assign owners to fit your organization.
| Review area | Collect | Acceptance criterion | Suggested owner |
|---|---|---|---|
| Business identity | Legal name, address, registration where applicable | Entity identified; discrepancies resolved | Vendor operations |
| Tax documentation | Applicable tax form and classification | Form appropriate, complete, and reviewed | Tax or trained AP reviewer |
| Banking | Beneficiary, account details, currency | Destination verified under bank-control policy | AP or treasury |
| Compliance | Required screening and ownership evidence | Potential matches resolved; decision recorded | Compliance |
| Service-specific risk | Relevant licenses, insurance, security evidence | Required coverage and reviews accepted | Legal or specialist reviewer |
| Activation | Approvals and system-sync confirmation | No unresolved activation blockers | Vendor operations |
Document requirements should follow the service and exposure. For example, RiskXchange’s security checklist discusses security assurance and contractual evidence relevant to technology suppliers. Those specialist checks should not become mandatory uploads for every vendor.
Collect W-9 and W-8 forms through a tax decision path
For workflows involving U.S. tax documentation, Form W-9 generally documents a U.S. person’s taxpayer identification information and certifications. Foreign persons generally provide an appropriate W-8-series form when relevant to the payment relationship.
Do not make “W-8” a single upload category with no further guidance. W-8BEN is generally for foreign individuals, while W-8BEN-E generally applies to foreign entities documenting beneficial-owner status. Other W-8 forms serve different circumstances. A foreign incorporation address alone does not establish which form applies.
Separate completeness from tax treatment
A completeness check can identify missing fields or certifications. It cannot, by itself, establish whether a treaty claim is valid or whether a payment requires withholding or reporting.
- Check that the form type fits the payee’s stated status and role.
- Reconcile the tax name with the vendor’s legal identity, accounting for legitimate differences.
- Review required taxpayer identification fields, signatures, dates, and certifications.
- Route inconsistent classifications, intermediary relationships, and treaty claims to a qualified reviewer.
- Record the tax decision separately from the uploaded document.
Do not infer U.S. tax status from bank location, or assume that every foreign-vendor payment receives the same treatment. Payment character, source, payee status, and applicable rules matter. Have tax advisers establish the decision rules; do not treat this operational checklist as a withholding determination.
Track validity by document type
W-9 forms generally do not require annual renewal solely because a calendar year has ended; changed information can require an update. W-8 validity depends on the form and circumstances, and changes in circumstances can invalidate documentation before its expected review date.
Store the signature date, applicable validity rule, next review date, and change triggers separately. Use current form instructions to configure those rules rather than applying a universal expiry period. Payouts.com’s Tax & Compliance offering addresses tax documentation and KYC/KYB within global payment workflows.
Verify banking information independently
Correctly formatted account details are not proof that the account belongs to the intended supplier. Likewise, a bank letter uploaded by the applicant is evidence to assess, not independent confirmation by itself.
Use account-validation and beneficiary-name services where available, understanding what each service actually confirms. Coverage and matching quality vary by market and institution. Where stronger verification is unavailable, use documented alternative checks and independent approval.
For a new vendor, establish contact through a channel corroborated independently of the bank submission. For later bank changes, use a previously trusted contact route—not the phone number supplied in the change request. Preserve who checked the instruction, how they checked it, and which account version they approved.
A beneficiary-name mismatch should create an exception, not an automatic rejection or silent acceptance. Trading names, group treasury arrangements, and financing relationships can explain differences, but the relationship needs evidence and approval.
Apply KYB and KYC proportionately
Know your business checks concern the entity; know your customer checks concern individuals. Ramp’s explanation of KYC versus KYB describes this distinction. In vendor onboarding, the practical question is which entity and individual checks are justified by applicable law, payment-provider requirements, and your risk policy.
Ordinary supplier onboarding does not automatically create the same AML duties as opening a regulated financial account. Sanctions obligations also depend on the jurisdiction and transaction nexus. Compliance counsel should define applicability rather than importing a financial-institution checklist wholesale.
- Baseline checks: establish identity, resolve duplicate candidates, and perform screening required by the applicable framework.
- Enhanced review: investigate opaque ownership, unexplained account relationships, or other documented risk indicators.
- Specialist review: involve security, privacy, or legal teams when the service creates additional exposure.
A screening alert is not a confirmed match. Retain the identifiers compared, disposition rationale, reviewer, and evidence. A politically exposed person connection or adverse-media result should receive an assessment, not be treated as equivalent to a sanctions prohibition.
Reduce onboarding time without removing controls
Speed comes from fewer clarification loops and better routing, not from treating unchecked uploads as approvals.
- Branch the intake. Ask early questions about entity type, tax status, service, and payment destination, then show relevant requirements.
- Validate at submission. Flag missing fields, unreadable documents, and inconsistent information before the file enters review.
- Run independent reviews in parallel. Tax and security reviews need not wait for each other when their inputs are available.
- Make exceptions actionable. Give every blocker a reason, owner, requested evidence, and escalation route.
- Confirm downstream acceptance. Do not mark activation complete until the receiving AP or ERP system accepts the approved record.
A self-serve vendor portal gives suppliers a defined place to onboard. Evaluate the surrounding workflow for secure uploads, clear correction requests, access restrictions, and visibility into outstanding actions—not just ease of form submission.
Automation can extract fields, chase documents, and route cases. It should not invent missing tax information, resolve ambiguous identity matches without an approved process, or grant itself exception authority.
Make approval expire selectively, not indiscriminately
Different changes should reopen different reviews. A new bank account should reopen banking approval. A change in legal entity may require renewed identity and tax review. An expiring insurance certificate may affect permission to perform work without necessarily determining whether already-delivered services can lawfully be paid.
Hypothetical example: a supplier has accepted tax documentation but submits a replacement account whose beneficiary differs from its legal name. Keep the tax decision intact, mark the new account as pending verification, and prevent its use until the discrepancy is resolved. Do not assume the previous account is still authorized either; confirm the intended payment route.
For every renewal or change trigger, specify what becomes restricted, who can clear it, and whether an exception is legally permissible. The related guide to AP fraud prevention controls explains why those decisions must remain effective through payment release.
Measure the bottleneck, then improve it
Track elapsed time from invitation to usable submission, internal review time, and time from approval to system activation separately. Pair speed measures with first-submission acceptance, exception reasons, reopened reviews, and payment failures attributable to onboarding data.
Start with a sample of recently completed and stalled vendors. Identify which evidence caused rework, which decisions lacked an owner, and where approved information failed to reach AP. Then revise the intake questions, acceptance criteria, and routing rules.
The goal is not to collect more documents. It is to make every requirement purposeful, every approval traceable, and every unresolved issue visible before it affects the vendor relationship or a payment.
Created with AI assistance. Sources are linked in the article; this content is general information, not legal, tax, or financial advice.
Discussion
3 commentsRelated resources
Accounts Payable Fraud Prevention Controls That Survive Payment Release
An approved invoice can still become a fraudulent payment. Build controls that preserve authorization from vendor setup through bank release—and test whether your AP software actually enforces them.
Esports Prize Pool Tax Reporting: What Gaming Platforms Must Do When Winners Are in 50+ Countries
A practitioner's guide to esports prize pool tax reporting for platforms paying winners worldwide — covering U.S. 1099 reporting, W-8BEN collection, treaty withholding, and the payout infrastructure that makes it repeatable.
Run your entire money cycle on one ledger
Global payouts, AP/AR automation, and AI agents with their own wallets and spend limits.
Get started
The distinction between "submitted" and "verified" is exactly where we used to lose vendors in limbo for weeks. We built separate swim lanes in our workflow for tax review, bank validation, and compliance screening, and the difference was immediate. AP could see what was blocking activation without asking the vendor to resubmit everything.
"Correctly formatted account details are not proof that the account belongs to the intended supplier" - this should be printed on every AP manager's wall. We got burned twice last year by change requests that looked perfect but came through compromised email threads. Now we require callback verification on a number we already have on file, no exceptions.
Curious how most teams are handling the W-8 variations in practice. We still see vendors uploading W-8BEN-E with missing Part III beneficial owner info, and our AP team doesn't have the tax training to evaluate treaty claims. Do you route every single foreign vendor form to external tax advisors, or have you built internal decision trees that cover the common cases?